Inflation caution holds
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
iFlow asset allocation indicators suggest investors remain alert to price pressures, despite easing inflation risks from energy and labor markets. Fed hikes remain in play, pushing cross-border dollar exposure near multi-year highs. In equities, investors remain reluctant to cut inflation beta in industry allocations, even as breakevens move back toward the Fed’s target. Crucially, short utilization in both sovereign and corporate bonds is at year-to-date highs, embedding steepening risk within duration. Taken together, financial conditions remain tight and continue to pose a risk to sentiment.
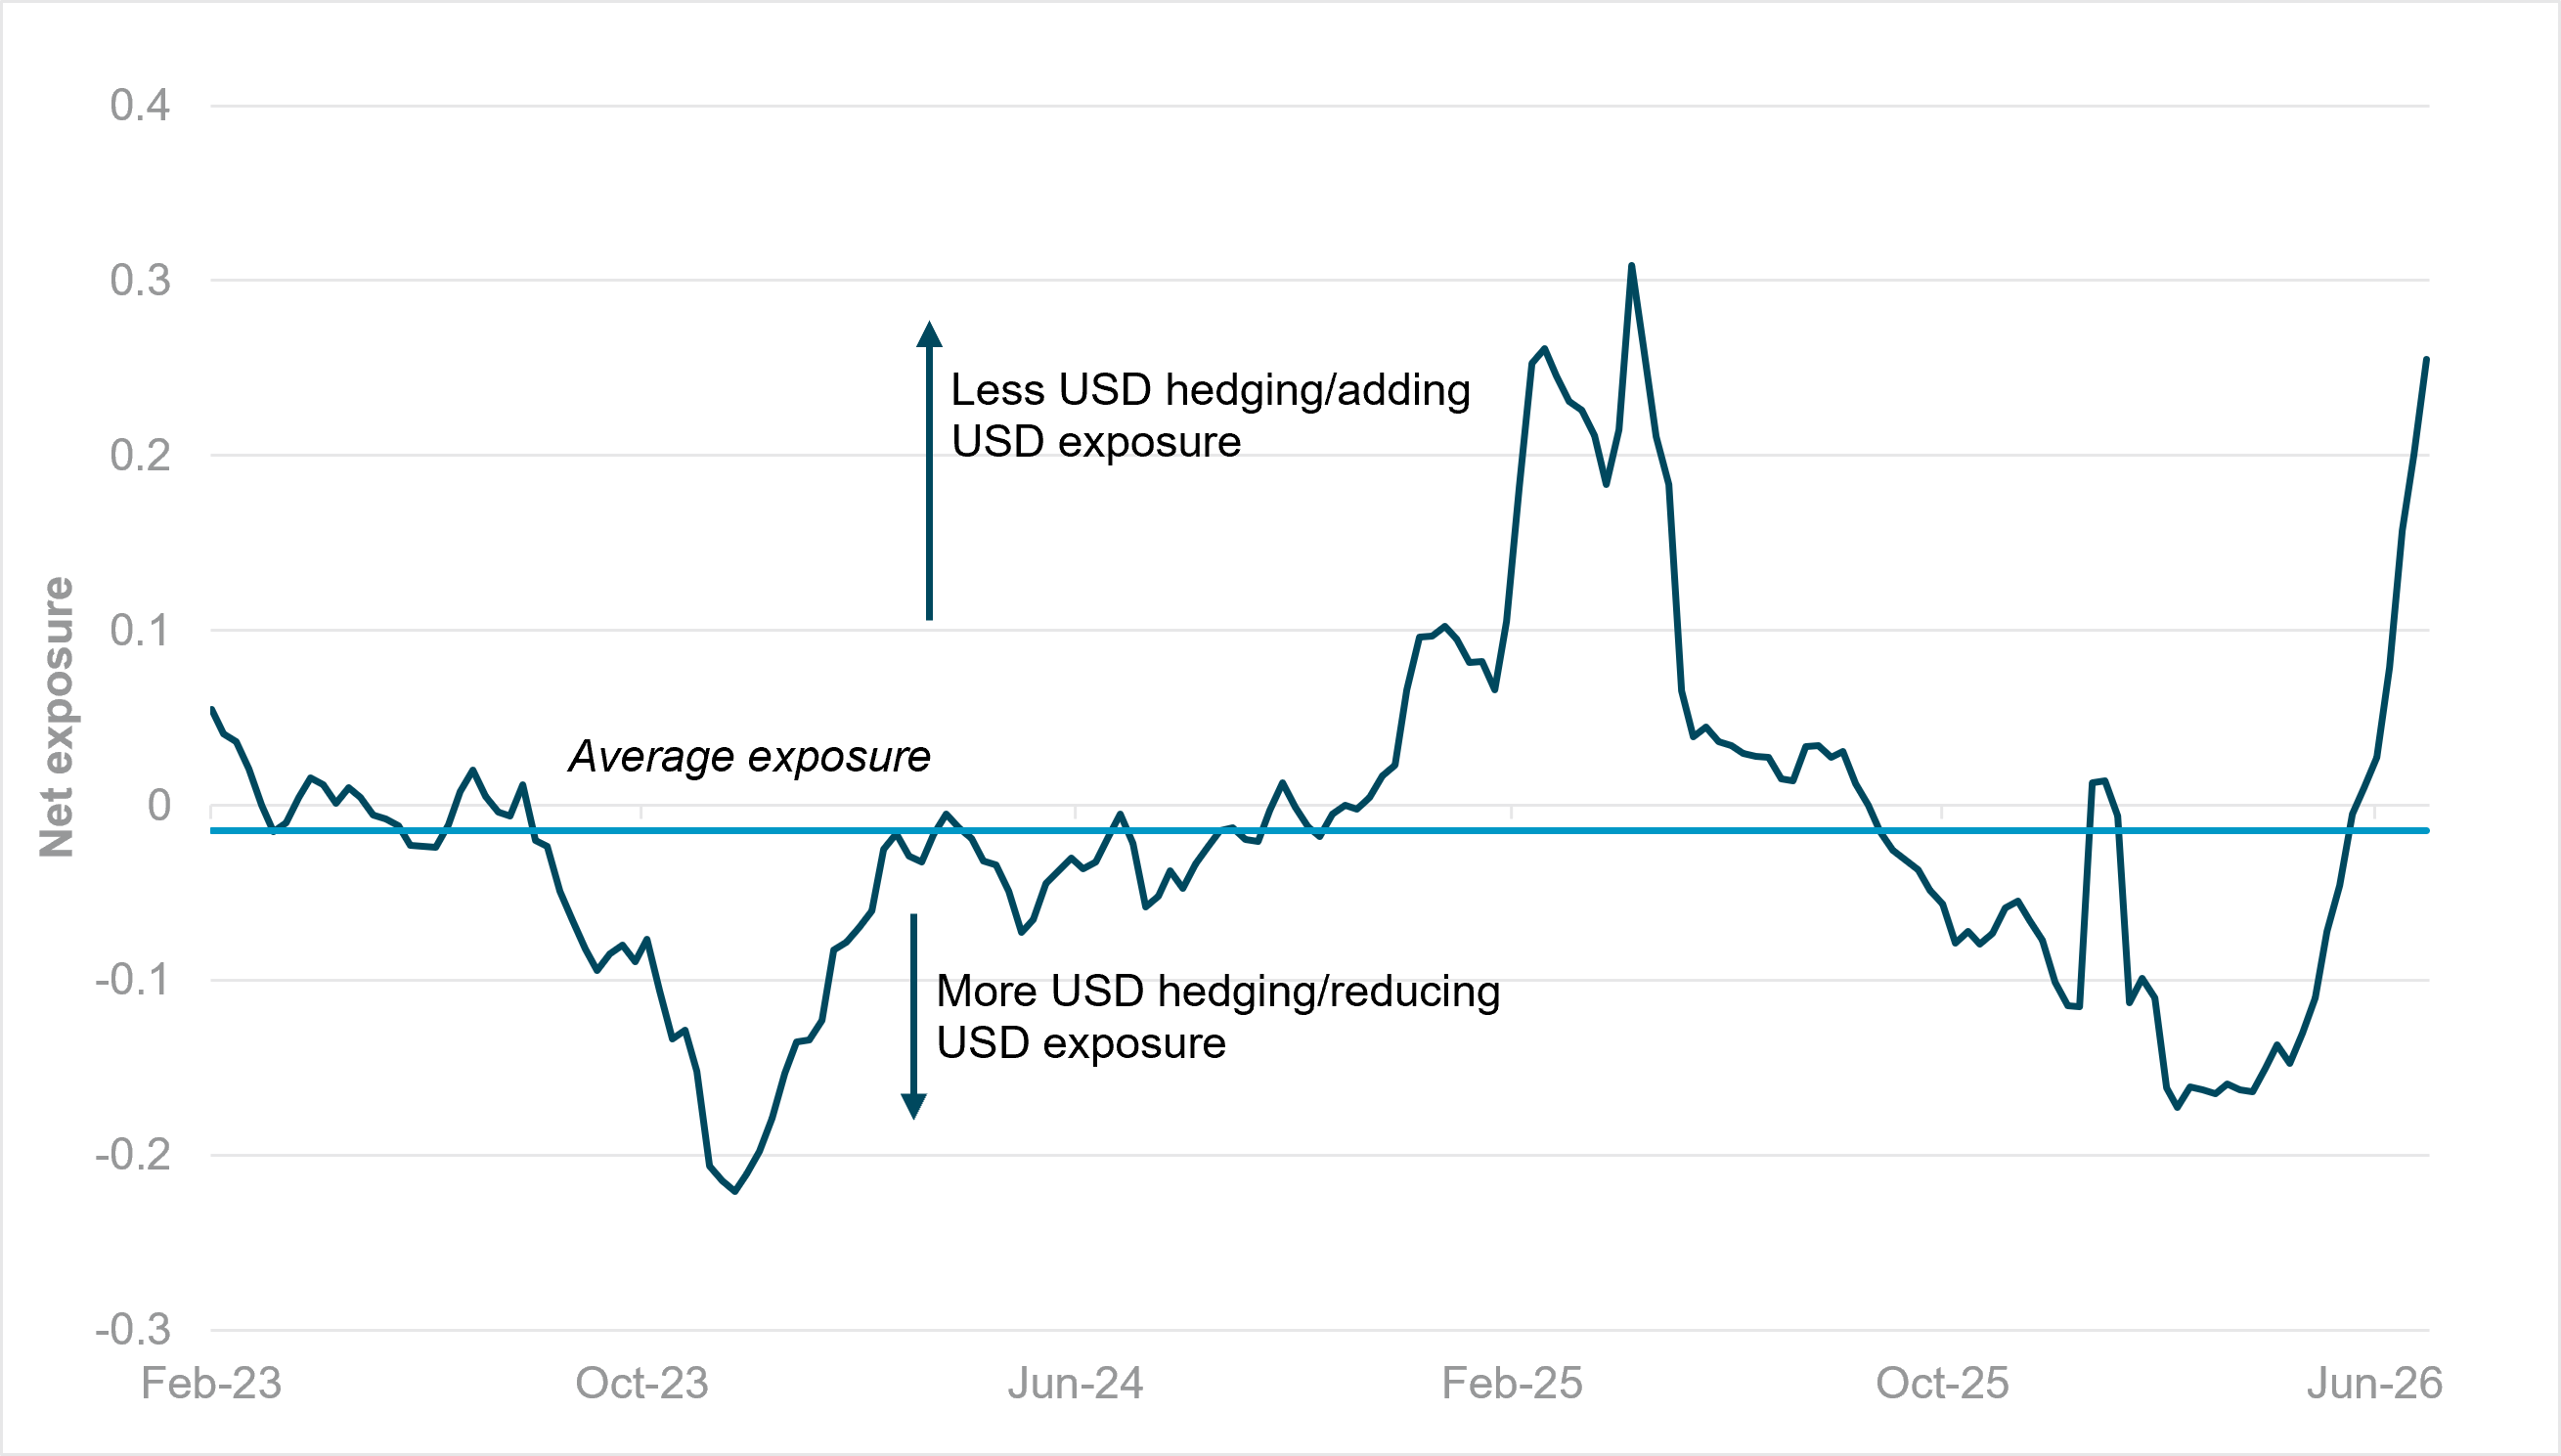
EXHIBIT #1: NET CROSS-BORDER USD EXPOSURE (60:40 TREASURYS VS. EQUITIES PORTFOLIO)
Source: BNY
Our take
Fed expectations have not moved materially over the past week, but cross-border investors’ aggregate dollar holdings remain at their highest level since April 2025. That comparison needs caveating: the April episode was distorted by the extreme moves around the Liberation Day tariffs. Today’s dollar exposure is different. It’s being driven less by outright safe-haven demand than by elevated U.S. asset exposure without accompanying FX hedges.
The first phase of hedge reduction reflected safe-haven flows around the U.S.–Iran conflict. By late Q2, however, Fed expectations had become the dominant driver, with the dollar’s yield advantage making hedges increasingly expensive. That advantage now looks durable. The ECB is stepping back from additional tightening, China is effectively easing, and other major central banks show little appetite to push hikes further. For the Fed, a stronger dollar also helps dampen imported inflation through pass-through effects.
Forward look
Unhedged asset flows are still a currency risk. FX balances may be secondary to asset performance for now, particularly in externally owned sectors such as tech, but concentrated asset weakness could quickly challenge the “U.S. exceptionalism” narrative. Some of that risk could rotate into more defensive U.S. sectors, rather than out of the dollar altogether. Barring a clear Fed pivot, limited alternatives should keep USD exposure well above long-term averages.
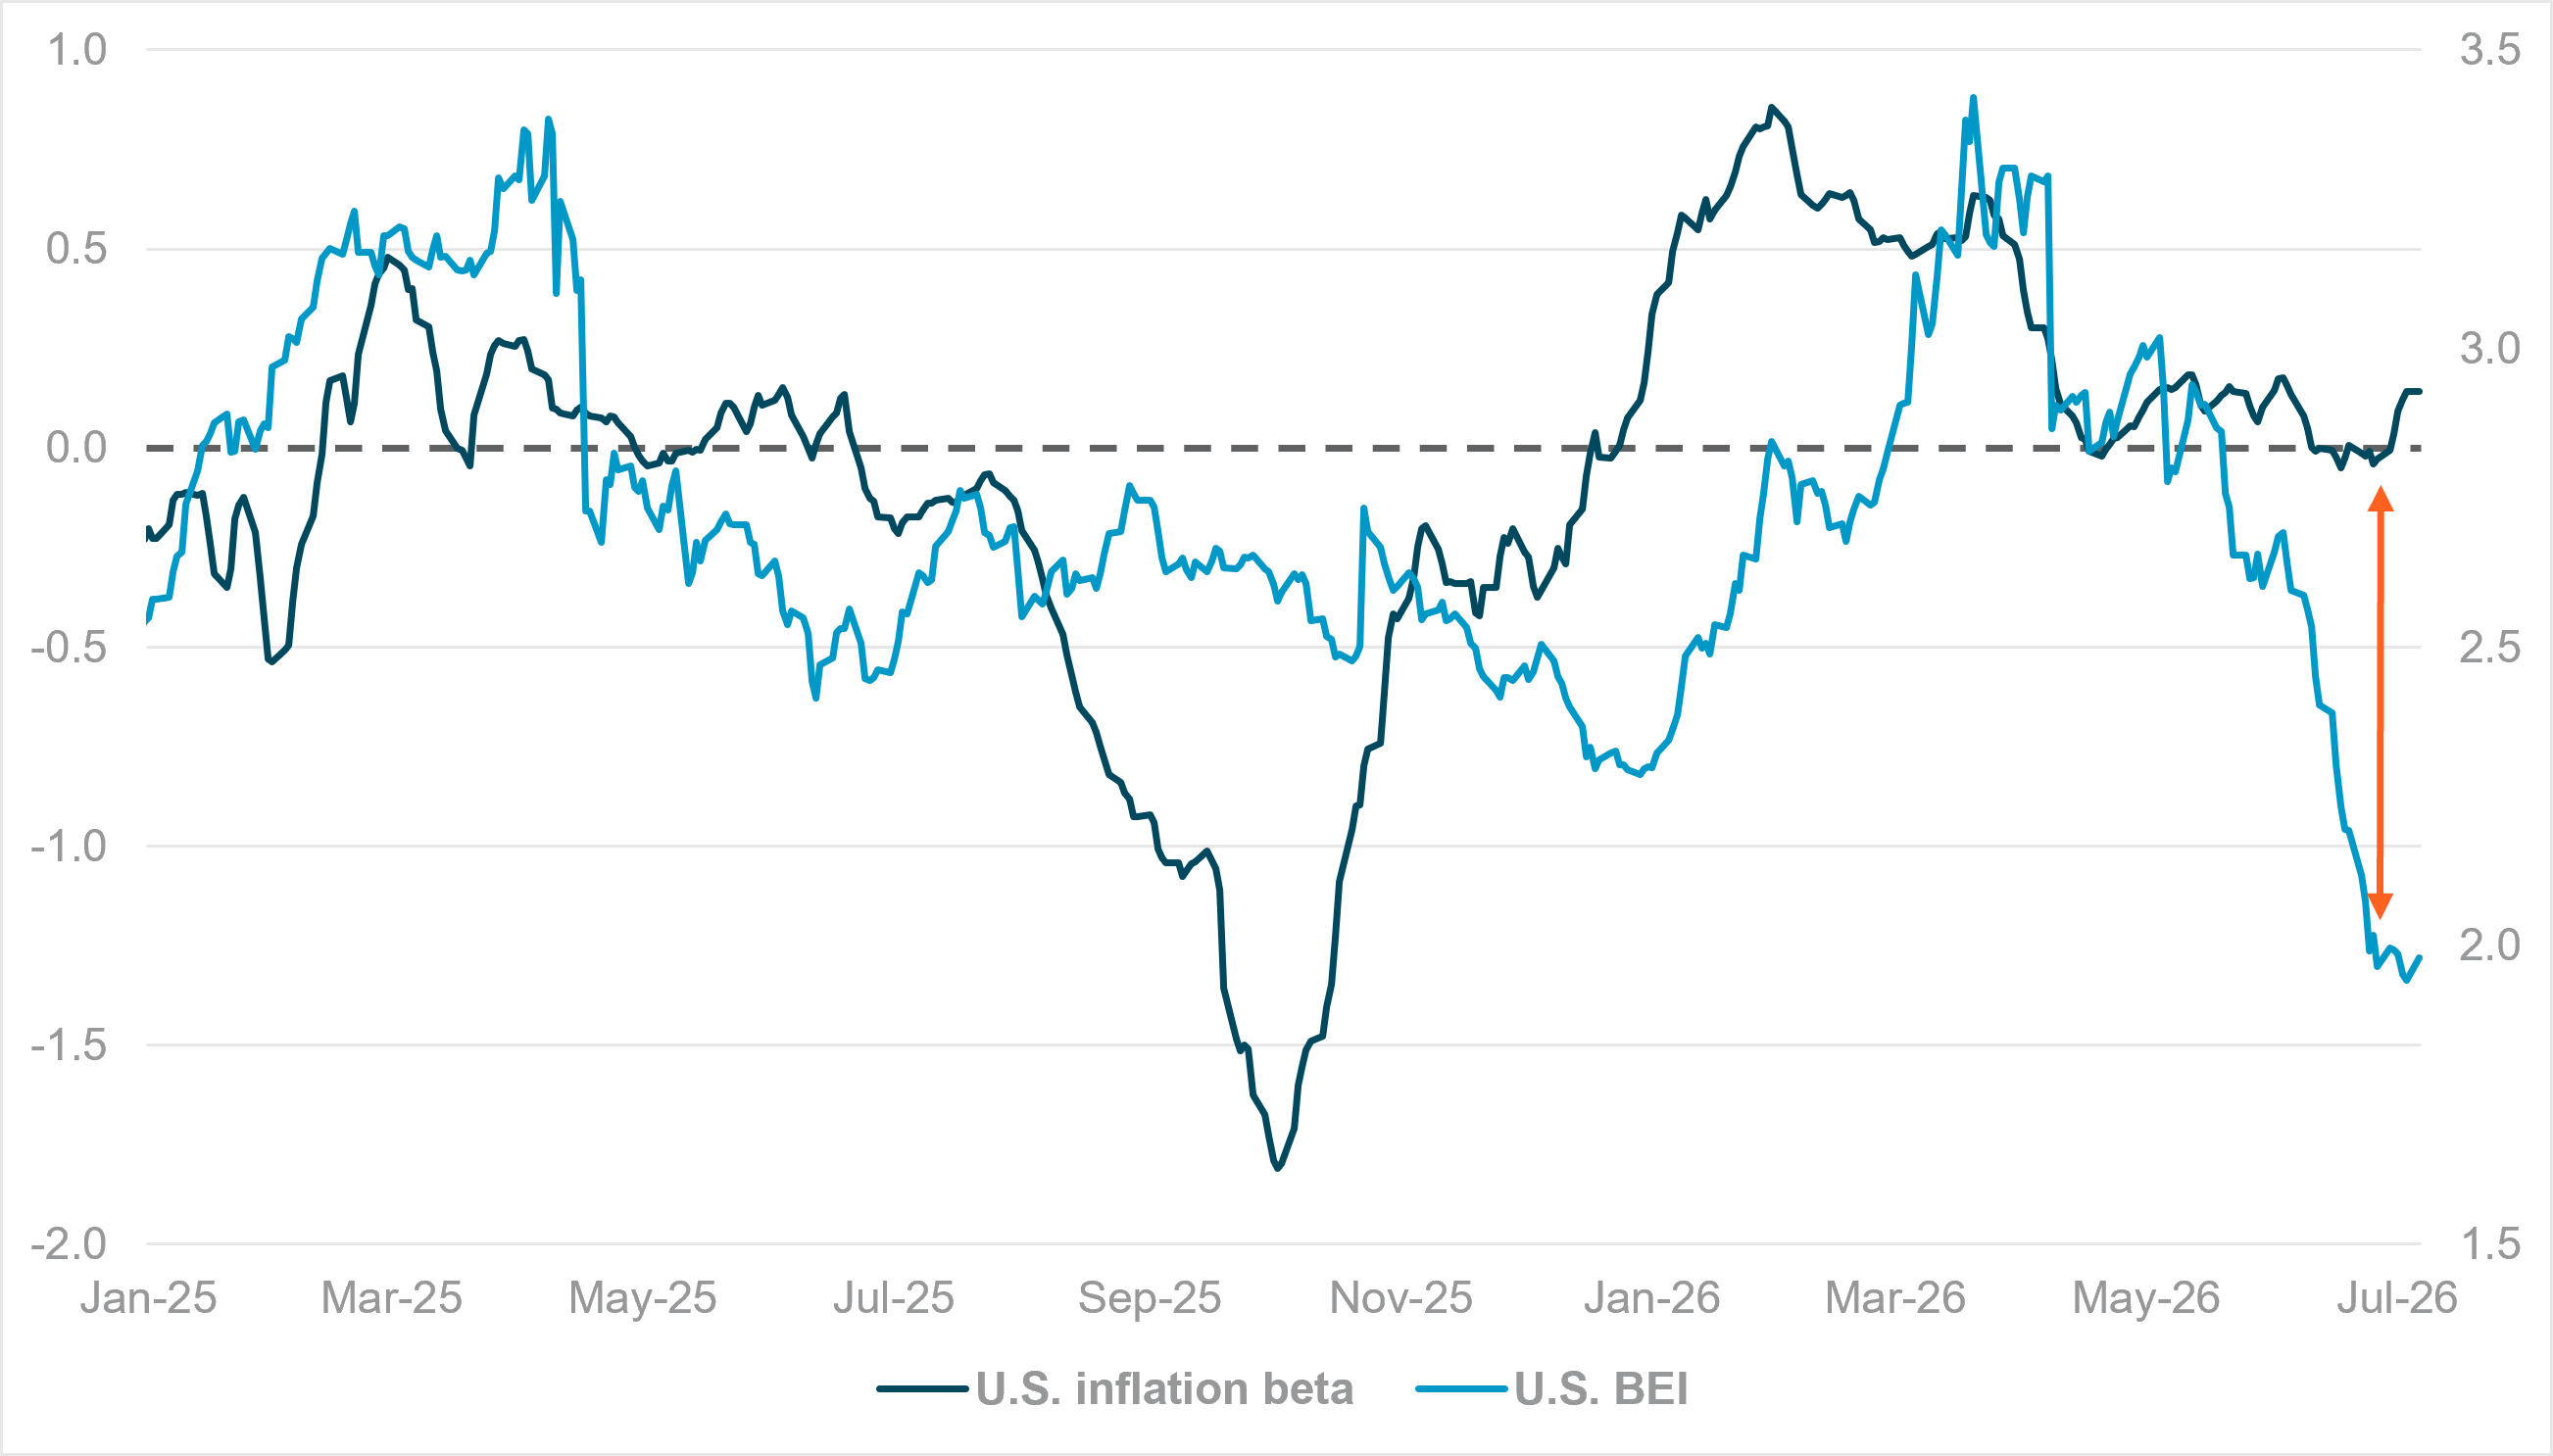
EXHIBIT #2: U.S. “SURGE” FLOWS VS. EQUITY INFLATION SENSITIVITY
Source: BNY
Our take
Client flows into U.S. equities remain sensitive to inflation risk, even as flows into the most direct inflation-hedge sectors have eased. Our iFlow equity inflation style indicator tracks this by estimating the correlation between industry-group returns and changes in the two-year breakeven inflation rate. It then compares that with accelerated flows into the same sectors. A higher regression beta signals stronger surge flows into industries with the highest breakeven sensitivity.
Before the conflict, inflation-linked equity flows were already rising on the “debasement” theme. Low real rates supported the Q1 surge in precious metals, lifting inflation beta in sympathy. Energy gains in March and April kept inflation-related flows elevated, before flows started to reverse after the ceasefire. The break came in May: breakeven inflation fell sharply as energy prices weakened, but that didn’t trigger comparable outflows from industry groups with high inflation correlations.
Forward look
The gap between inflation-related equity flows and breakevens is now the widest in 18 months. This suggests clients are willing to accept energy-led disinflation but are less convinced that broader inflation risks have cleared. We see this as continued concern around labor markets and other price pressures linked to tech-driven investment. Until those non-energy inflation risks ease, equity flows are likely to remain defensive, with investors reluctant to cut inflation beta in sector allocations.
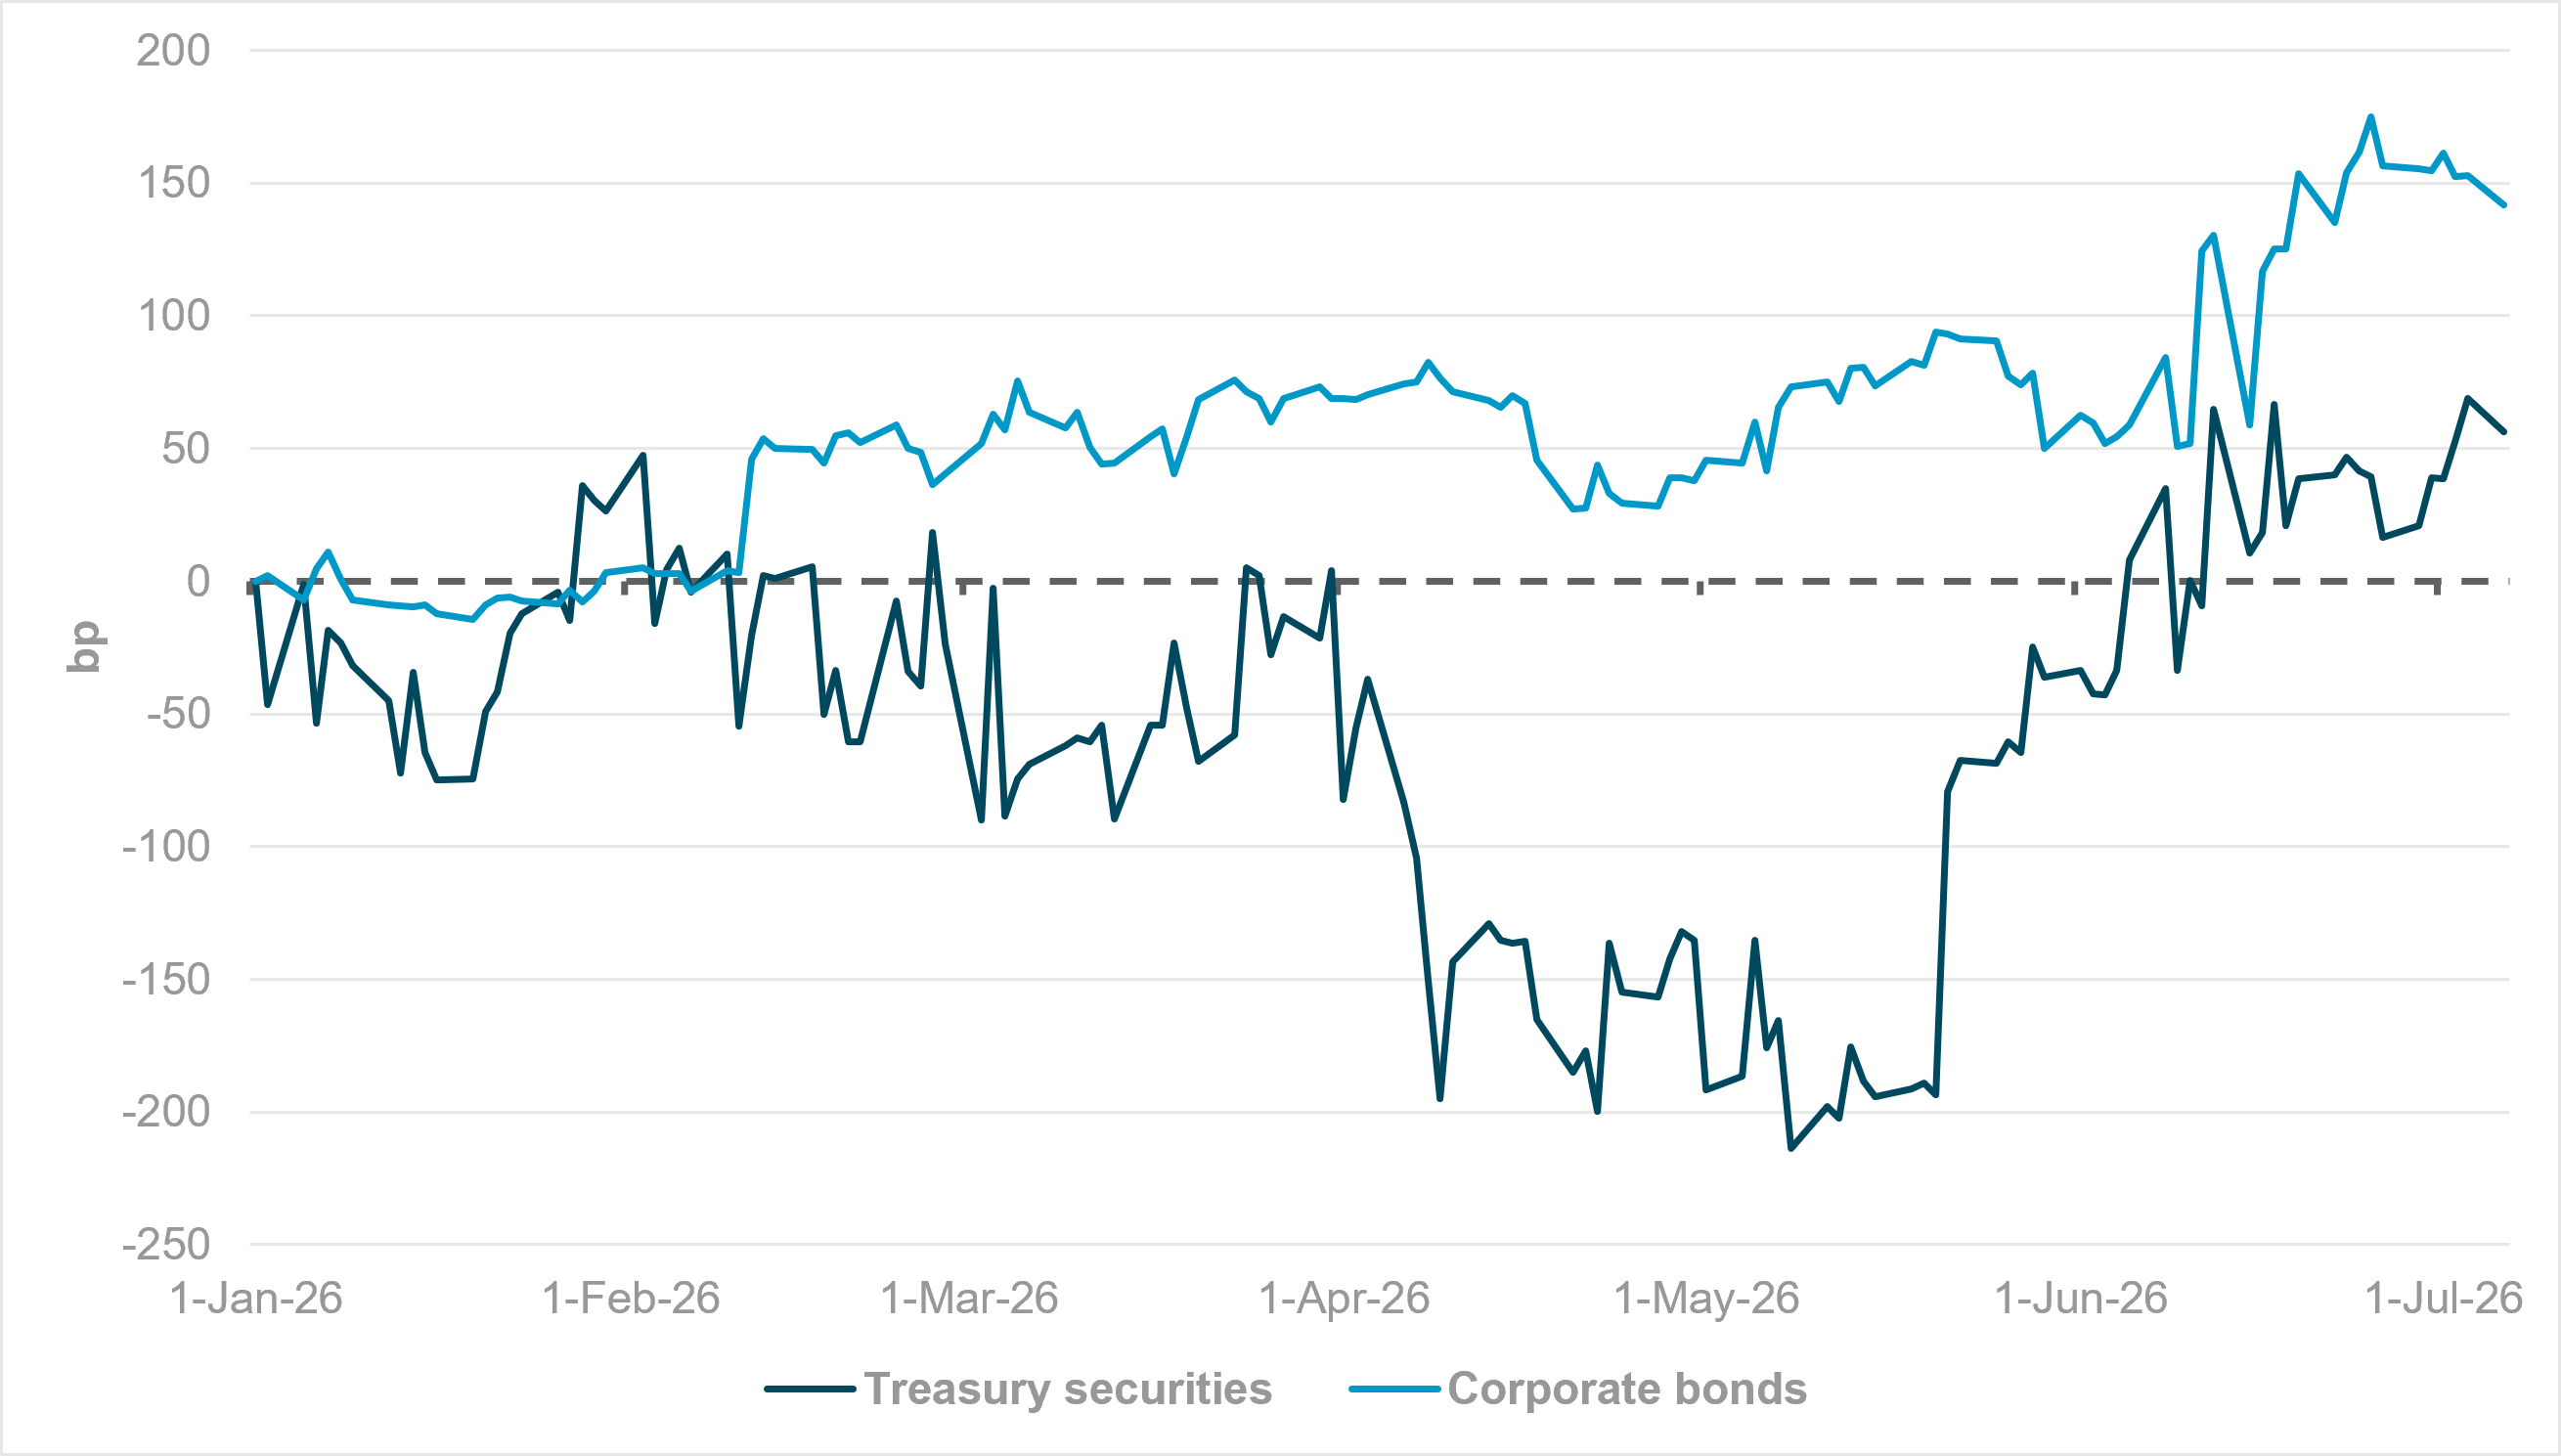
EXHIBIT #3: CHANGE IN SHORT UTILIZATION, YEAR TO DATE
Source: BNY
Our take
Bond markets remain positioned for inflation risk, and that is still a headwind for duration. The yield reaction to renewed attacks on shipping near the Strait of Hormuz shows sensitivity to supply-driven price shocks, even though central banks have signaled that they won’t overreact to them. The bigger signal, however, is domestic. iFlow short utilization – the share of bonds in the BNY lending program that have been sold short – remains elevated versus the start of the year, and the rise in Treasury short utilization since June points to Fed expectations and U.S. demand-led inflation as the dominant drivers. This matches the defensive inflation bias visible in equity sector allocations.
Corporate debt looks more vulnerable than Treasurys. Private-credit concerns have been spilling into listed corporate bonds for several quarters, but expectations of a dovish Fed had previously limited steepening positions. That changed in June. The conflict itself did not materially lift short utilization, but domestic inflation concerns did. Corporate short utilization is now 250bp higher year to date, significantly outpacing the cumulative move in Treasurys.
Forward look
Treasurys offer the cleaner risk-reward if inflation pressure fades. We still expect sequential inflation relief and see scope for the current hawkish tilt in markets to recede. Relative to the dollar and U.S. equities, Treasurys should perform whether the driver is supply normalization or weaker growth. If the latter becomes the dominant driver, domestic rotation out of equities and into bonds could strengthen further, while foreign investors may prove more cautious as yields soften. Such flows will also drive an over-owned dollar lower. We remain more cautious on corporate debt, where softer growth could amplify credit-quality concerns.
Inflation-risk positioning looks overextended. If the data continue to validate disinflation, investors should look to fade that exposure by adding dollar hedges and positioning for curve flattening. Easier financial conditions should also provide support for equities, provided softer inflation reflects supply-side normalization rather than a material weakening in demand.