Finding JPY’s marginal buyer
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 5 minutes
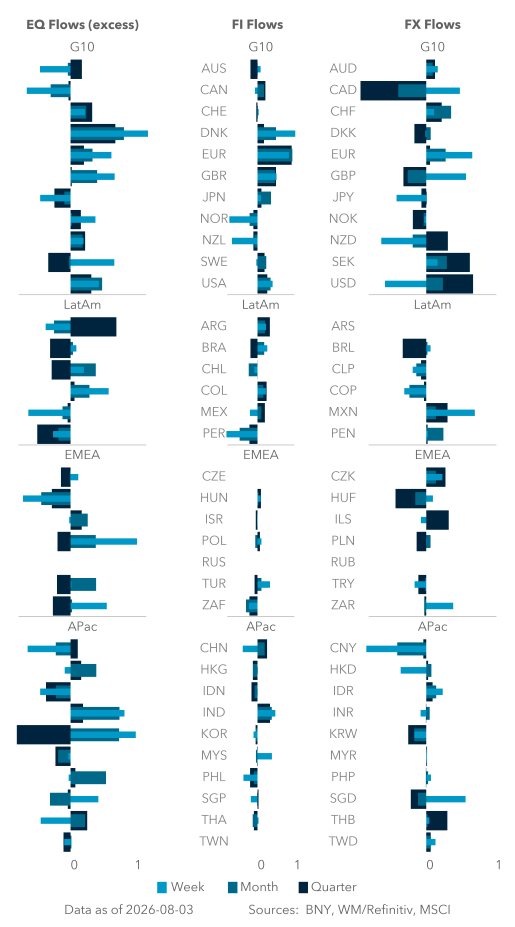
Coordinated intervention has bought time but hasn’t materially increased foreign JPY holdings. Investors remain net long JPY, but exposure is well below H1 2026 levels and won’t rebuild without credible domestic follow-through: Bank of Japan (BOJ) tightening, fiscal consolidation and structural reform. Japanese equities remain largely passive and under-supported, while Japanese government bonds (JGBs) are attracting the clearest marginal demand. Insurers, government institutions and central banks are adding duration as yields rise, provided the move remains orderly and doesn’t reflect worsening fiscal credibility.
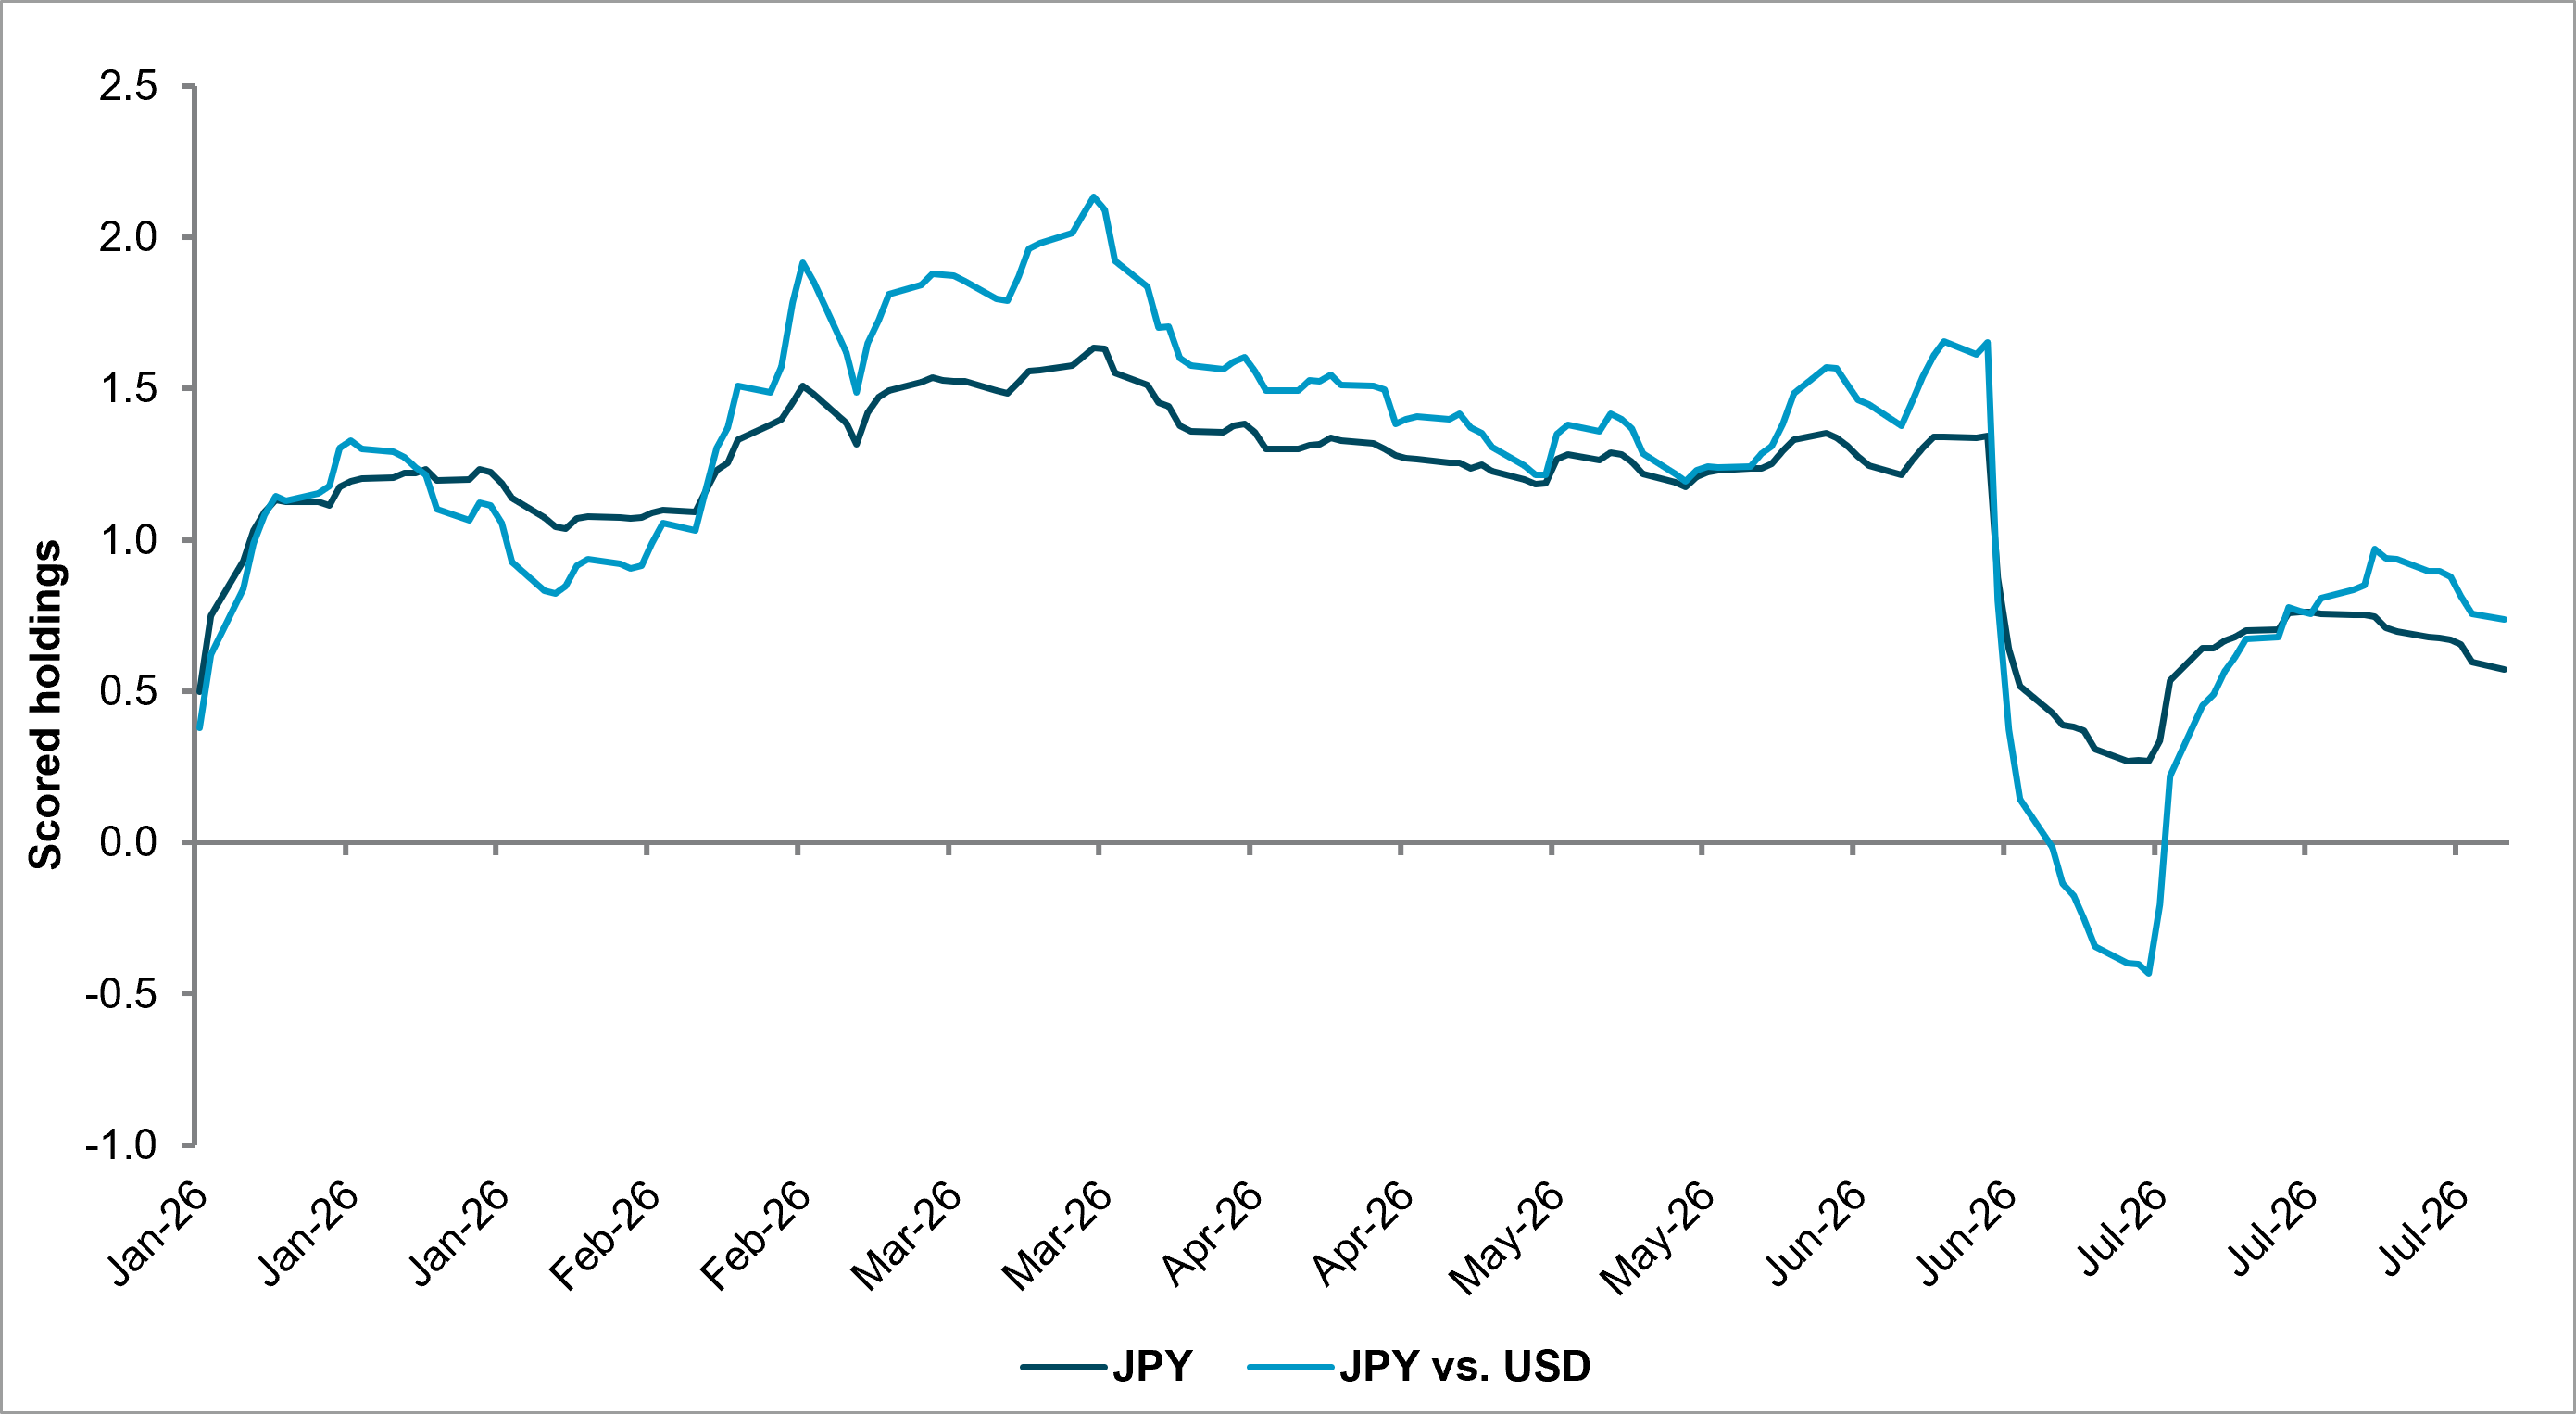
EXHIBIT #1: SCORED HOLDINGS, JPY AND USDJPY (INVERTED)
Source: BNY, Bloomberg
Our take
Coordinated intervention hasn’t materially changed cross-border JPY exposures, based on our latest data. Apart from a very strong volume day last Friday when both the Ministry of Finance (MOF) and the U.S. Treasury Department entered markets, there was no discernible impact on holdings. Measured on a JPY aggregate and USDJPY basis, current holdings remain net positive for the JPY but at far lower levels compared to H1 2026. Before the recent round of intervention, fears over renewed balance-of-payments stress and lack of policy tightening even pushed USDJPY into net long (i.e., underheld JPY vs. USD) briefly. We also note that the April intervention did little to accelerate JPY holdings, albeit they were already elevated at the time due to attractive valuations.
Forward look
On Tuesday, Treasury Secretary Scott Bessent admitted as much that intervention can give “market signals” but ultimately Japan was “going to need policy follow-up.” It’s not Treasury’s job to manage Japan’s exchange rate, but the signaling is clear: the U.S. now expects measures – such as further BOJ rate hikes, fiscal consolidation and structural reform – to drive up the JPY’s real rates and attract greater foreign portfolio flows while keeping savings onshore.
Our data indicate that investors wish to maintain net positive cross-border exposure to JPY, but developments in recent months, both due to external shocks and domestic credibility issues, have weakened resolve. U.S. support provides an opening for re-accumulation, but we believe the market will agree with Bessent that any structural shift in holdings will depend on credible domestic policy changes.
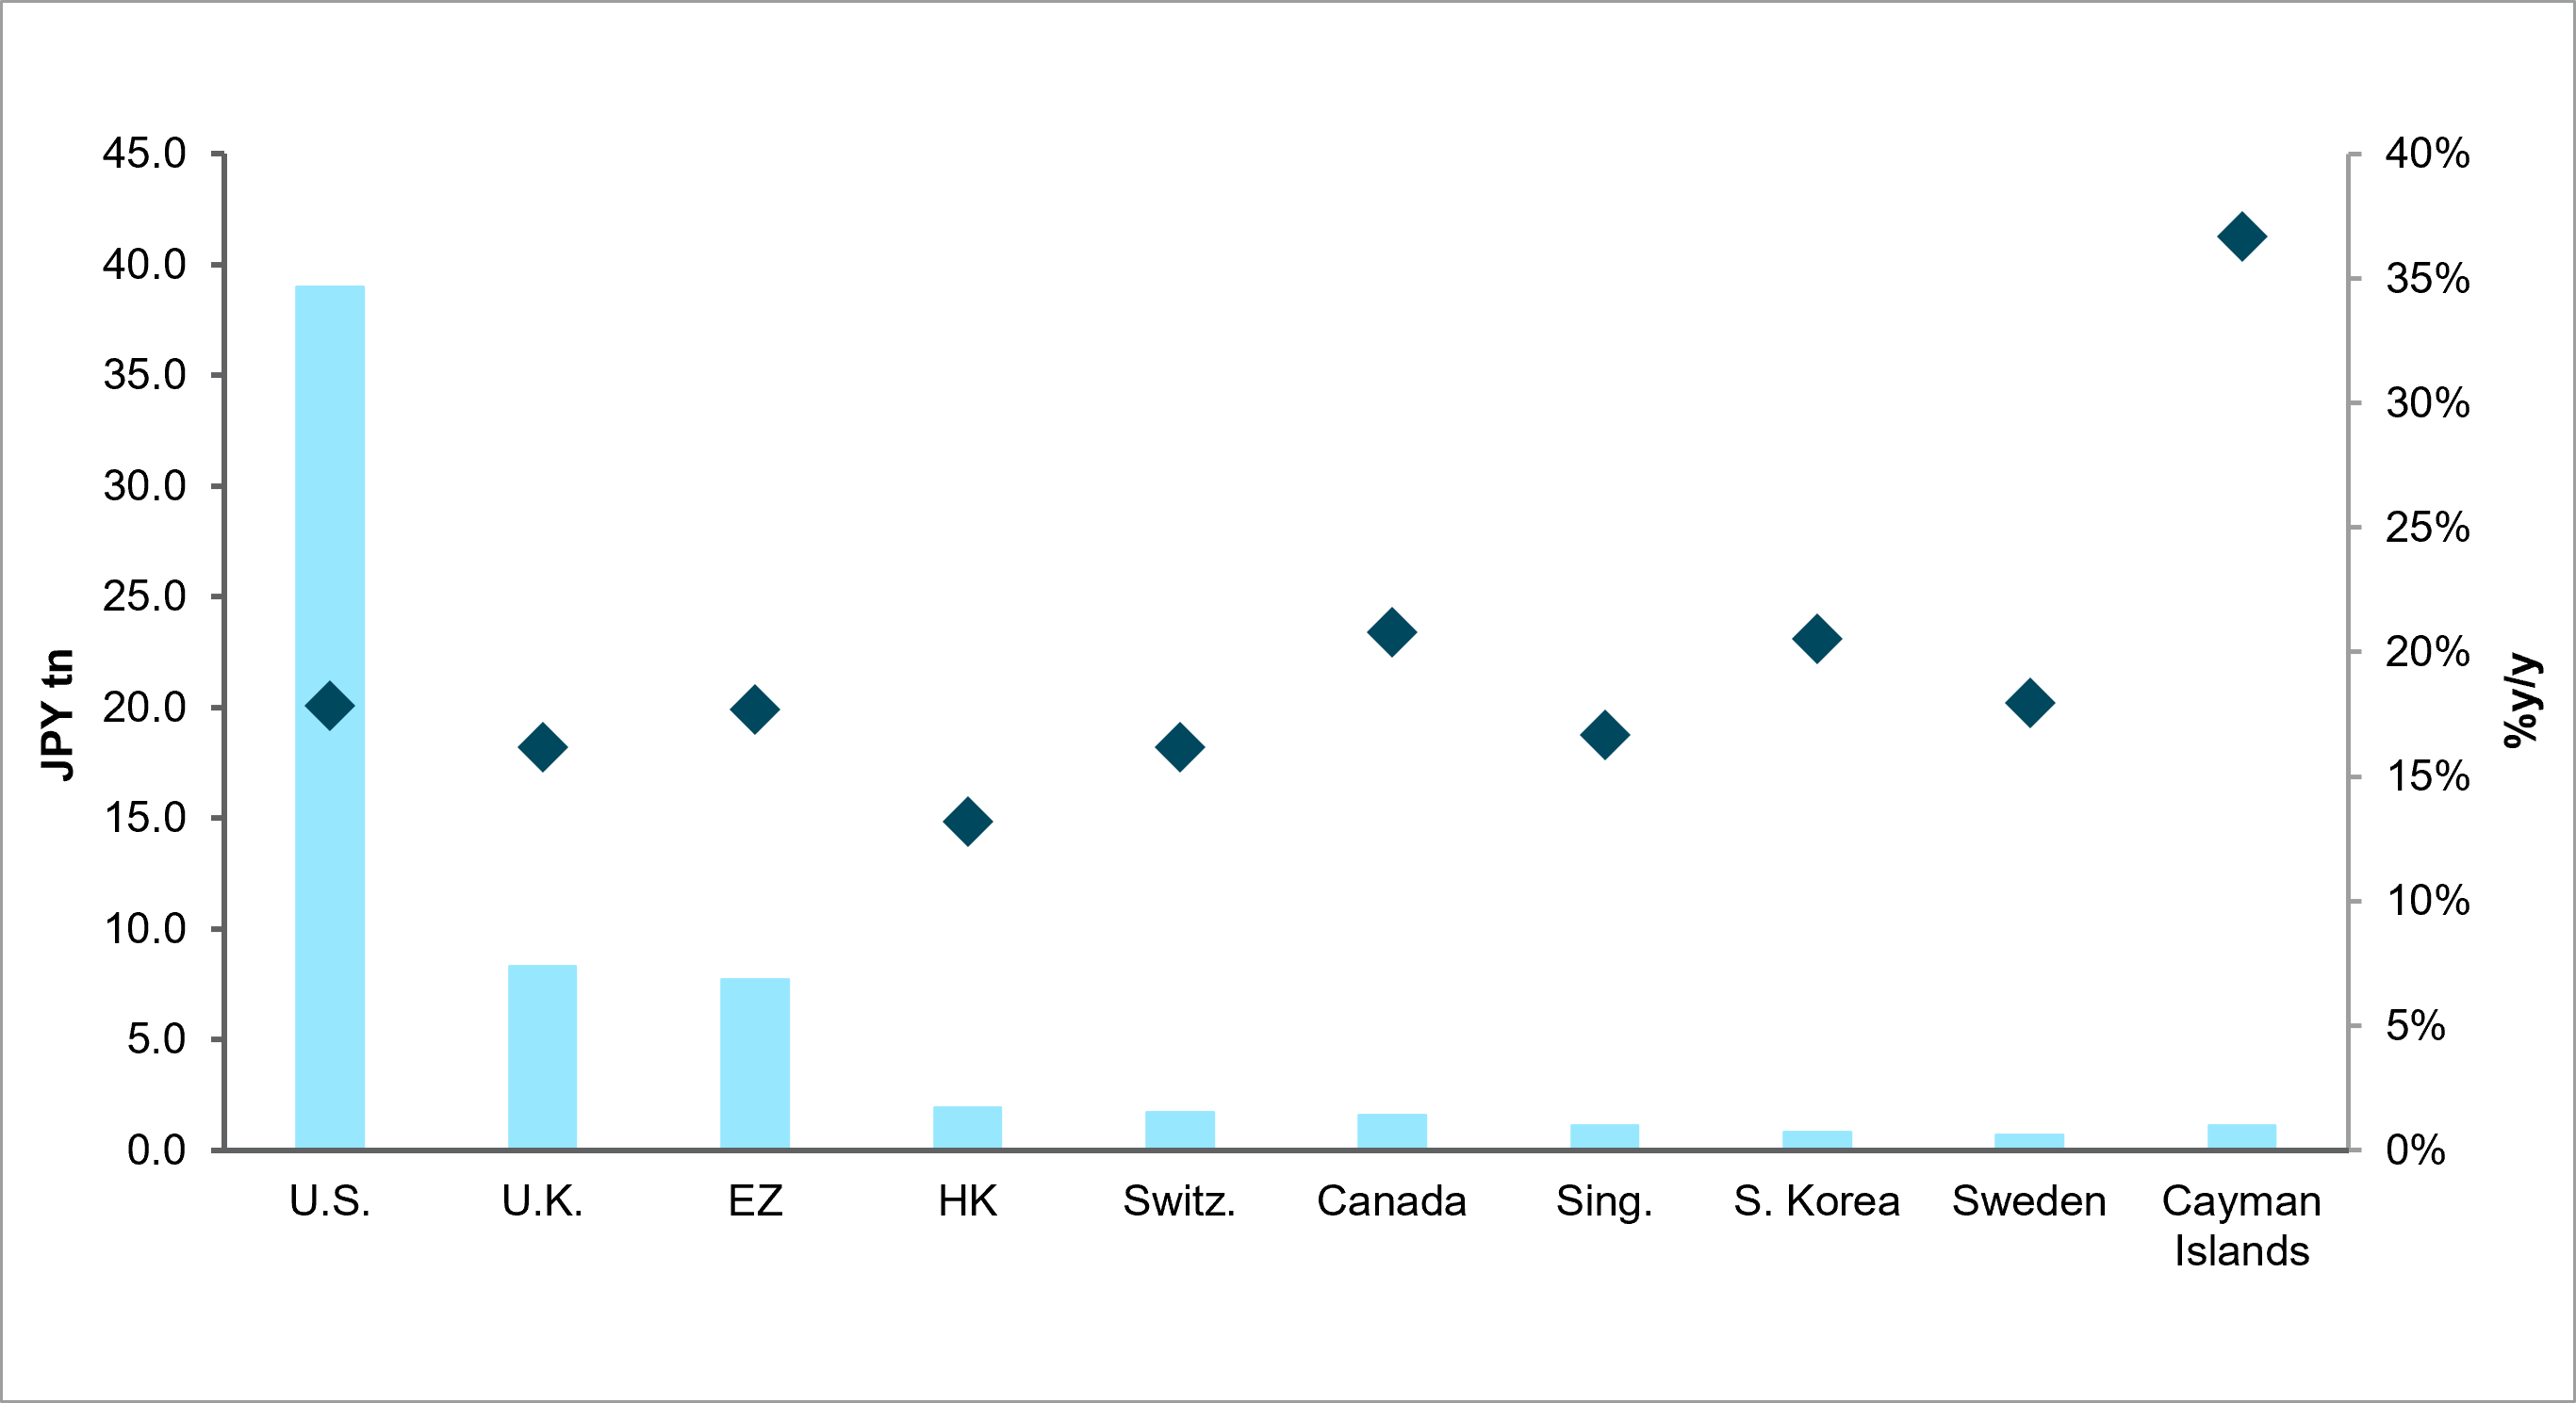
EXHIBIT #2: CHANGES IN HOLDINGS OF JAPANESE EQUITIES BY CROSS-BORDER INVESTORS, END-2025
Source: BNY, Japan Ministry of Finance
Our take
In our recent special report on Japan’s intervention, we highlighted that interest in owning JPY and JGBs (see below) is already emerging. Equities remain the weak link. Despite its industrial prowess, Japan hasn’t been as prominent in the semiconductor/memory chip theme as Taiwan and South Korea. As those two markets surged in value, asset allocation restrictions may have represented serious barriers against increased flows into Japan, especially for discretionary managers treating them as developed APAC rather than EM. The recent correction does create space for Japan, if a long-term growth and earnings narrative can be established. The initial reaction to JPY strength would also undermine Japanese equities due to earnings translation. Equities also comprise the bulk of cross-border portfolio investment in Japan (63% as of end-2025), so any rebalancing will likely favor the JGB market.
Forward look
Japanese survey data as of end-2025 don’t point to a surge flow story. In JPY terms, based on the MSCI Japan Index, Japanese equities returned 22% over the year. The median gain in holdings by key international investors was 17%, somewhat behind benchmarks (Exhibit 2). The only surge flow was seen in the Cayman Islands, likely reflecting more tactical positioning by hedge funds through offshore intermediaries. “Sticky money” remains relatively cautious; recent developments are unlikely to change this view.
The U.S. and Europe account for nearly 90% of all international equity holdings in Japan, totaling nearly ¥320tn as of the end of 2025. Rather than respond to the earnings outlook, structural shifts in hedge ratios will have the biggest impact, especially if front-end rates show closer sign of alignment. However, currency markets will need to be realistic about the numbers. Every 10pp reduction in hedge ratios will result in a net increase in JPY exposure of around $200bn, which only represents around two to three rounds of monthly intervention – enough to help consolidate tactical gains, but not sufficient to become the marginal buyer or seller.
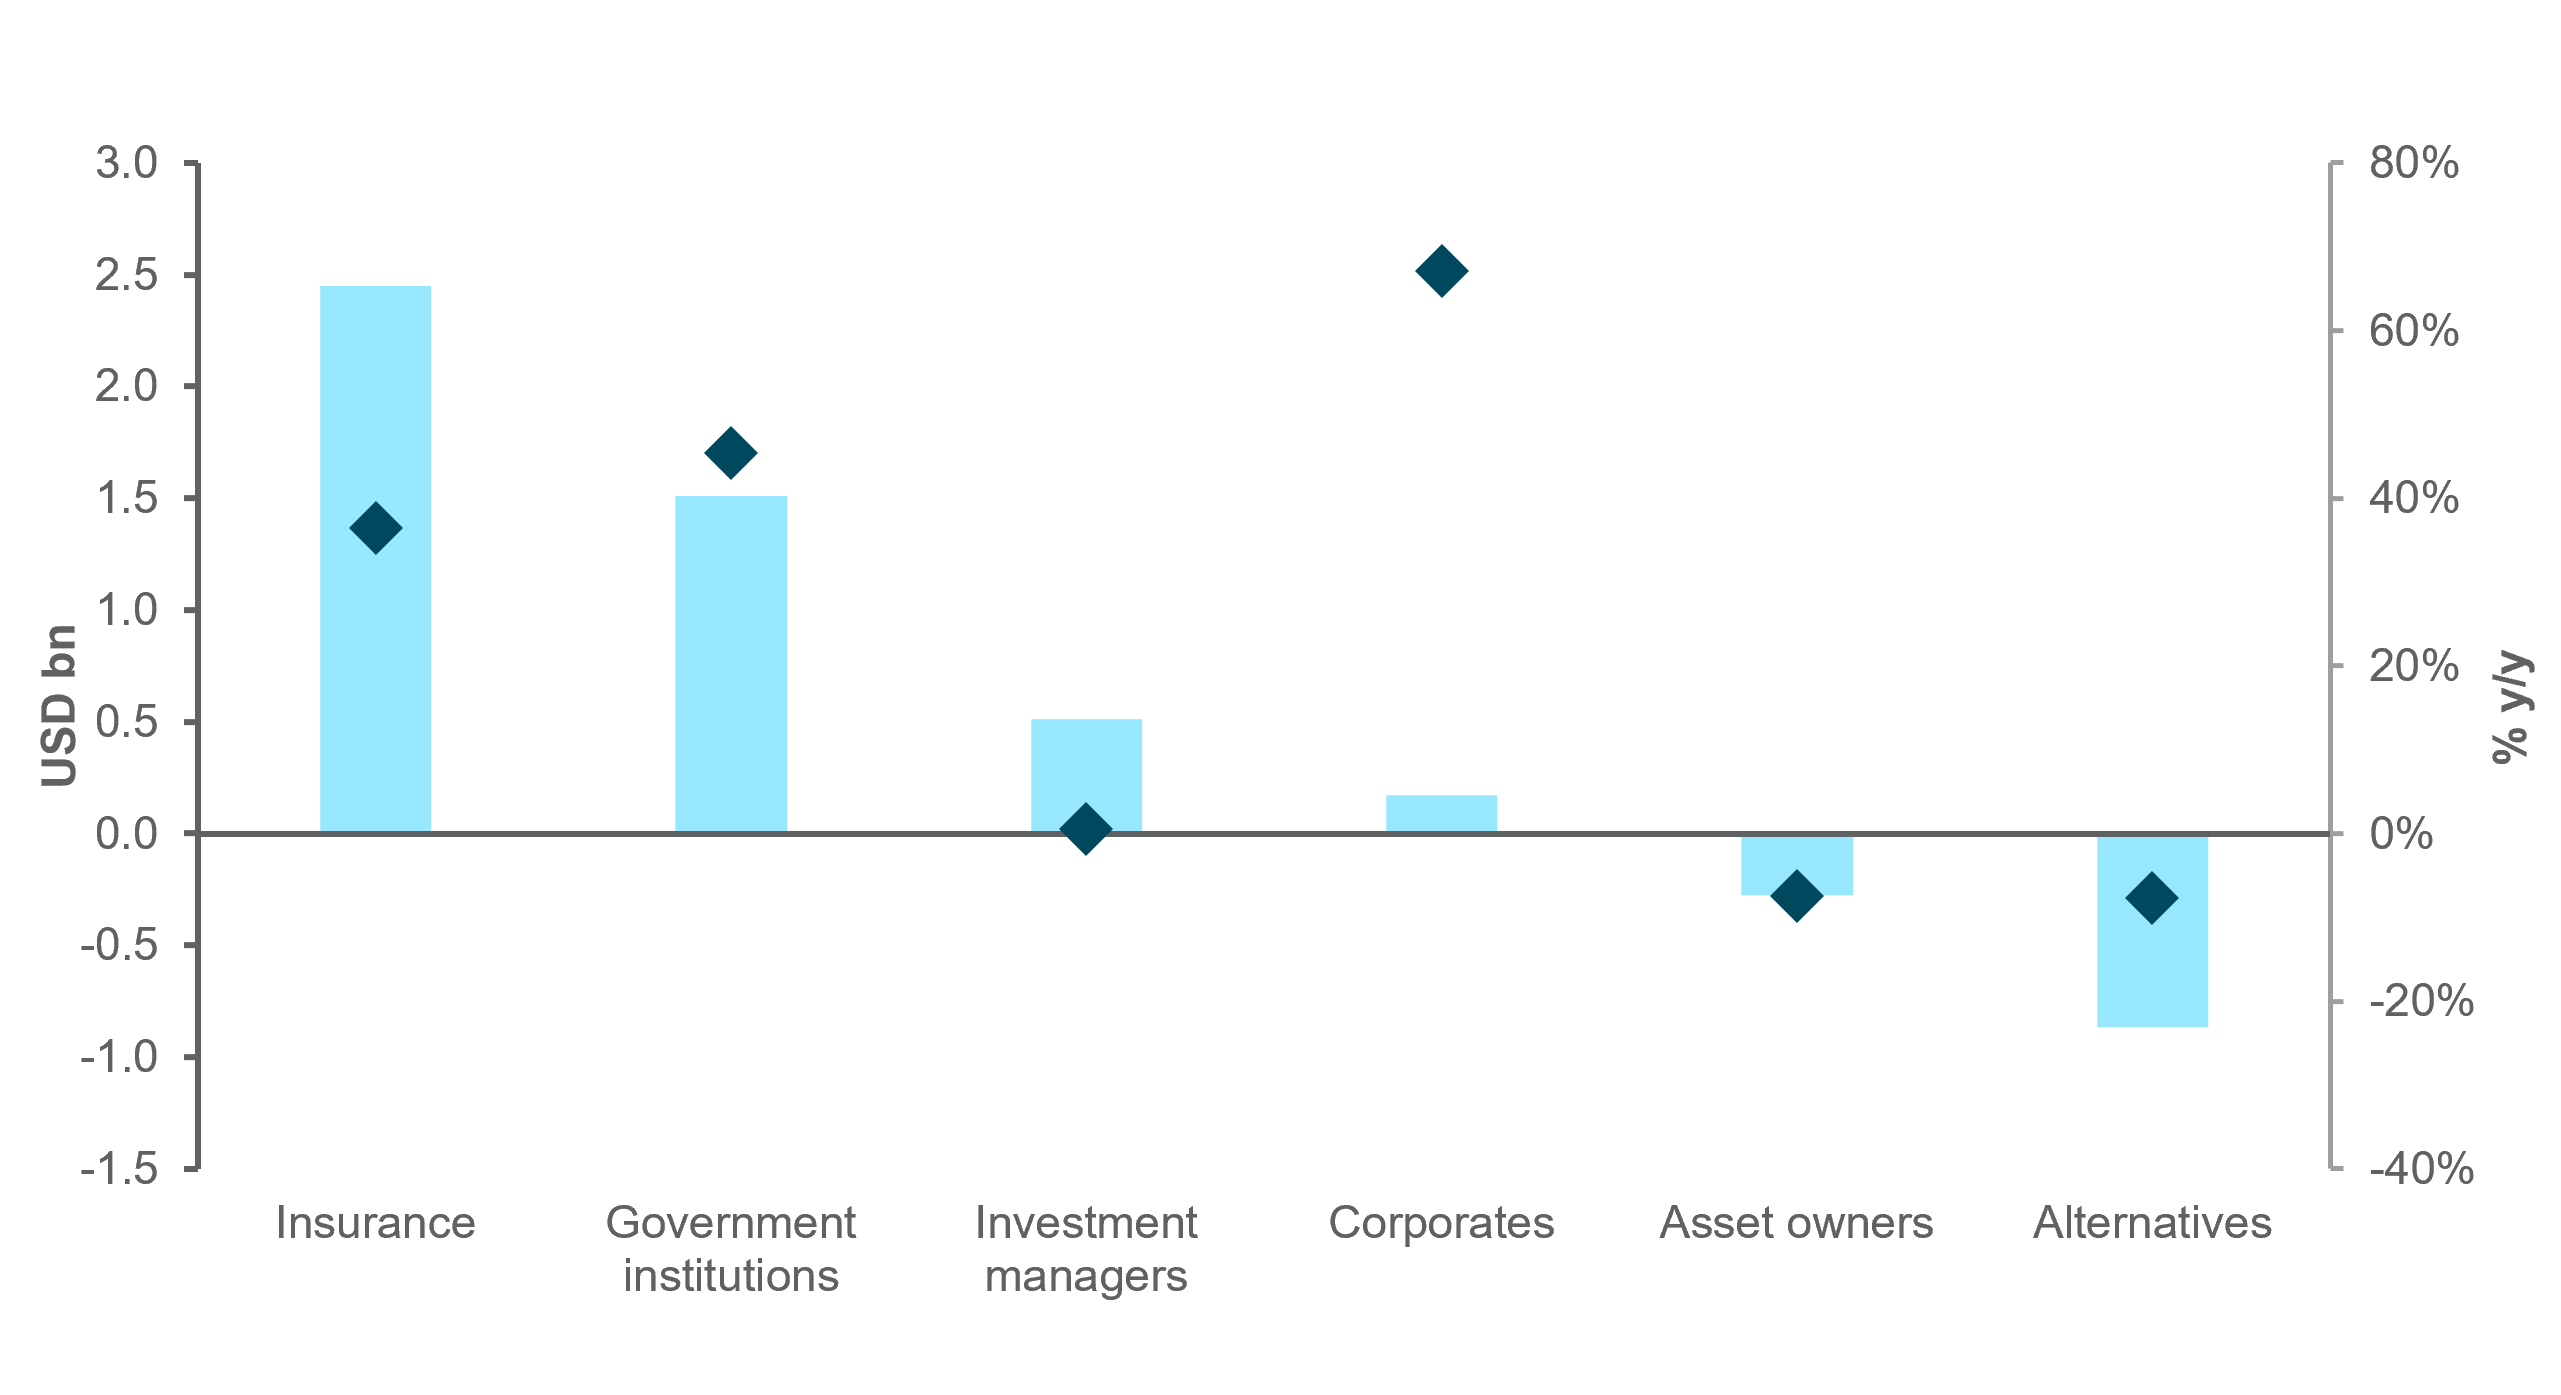
EXHIBIT #3: YEAR-TO-DATE JGBS PURCHASES BY FOREIGN-DOMICILED INVESTORS AND PERCENTAGE CHANGE
Source: BNY
Our take
The MOF shouldn’t fear an orderly rise in yields as foreign demand for JGBs gains ground. Based on our data, between January 1 and July 22, foreign-domiciled JGB holdings rose by $727mn to $87.1bn, while domestic holdings fell by $3.3bn to $95.3bn. The data measure changes in holdings rather than transaction-level flows, yet the direction is clear: foreign investors broadly absorbed the domestic reduction and added modestly on net.
The composition of foreign demand is more important than the aggregate change. Insurance companies were the largest buyers, increasing holdings by $2.45bn, or 36%, to $9.18bn. Government institutions added $1.51bn, lifting exposure by 45%, while central banks and monetary authorities increased holdings from $281mn to $975mn, a 246% rise from a low base. Together, insurers and government institutions added almost $4bn, indicating that the marginal demand is coming from structural, long-duration and official-sector buyers.
This contrasts with more tactical investors. Banks, brokers and dealers remain the largest foreign holder at $38.4bn, but reduced exposure by $1.57bn, the largest absolute decline. Alternatives cut $864mn, including a $541mn reduction by other alternative funds, while hedge funds trimmed holdings by $367mn. Mutual funds, pension funds and portfolio managers were broadly flat to slightly lower. The foreign bid isn’t broad-based: real-money and official investors are accumulating, while trading-oriented and leveraged accounts are reducing exposure.
Forward look
If yields continue to rise in an orderly way, insurers, government institutions and central banks should remain the main buyers. Insurers have the clearest incentive because higher long-end yields improve asset-liability matching, while official institutions can use JGBs for reserve diversification. Japanese investors may also reduce foreign bond purchases as domestic yields become more competitive. If there’s a clear strengthening trajectory for JPY in the meantime, hedge ratios are likely to remain lower than standard, adding to marginal interest.
The risk is that higher yields begin to reflect fiscal credibility concerns rather than better compensation for duration. In that scenario, banks, fast-money and alternatives may continue cutting exposure, leaving structural buyers to absorb supply. The durability of the JGB bid therefore depends less on the absolute level of yields than on whether the rise remains orderly. JPY’s volatility profile may also mandate higher hedge ratios for risk management purposes. Both factors create an imperative to manage FX and bond flows, which can improve volatility-adjusted returns on a structural basis.