Eurozone assets await ECB help
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 5 minutes
The ECB has room to pivot back toward growth. Weak consumer-sector positioning, tighter credit conditions and widening Eurozone cash outflows all suggest that the June tightening is already weighing on the economy. However, the euro itself offers less attractive risk-reward: currency exposure has risen sharply because hedge ratios are unusually low, even though underlying equity and bond ownership remains subdued. The stronger opportunity lies in Eurozone assets rather than chasing EUR outright.
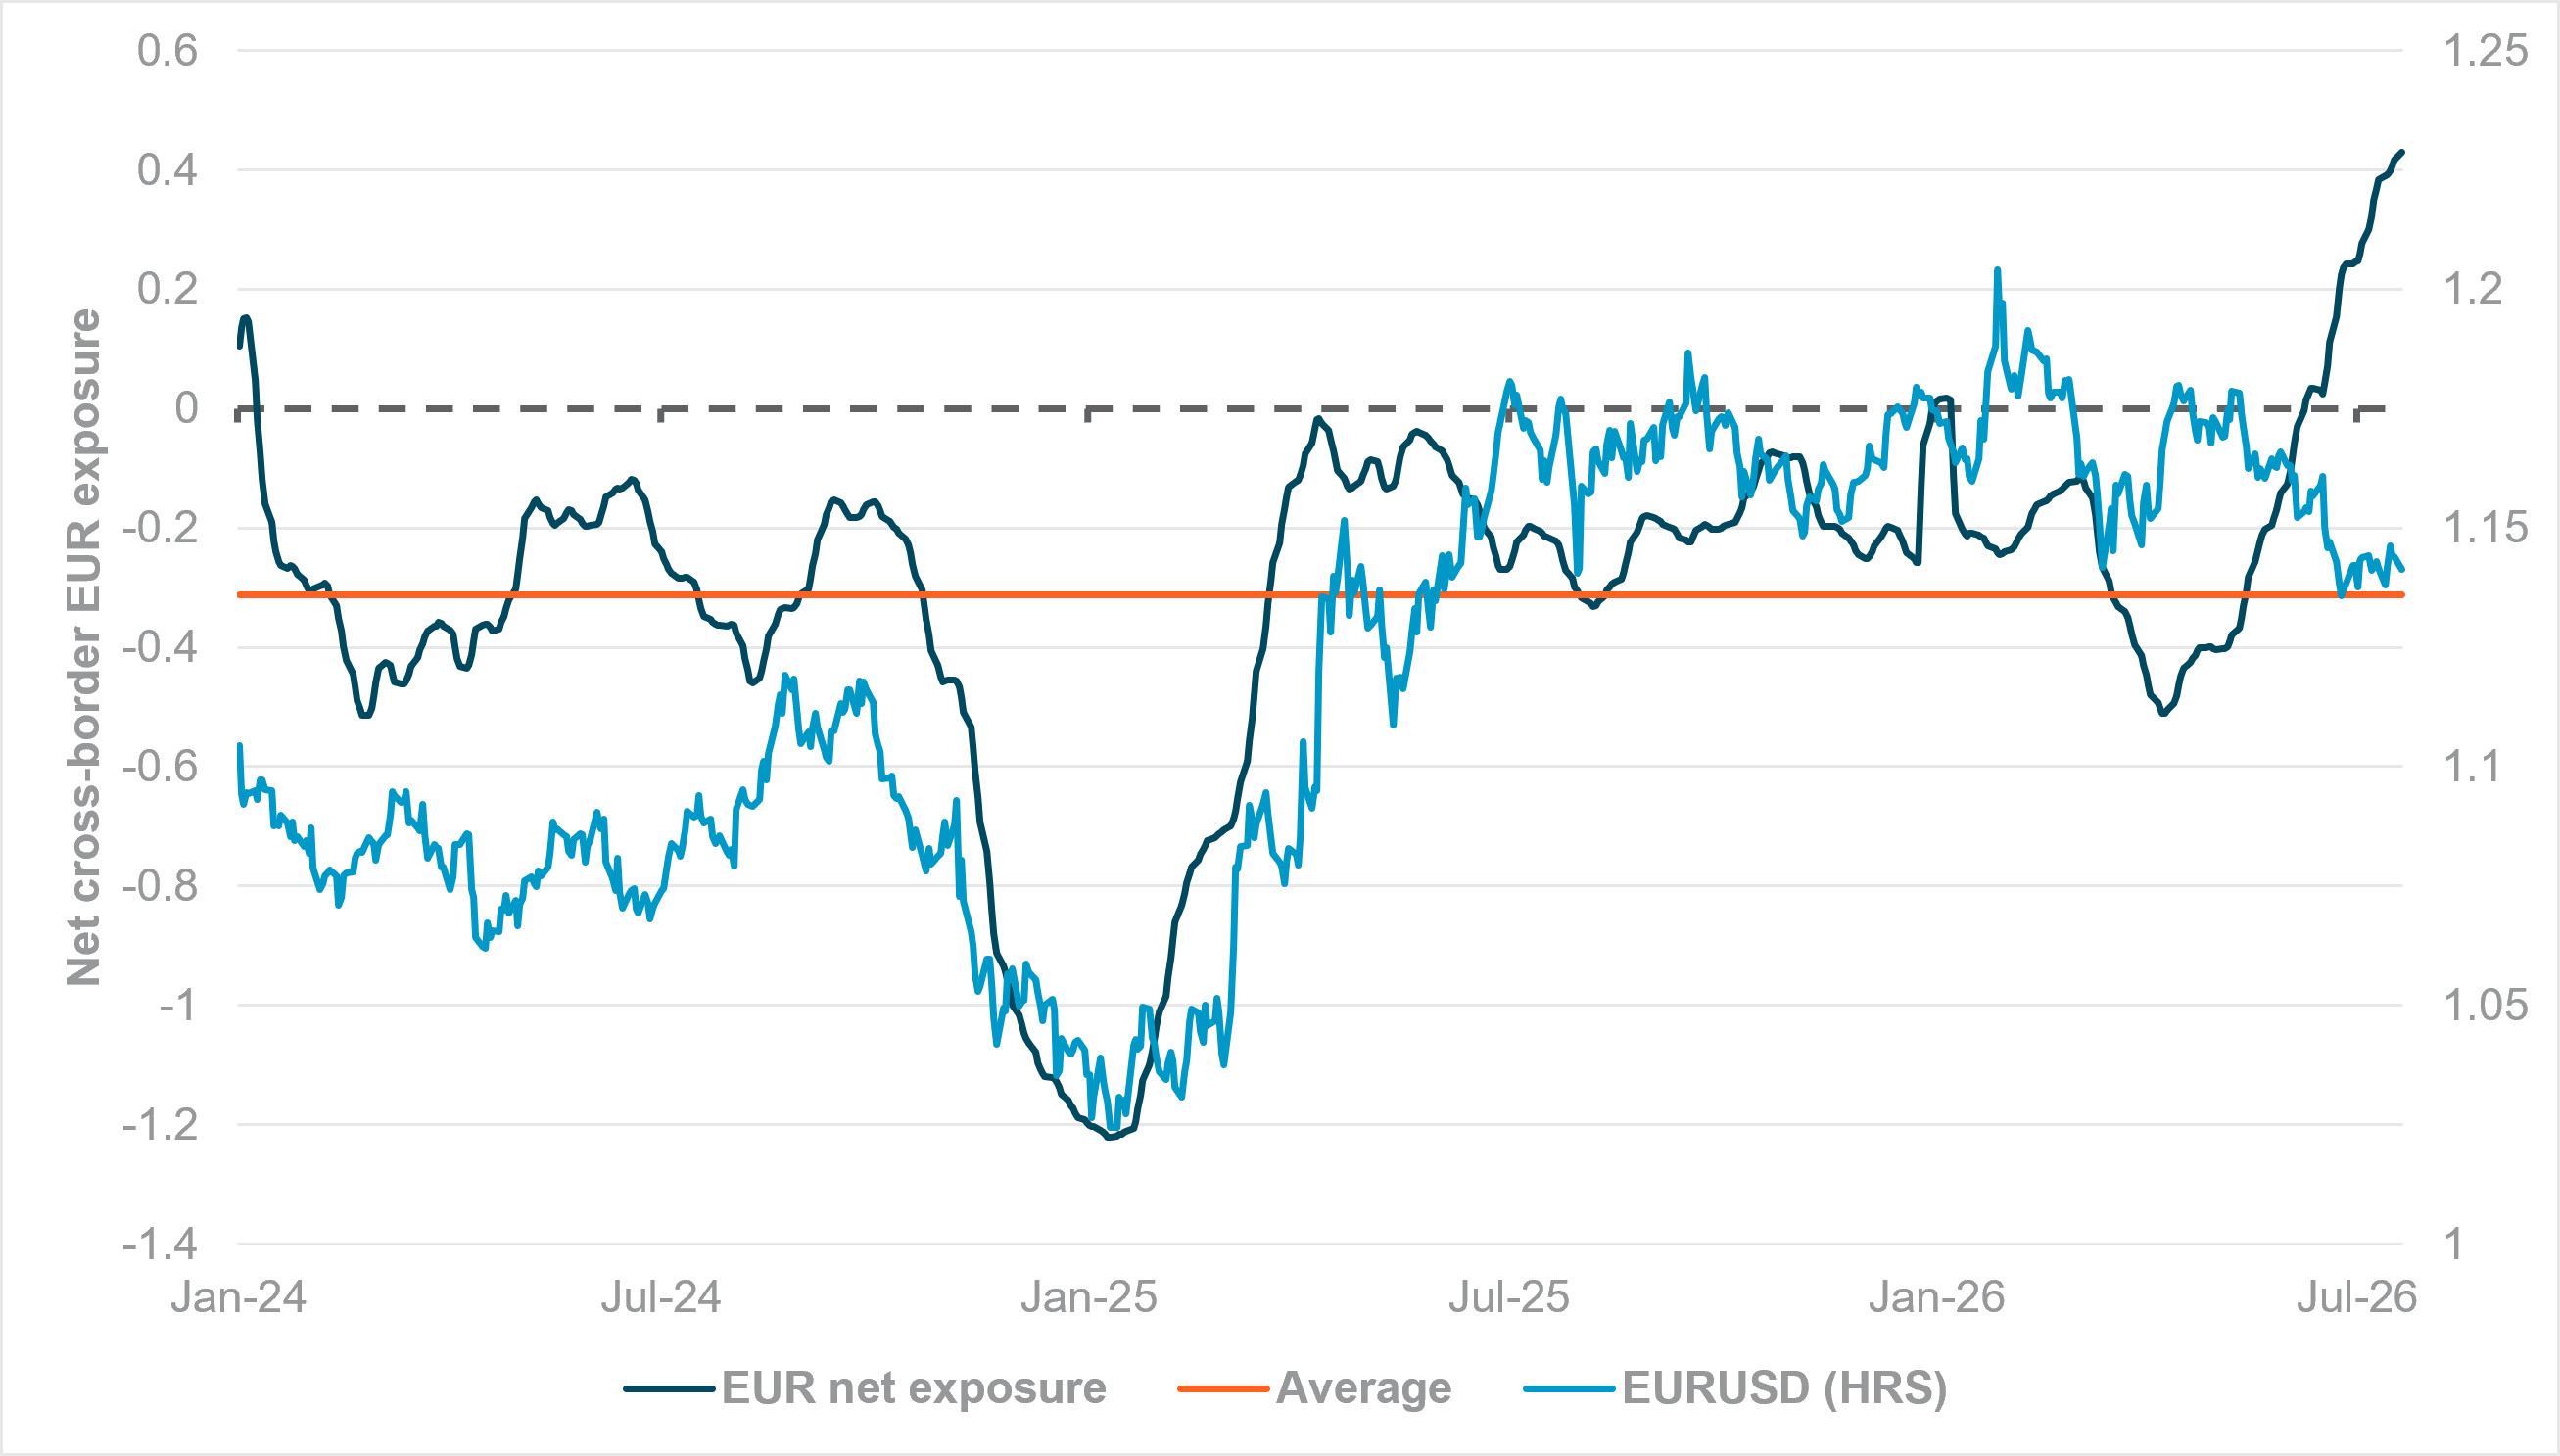
EXHIBIT #1: CROSS-BORDER EURO EXPOSURES, BASED ON 60:40 SOVEREIGN BOND/EQUITY PORTFOLIO
Source: BNY – calculated as net of cross-border euro holdings against a benchmark portfolio
Our take
The EUR is holding its ground heading into the ECB decision. There are already tentative signs of recovery, and we maintain the view that a pro-growth message from the ECB is far more beneficial to the Eurozone economy. Governing Council rhetoric is clearly shifting in that direction, with some major exceptions, and guidance in that direction would encourage further rotation back into the Eurozone.
We remain cautious on chasing EUR outright, however. Our analysis indicates that current net EUR exposures are at the highest levels since 2024 and there has been decoupling in currency performance relative to ownership. By netting off the cross-border EUR holdings position (normally net short to reflect hedges) against changes in a standard 60:40 sovereign bond/equity portfolio, we can track the change in EUR exposures relative to portfolio performance. The long-term average is around -0.3, indicating preference to be over-hedged relative to portfolios, which is standard for low-yielders.
Recently net exposures have surged into positive (Exhibit 1), which is a rarity. This has been led by significant unwinding of EUR holdings relative to changes in portfolio holdings: current EUR hedges are 0.6x the rolling 12-month average, which is the lowest hedge level in our tracking period from 2024 onwards. Overall portfolio holdings are not high – equities are less than 2% above the rolling 12-month average and sovereign bonds 2% below (27th and 25th percentile respectively). It’s that hedging levels are too low, and significant catch-up is needed if asset holdings improve.
Forward look
The ECB is unlikely to favor a significantly weaker EUR while residual inflation remains high. Any step back from tightening will be framed as just that and targeted at credit conditions. The German government’s complaints against CNH suggests concern over valuations against a Chinese shock. iFlow indicates that current EUR holdings strength is largely due to buying on the crosses (ex-EURGBP) due to the ECB’s recent hike, so a pullback will help avoid EUR exposures becoming excessive. Even with a more cautious growth outlook, the EUR has not fallen materially, which supports the view that holdings remain firm. Eurozone assets stand to benefit far more from an ECB pullback, and we expect hedge ratios to naturally increase.
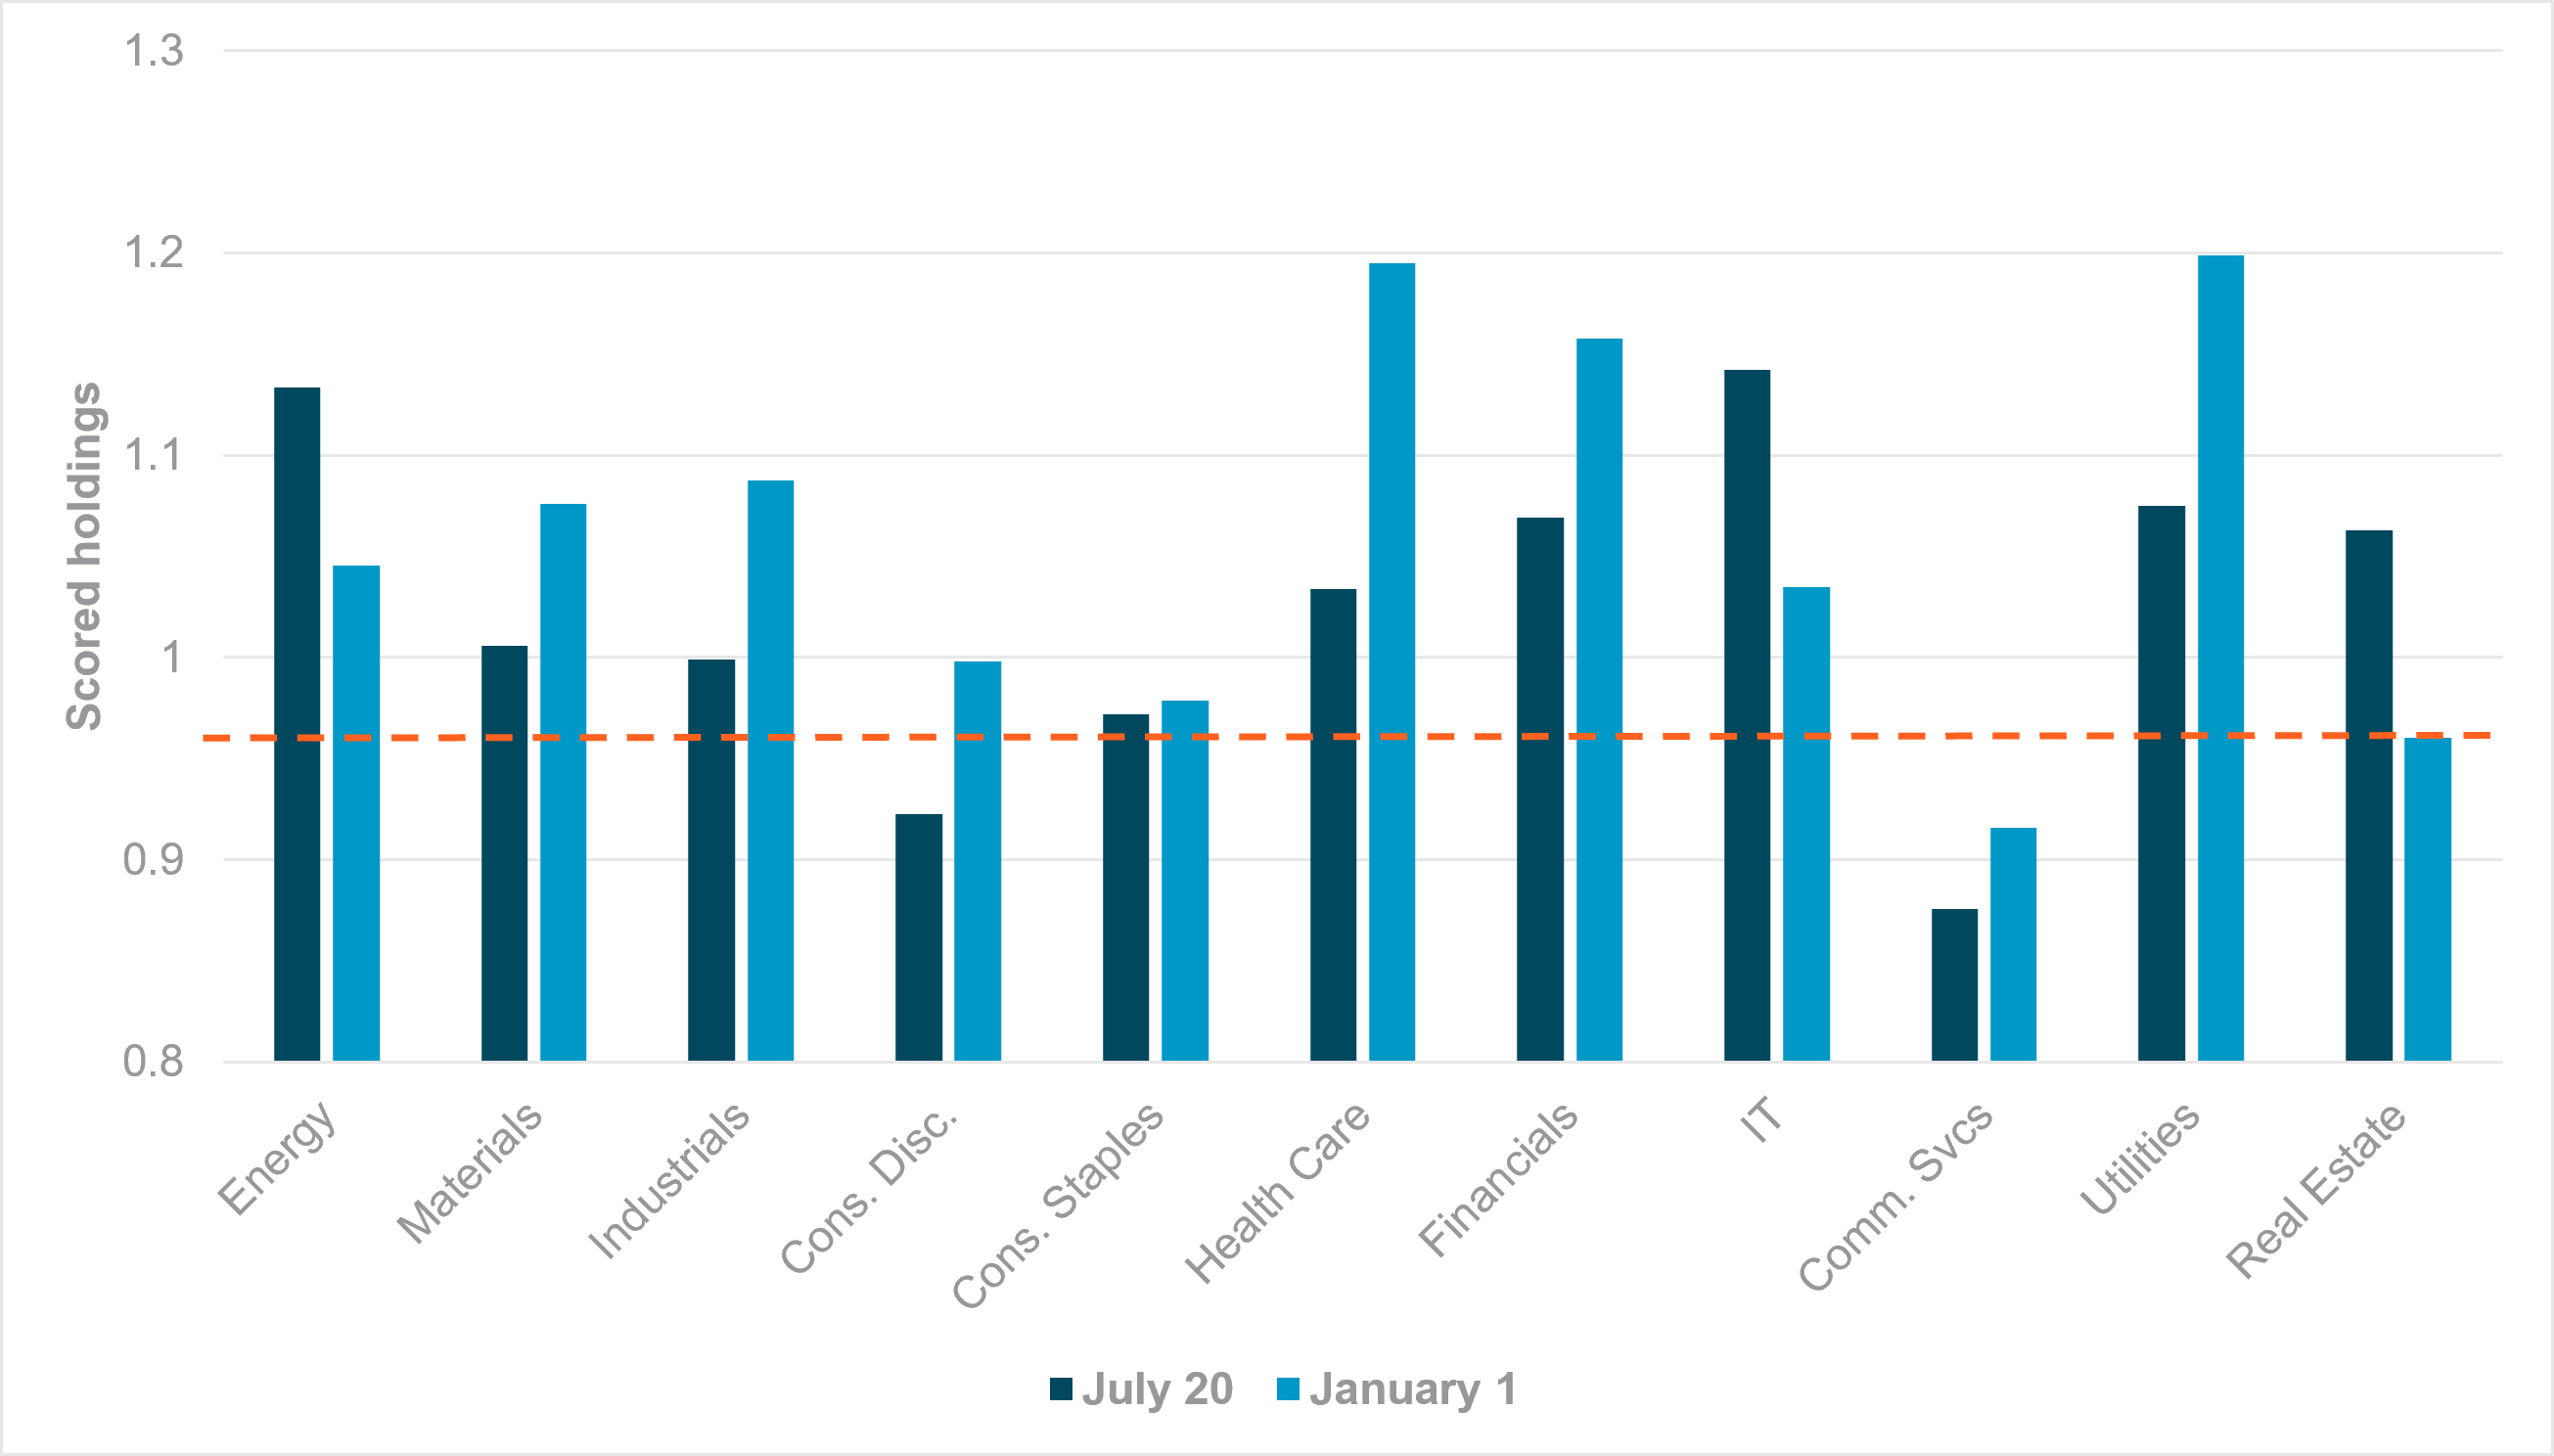
EXHIBIT #2: HOLDINGS CHANGE BY GICS LEVEL 1 (SECTOR), DEVELOPED EUROPE
Source: BNY
Our take
Equity holdings show institutional investors remain deeply cautious about the European consumer. Holdings in DM EMEA Consumer Discretionary stand at 0.92, placing the sector in the fourth monthly percentile and close to its lowest level of the past year. Only Communication Services has a weaker holdings level. This is more than a temporary bout of selling: investors appear to have settled into a firmly negative view on household demand and discretionary spending. Europe is also the clear weak spot across developed markets. Consumer Discretionary holdings stand at 0.97 globally and 1.02 in Asia-Pacific, compared with just 0.92 in DM EMEA. Europe is therefore the main drag on the broader sector picture.
Flows offer little sign of a turnaround. The current reading of -0.39 suggests selling is no longer intensifying, but investors are not returning to the sector either. Participation has widened slightly over the past five days, although from a very low base and not by enough to indicate a convincing recovery.
Forward look
The flow picture signals broad caution toward the European consumer up ahead. Consumer Discretionary is already a deeply established underweight, with no recovery in demand for the sector. Consumer Staples are now also facing pronounced outflows rather than benefiting from a conventional defensive rotation. If this selling persists, it would confirm that investors expect weakness to extend beyond discretionary spending and into the wider European consumer complex. European corporates will see greater immediate benefit from a more dovish ECB but confirmation for full recovery will be required from the consumer. Lack of improvement through Q3 – reflected in ongoing holdings weakness – will open the way for ECB easing.
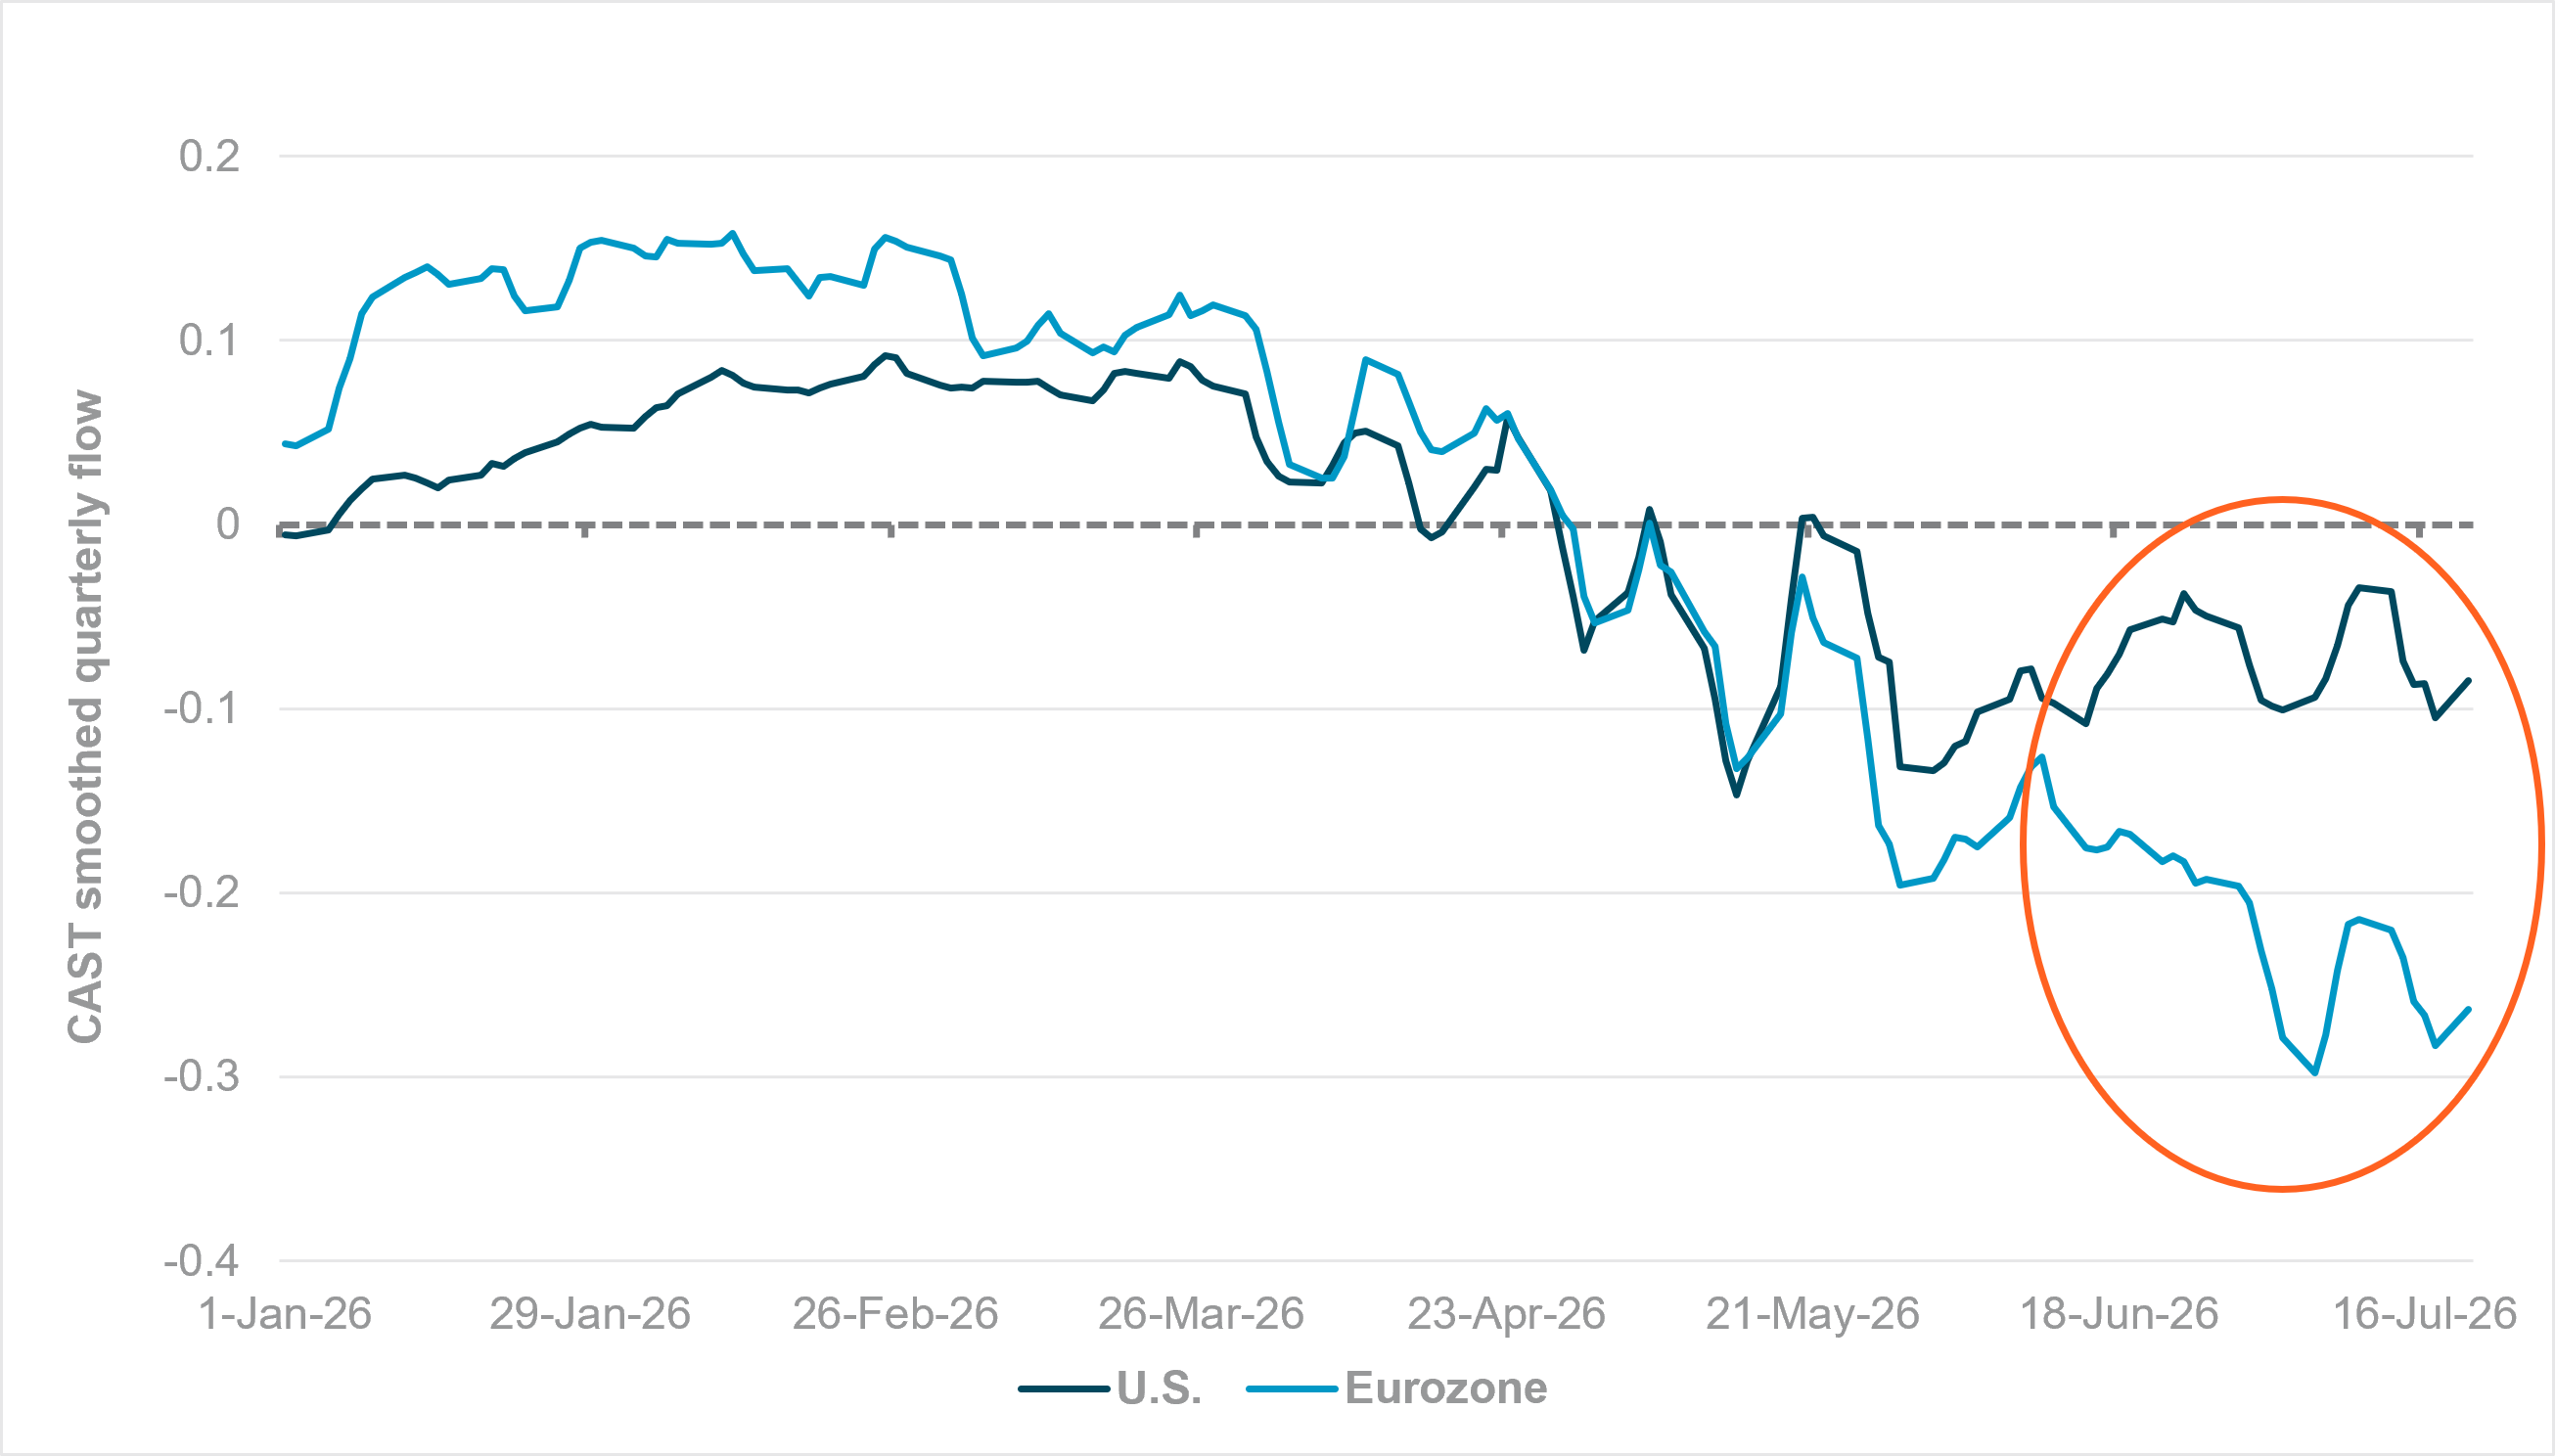
EXHIBIT #3: QUARTERLY SMOOTHED FLOWS, U.S. AND EUROZONE CAST
Source: BNY
Our take
Cash and short-term securities (CAST) outflows tend to pick up in two situations. First, when there is a significant interest in assets, which causes rotation out of cash. Secondly, when interest rate expectations shift more materially. CAST flows in EUR and USD have been well-aligned throughout the year, but we can see a material break in recent weeks. As outflows through April and May support the asset flow thesis, the more recent June data point to a pullback in interest rate pricing.
We find the divergence between the Eurozone and the U.S. particularly striking. On a quarterly smoothed basis, the current divergence is the widest year to date and isn’t showing any sign of abating. The U.S. is facing outflows as well, which is in line with the recent adjustment in policy expectations and supports our view that the Fed won’t hike this year. The Eurozone decline represents ongoing pullback from a hawkish position: Governing Council rhetoric is shifting; even compared to the Fed, there is more tightening to be priced out.
Forward look
We don’t expect further ECB hikes this year. A cut is also possible to compensate for the unnecessary June move. The Eurozone lending survey for Q2 has already indicated moderate tightening in credit standards for firms and households, even before the June move had time to work through the economy.
CAST figures indicate that the hike has not introduced greater inflows into Eurozone cash equivalents; after all, absolute yields in the Eurozone are not high enough to generate any carry interest and liquidity preference moved elsewhere, which also tightens financial conditions. These outflows are driving EUR weakness, but a shift by the ECB toward stimulus can help engineer a turnaround. Buying of EUR CAST in anticipation of better asset allocation into the region is far more important than simple liquidity preference and confirms improved growth and earnings expectations.
Use any ECB-led EUR pullback to add selectively to under-owned Eurozone assets, not to abandon the regional recovery story. A more growth-friendly policy signal should support bonds, equities, and eventual foreign inflows, while encouraging investors to rebuild currency hedges. Focus on duration and high-quality European assets first; broader equity conviction will require evidence that consumer holdings and flows stabilize through Q3.