Our take
For U.K. assets, the Bank of England (BOE) decision on Thursday is not the key event. We expect rates to remain on hold, but there will be votes for a precautionary hike. However, we don’t see much interest pushing for a more prolonged cycle even among the hawkish members, leaving very little chance that the BOE will match the European Central Bank in sustaining a hawkish outlook. We expect Governor Andrew Bailey to reiterate his view that the labor market is loosening sufficiently to avoid strong wage growth, which characterizes second-round effects, while the economy is already responding to a tightening in financial conditions enforced by higher yields across the curve.
After the meeting, attention will swiftly move to Greater Manchester, where its mayor Andy Burnham is expected to win a by-election and immediately seek a leadership challenge upon his return to the House of Commons. Given the market’s base case is for a new prime minister by year-end, and Burnham is the leading candidate to replace Sir Keir Starmer, gilt markets will need to adjust to a change in fiscal policy, most likely in an expansionary direction.
Forward look
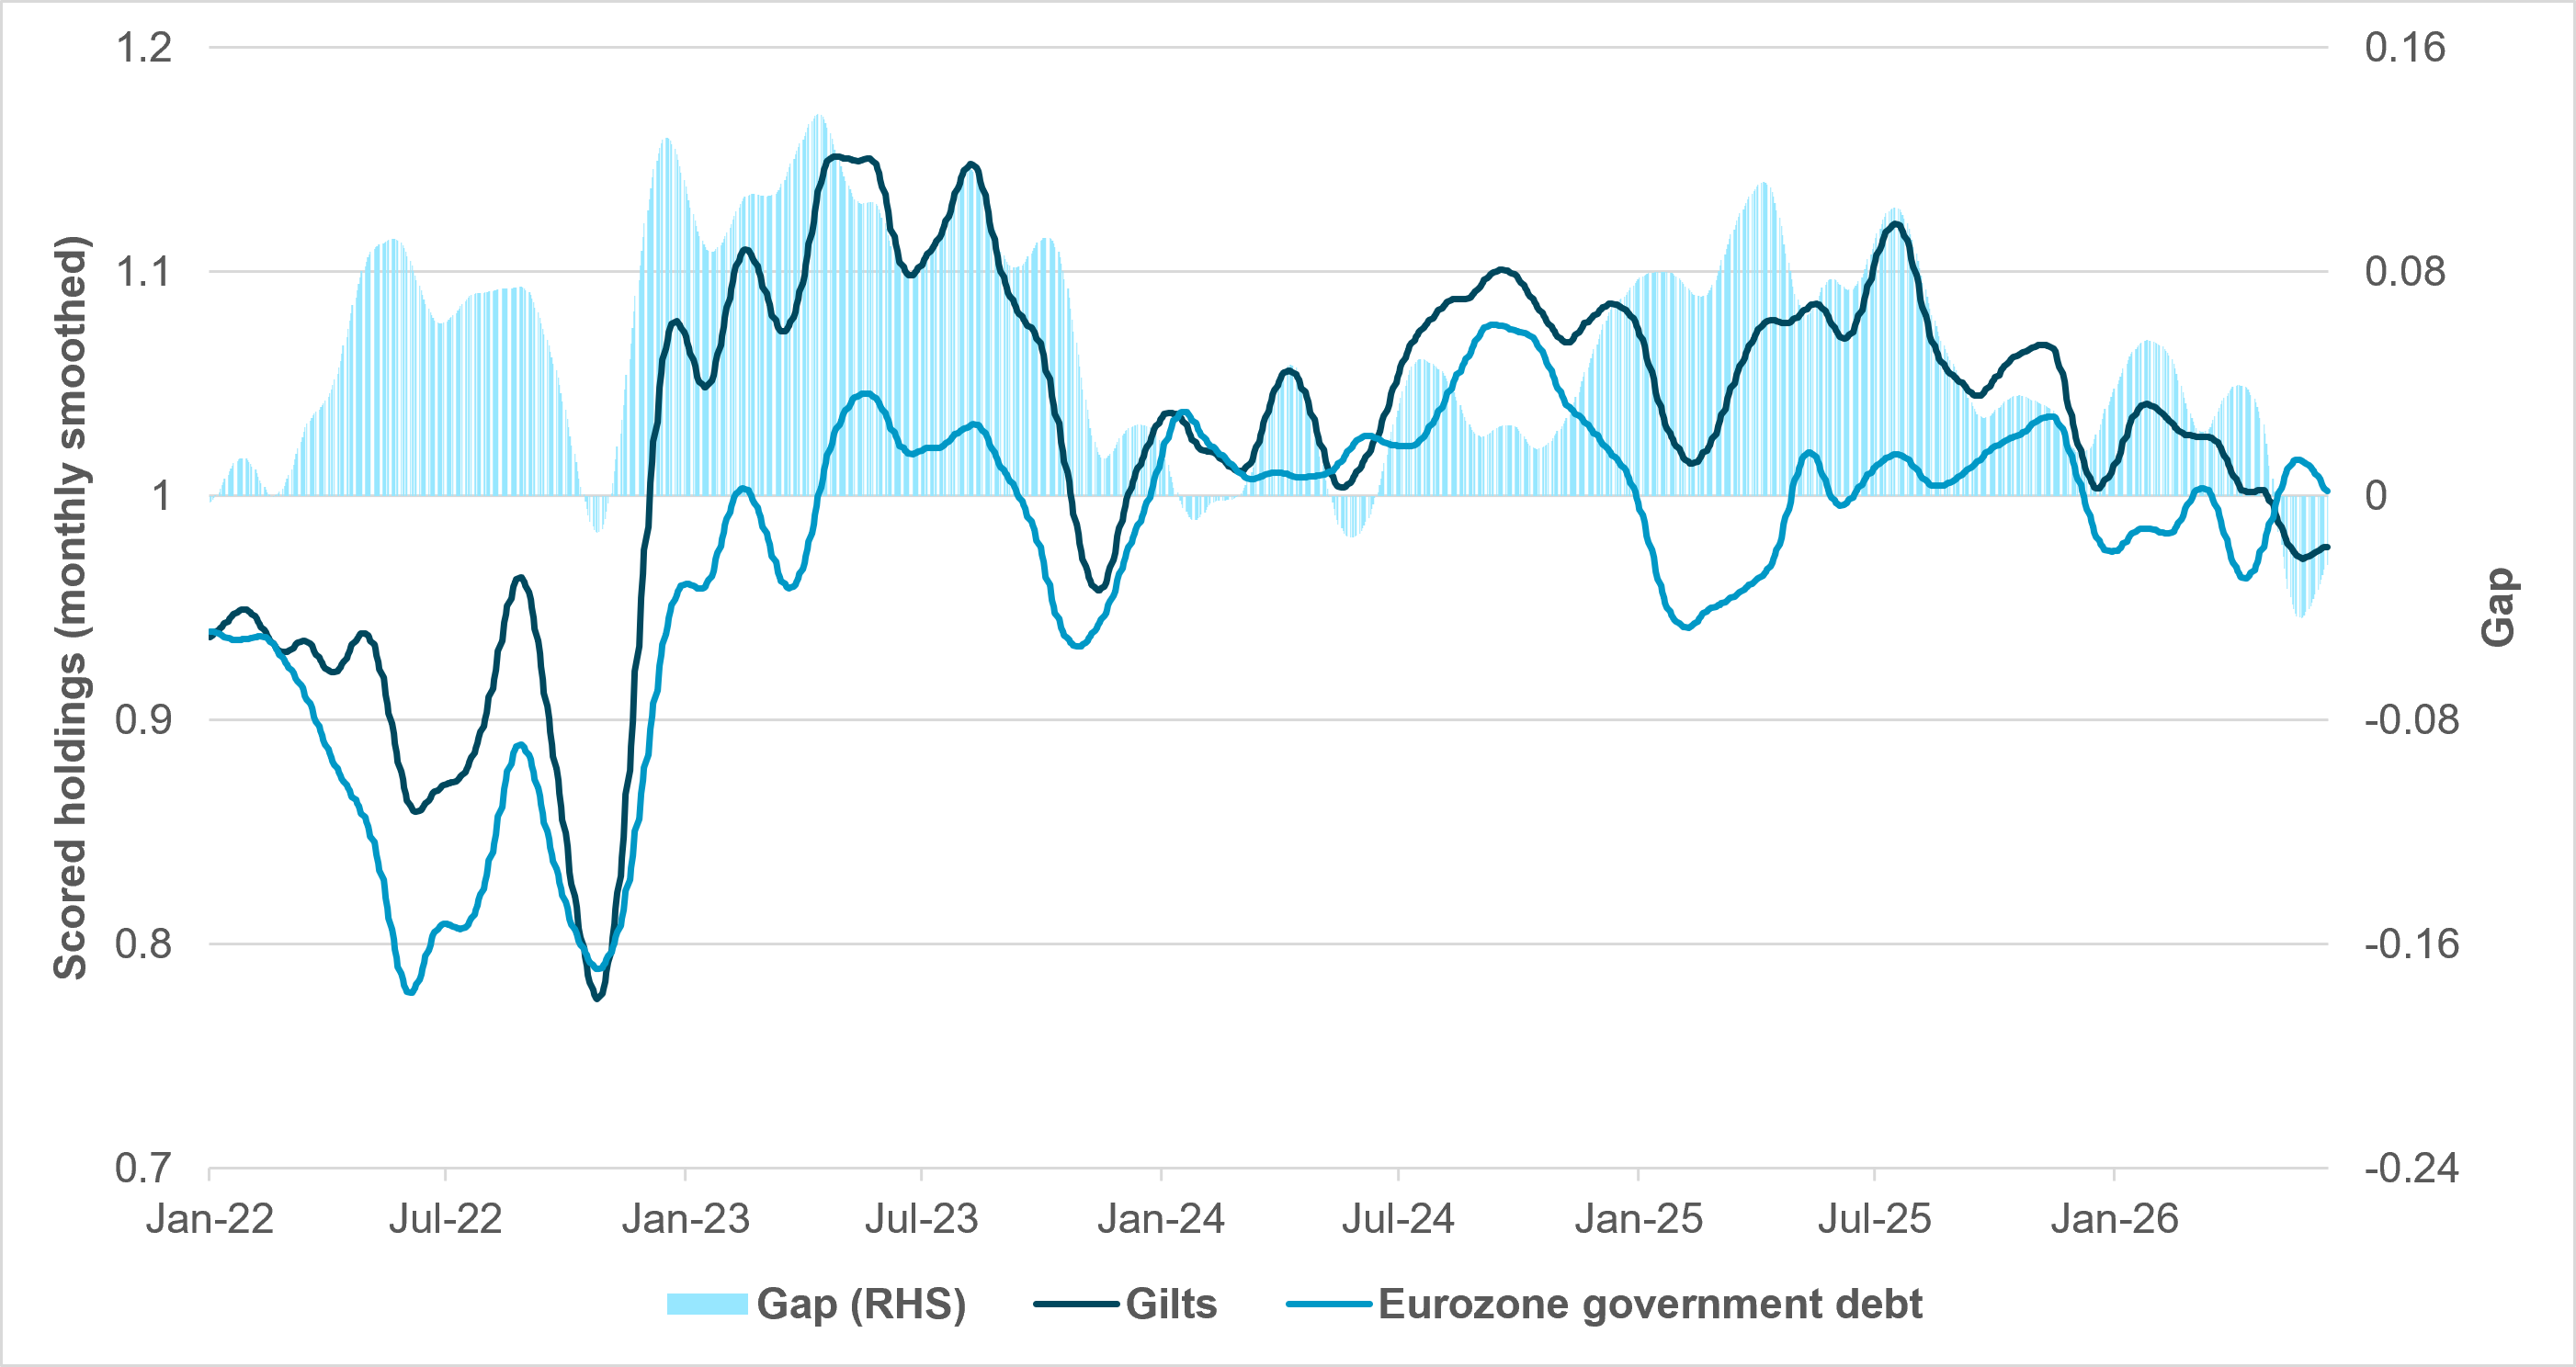
Our data indicate the U.K. gilt market continues to attract strong inflows due to high real rates, but interest remains largely dependent on domestic investors. In contrast, cross-border gilt holdings have recently fallen to the lowest levels since late 2022, and the holdings gap for cross-border investors between Eurozone sovereign debt and gilts also reached its widest level since early 2022.
In absolute terms, both markets’ holdings are well above the “stressed” levels seen in late 2022, and we do not expect a repeat. Admittedly, cross-border interest in both sovereign markets is poor at present as the region is seen as prone to stagflation, but the current gap suggests additional risk premia attached to the U.K. on a relative basis. Previous holdings drops in 2022 and 2023 were followed by significant recoveries – between 10 and 15 percentage points of the rolling 12-month average – in cross-border holdings due to fiscal improvement. Irrespective of political developments, risk-reward is now materially improved for gilt market recovery due to low external holdings. A credible showing in the fall fiscal event is required to realize potential gains.