Dollar and AI themes continue to assert U.S. exceptionalism
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
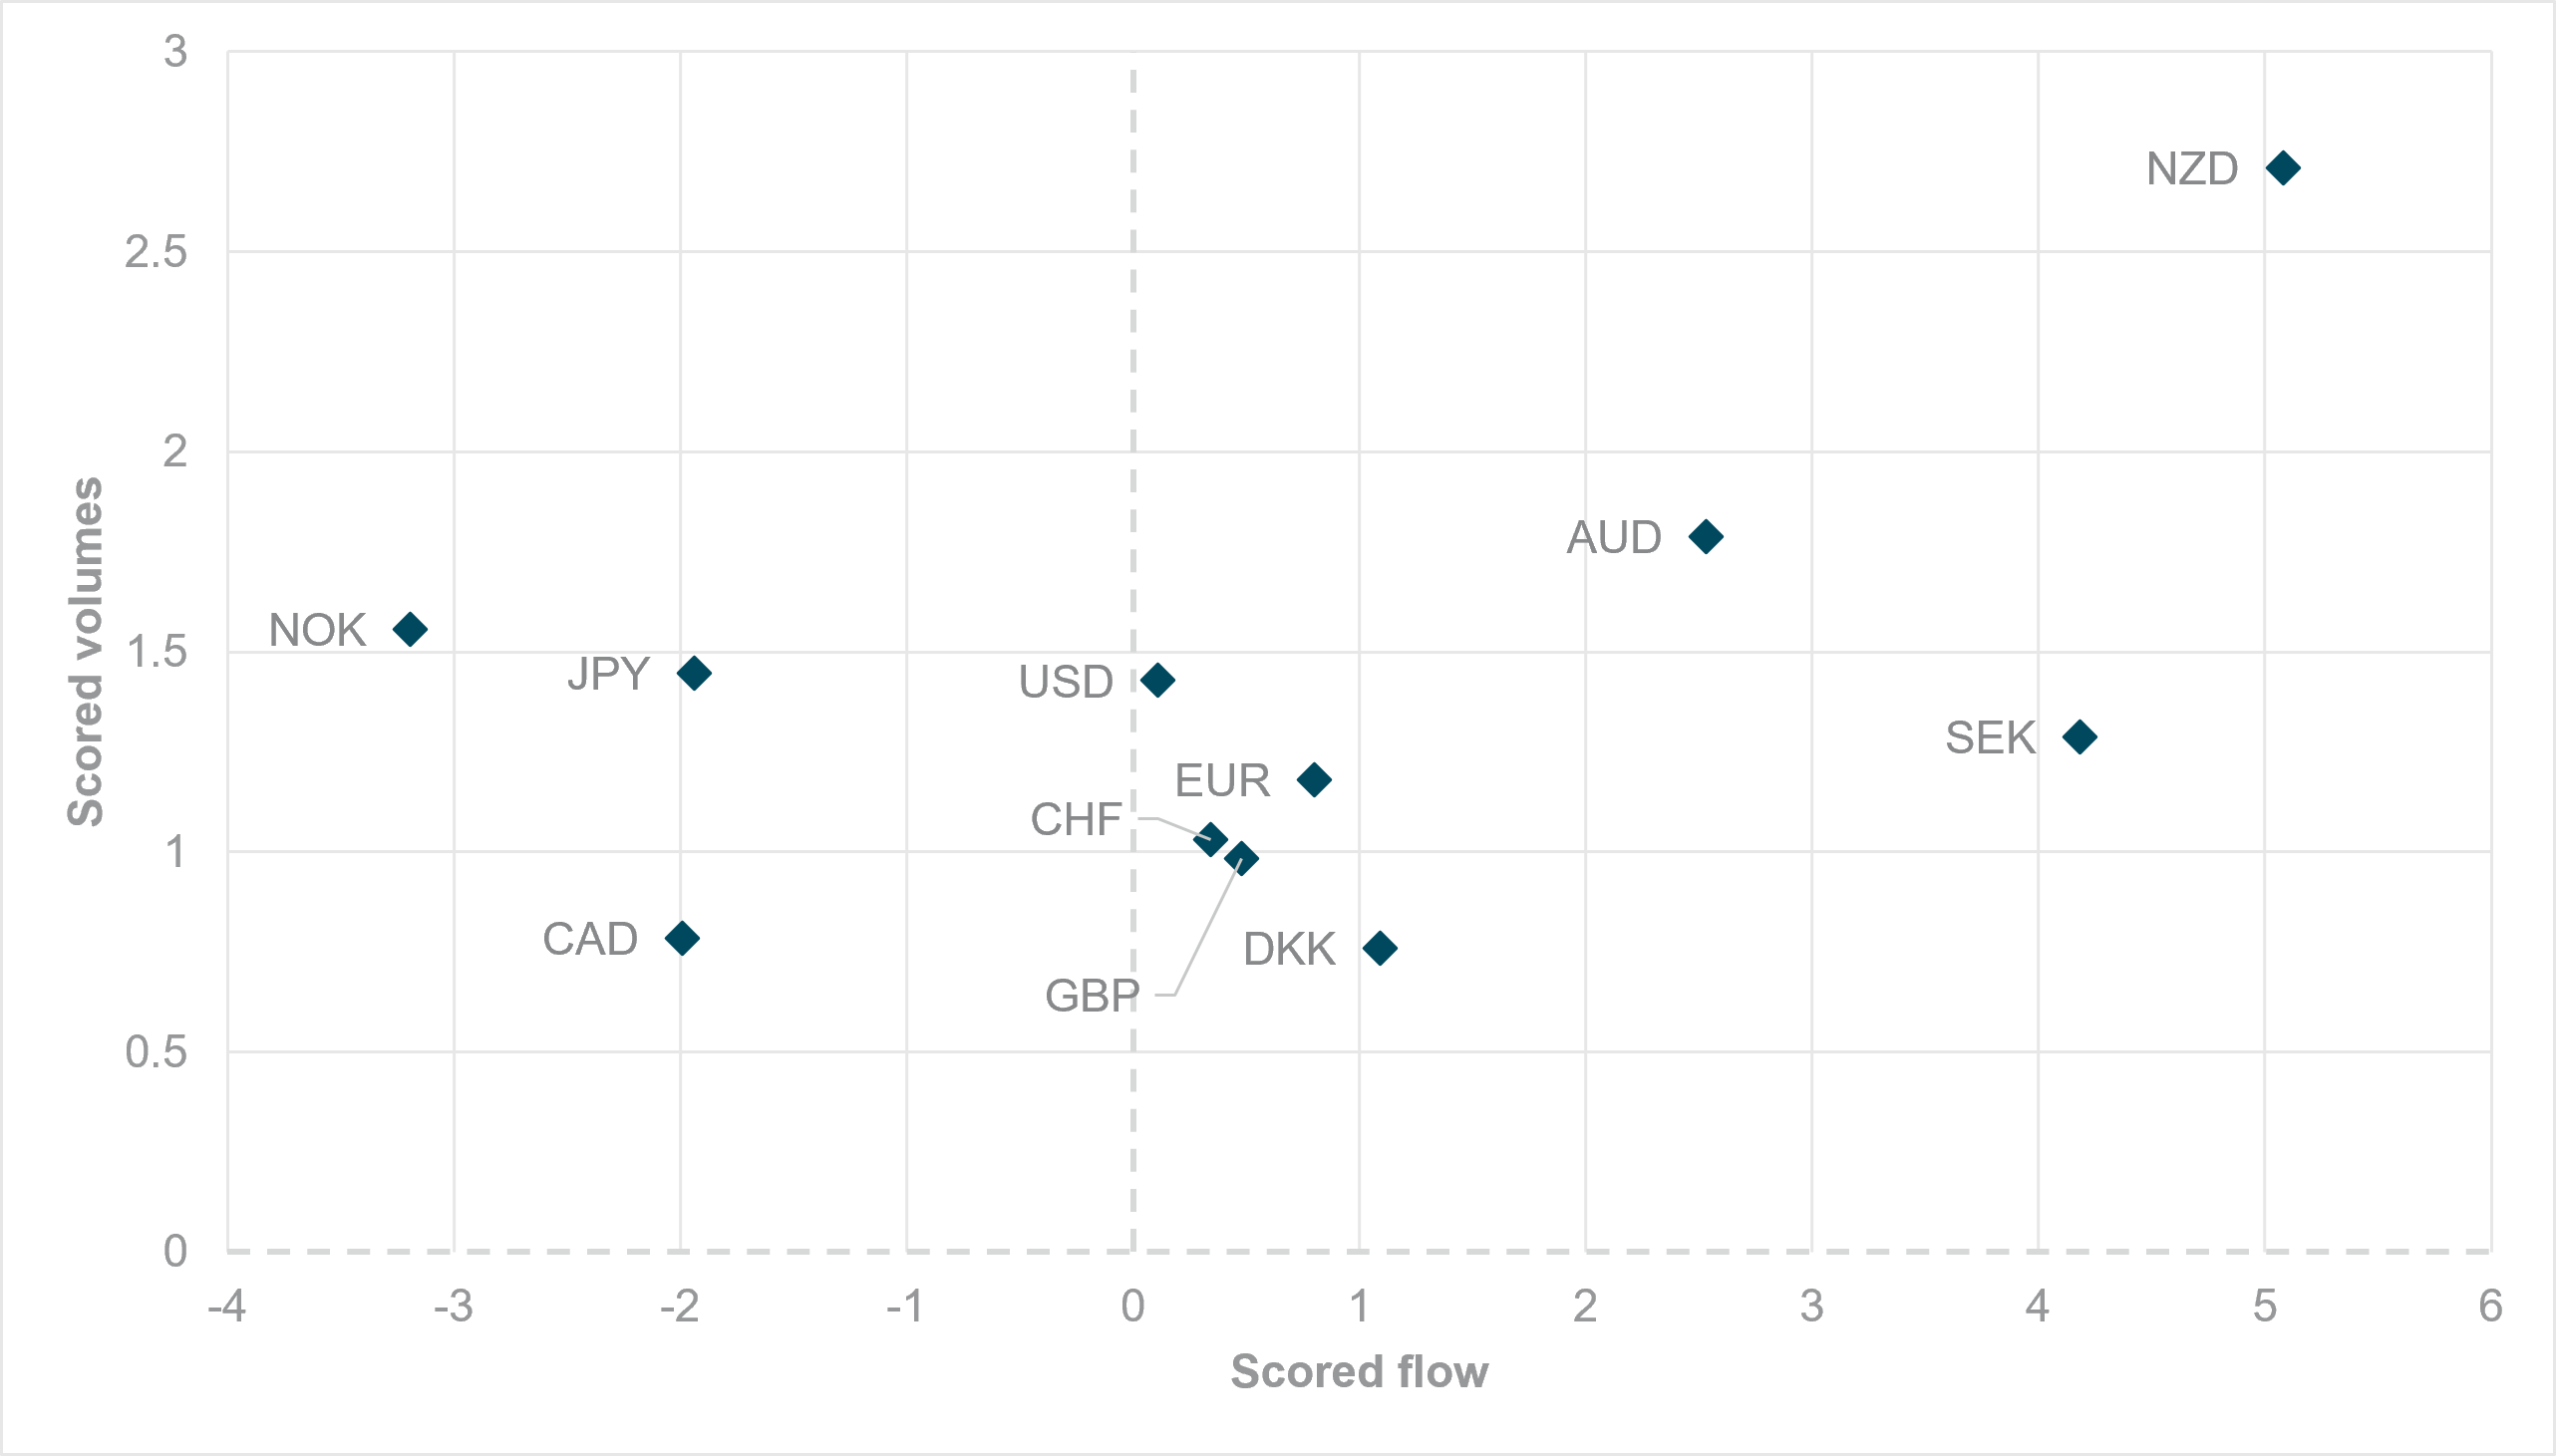
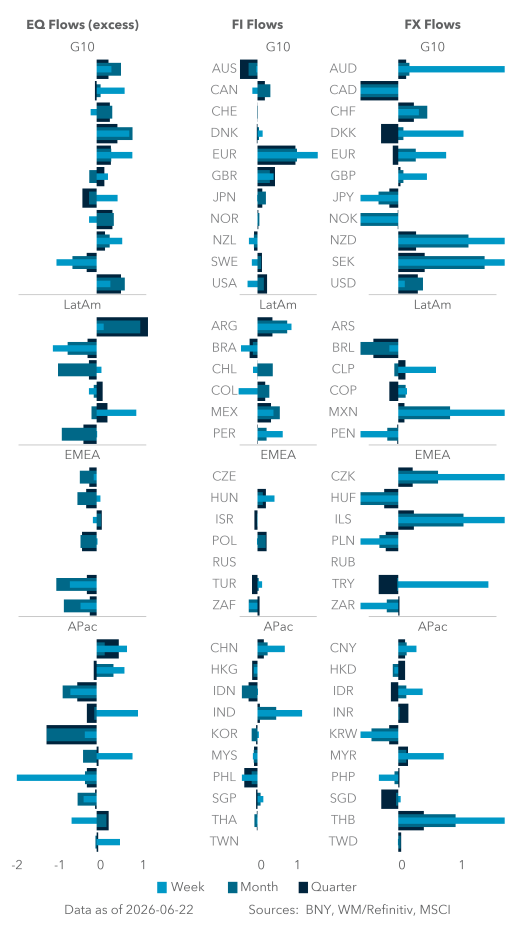
EXHIBIT #1: WEEKLY SCORED VOLUME AND FLOW AS OF JUNE 22, 2025
Source: BNY
Our take
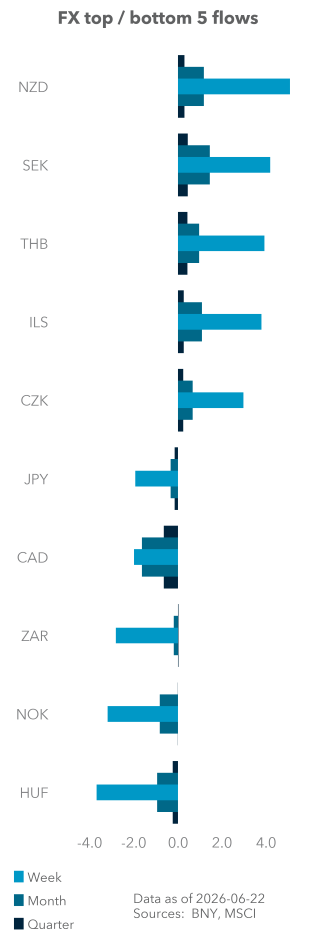
The concentration of FX volumes around International Monetary Market (IMM) roll dates, which now often coincide with Fed decisions, provides a useful indication of investor preferences for maintaining or changing exposures. For example, EUR has moved back into overheld territory on an aggregate basis, as strong net inflows were amplified by a high-volume session. Dollar net flows were broadly neutral, suggesting the currency was used equally as a funding and carry vehicle, which is consistent with current market conditions.
Measured by combined net flow scores and volumes, the largest adjustments occurred in commodity-linked currencies. AUD, NZD and NOK were the most actively traded currencies, while NOK, CAD, NZD and AUD all ranked among the top five G10 currencies by flow magnitude. Combined with recent spot performance, the flows point to clear valuation themes emerging around the outlook for energy and commodities.
Forward look
Outflows from NOK and CAD are unsurprising. Both currencies are highly exposed to oil prices, and the prospect of a durable ceasefire argues for some derating. NOK is particularly vulnerable as the most overheld G10currency, while expectations for further Norges Bank tightening remain modest. CAD also faces headwinds from unfavorable forward rate differentials.
By contrast, NZD and AUD have underperformed since early May. Rising input costs have weakened the case for improved terms of trade, while soft Chinese growth has provided little support. Changes in U.S. rate expectations relative to the antipodeans have historically had a large impact on valuations, but IMM positioning suggests much of that adjustment has already occurred. We are sympathetic to the view that non-energy commodity currencies could outperform in the near term, but current risk-reward favors relative-value positions while USD dominance persists.
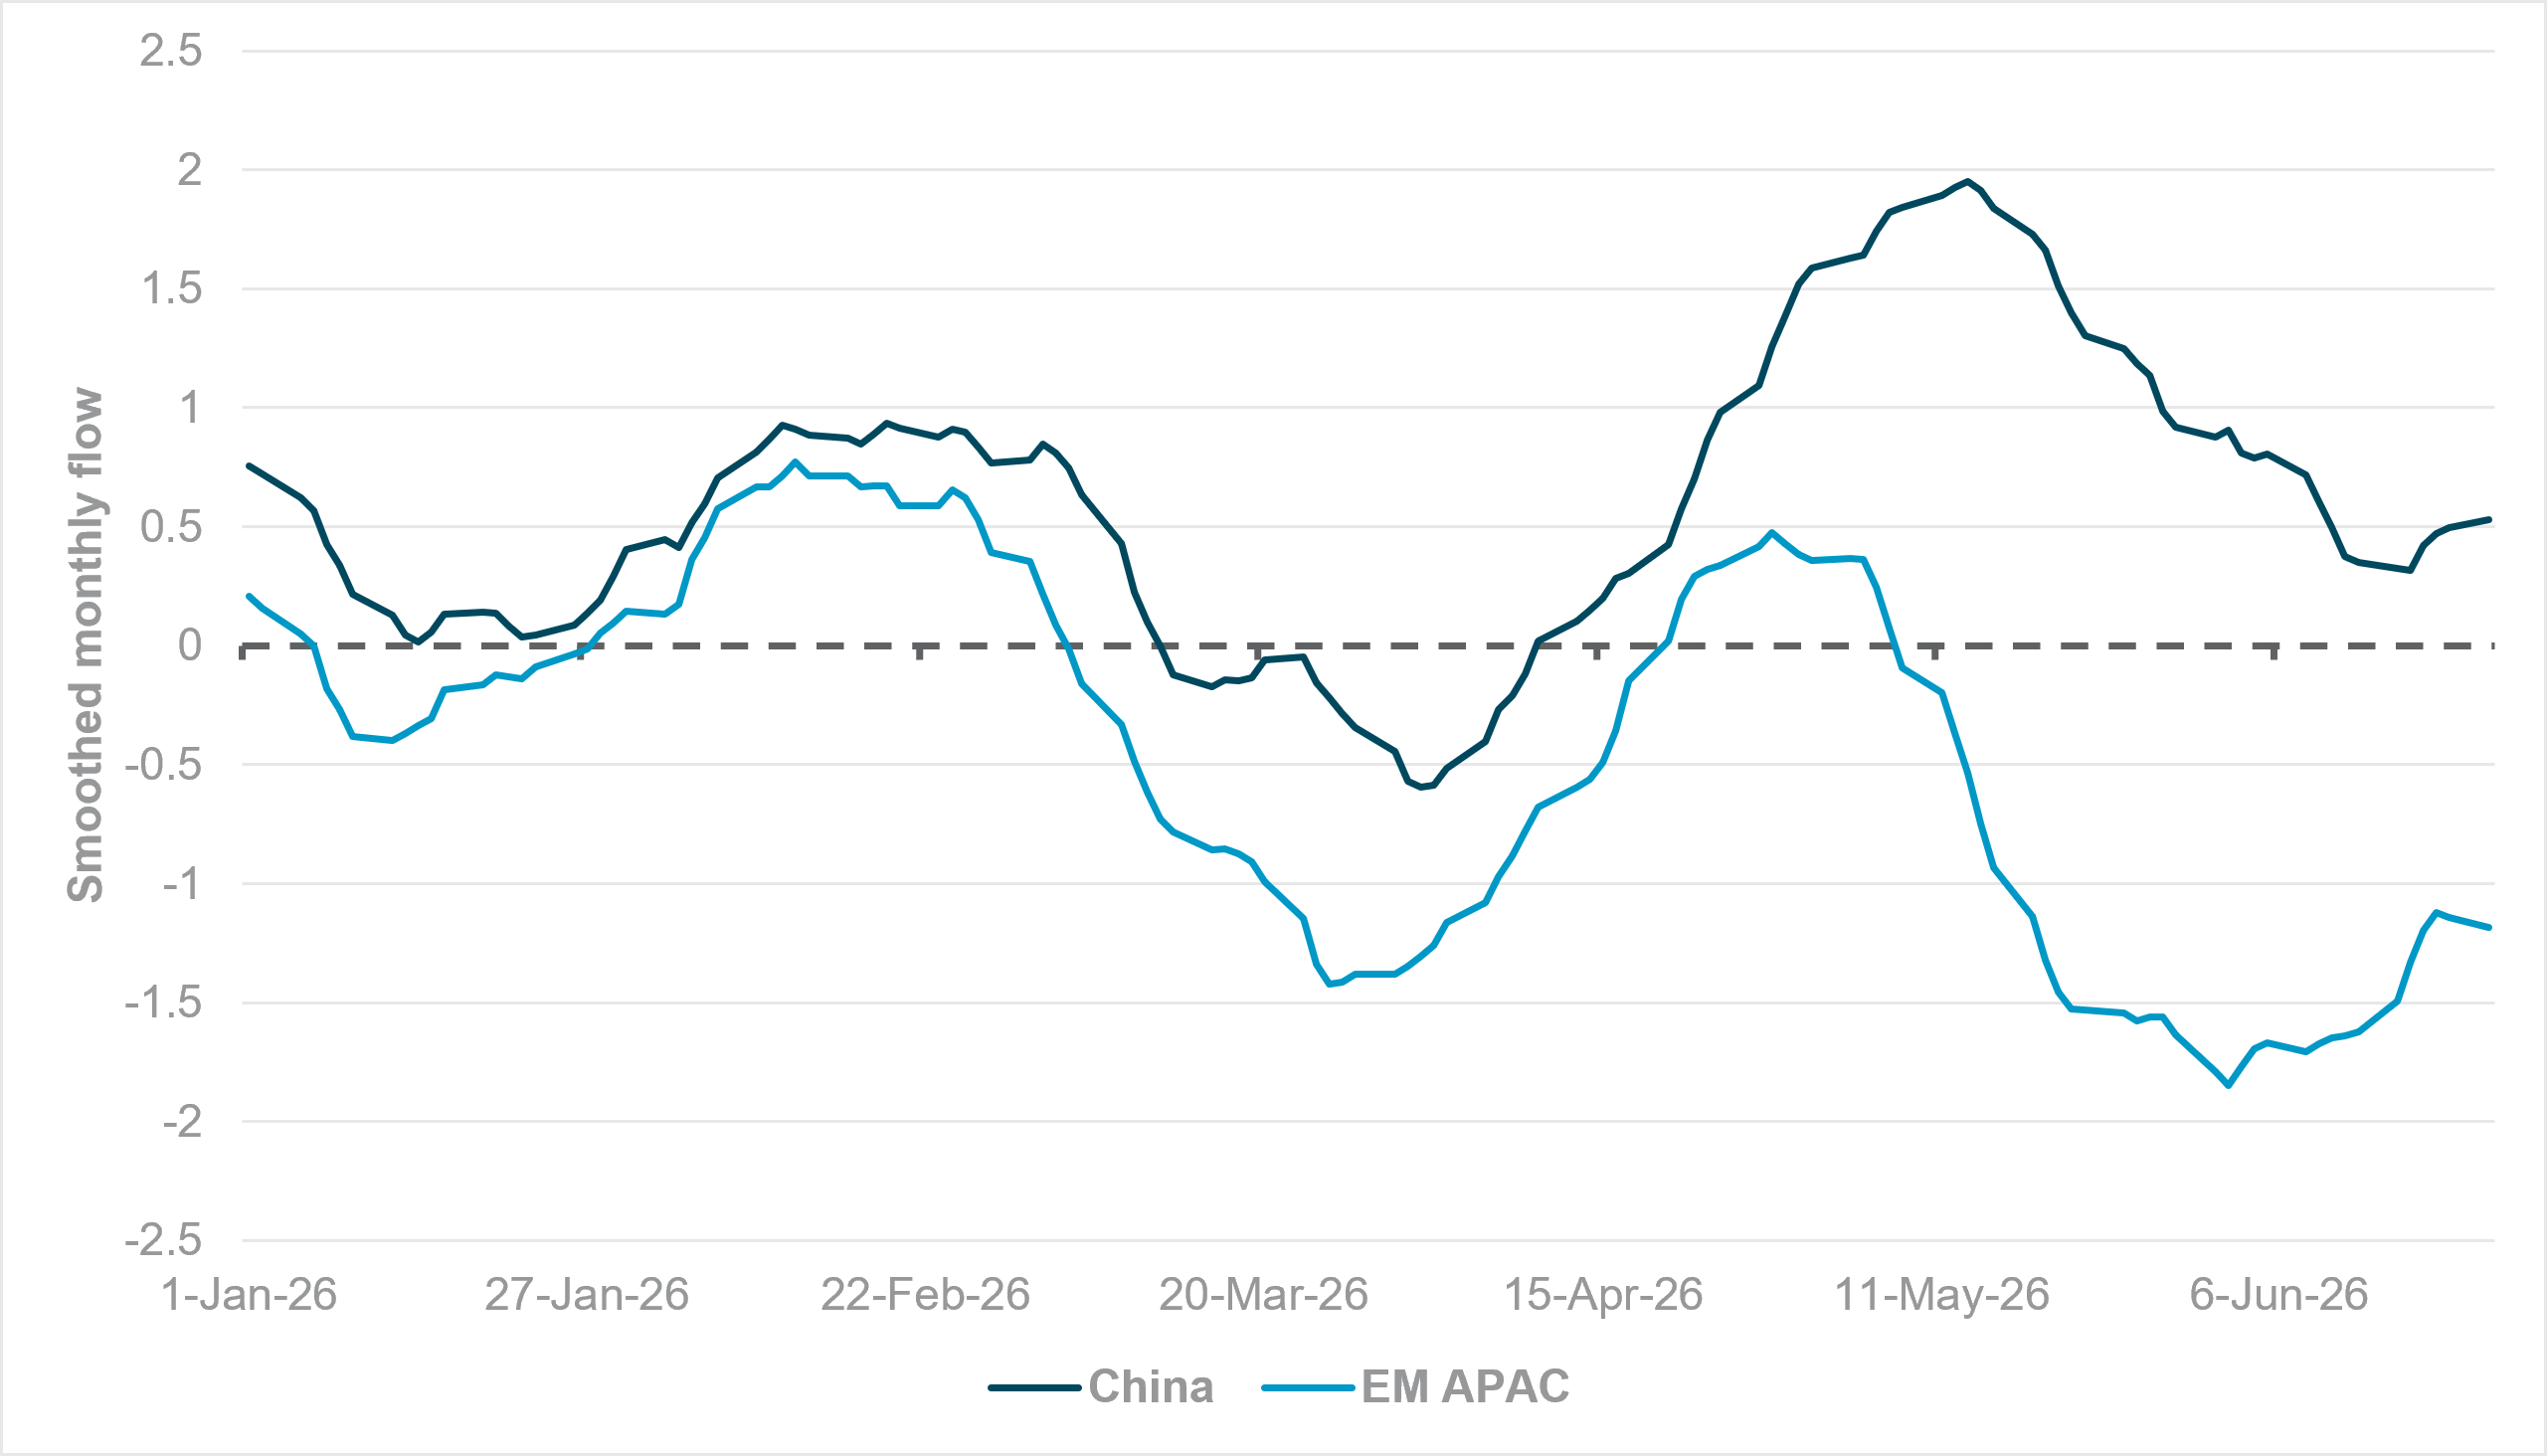
EXHIBIT #2: INSTITUTIONAL FLOWS, CHINA VS. EM APAC
Source: BNY
Our take
The Hong Kong China Enterprises Index has entered a bear market from its October 2025 high, becoming the latest China-focused benchmark to do so. Despite this weakness, our data shows institutional investors continue to buy Chinese equities, with inflows outperforming the rest of Asia (Exhibit 2) where sentiment has been weighed down by outflows from South Korea and Taiwan. However, Chinese equities have fallen 15% to 16% this year, meaning losses on existing holdings have more than offset the value of new purchases.
It is also important to put the current holdings ranking into context. China holdings currently rank in the eighth percentile of their 2026 range, but that range has been exceptionally tight: holdings have fluctuated between roughly 10% and 18% above their rolling 12-month average throughout the year. In other words, the low percentile ranking reflects a modest decline from elevated starting levels rather than an outright underweight position. Investors have reduced exposure relative to earlier-year highs, but positioning remains elevated when viewed against a longer historical backdrop.
Forward look
Investors appear to be buying Chinese equities because the recent selloff has created a more attractive entry point. Major China ETFs are down close to 20% from their year-to-date highs and more than 12% below their 200-day moving averages, leaving the market deeply oversold. Yet valuations remain relatively undemanding, with the Shanghai Stock Exchange trading on a trailing P/E of 17.6x and the HSCEI on 11.3x. For many institutional investors, the decline in prices appears greater than any deterioration in the long-term investment case, supporting a buy-the-dip mentality.
Domestic demand is clearly soft and contributed to the recent selloff. Nonetheless, the external sector remains resilient, much to the chagrin of the key trading partners which portends greater conflict ahead, especially with the EU. From an asset allocation perspective, the combination of attractive valuations, better export data and the potential for further policy support in response to equity market signaling helps explain why cross-border investors continue to add exposure despite recent market weakness.
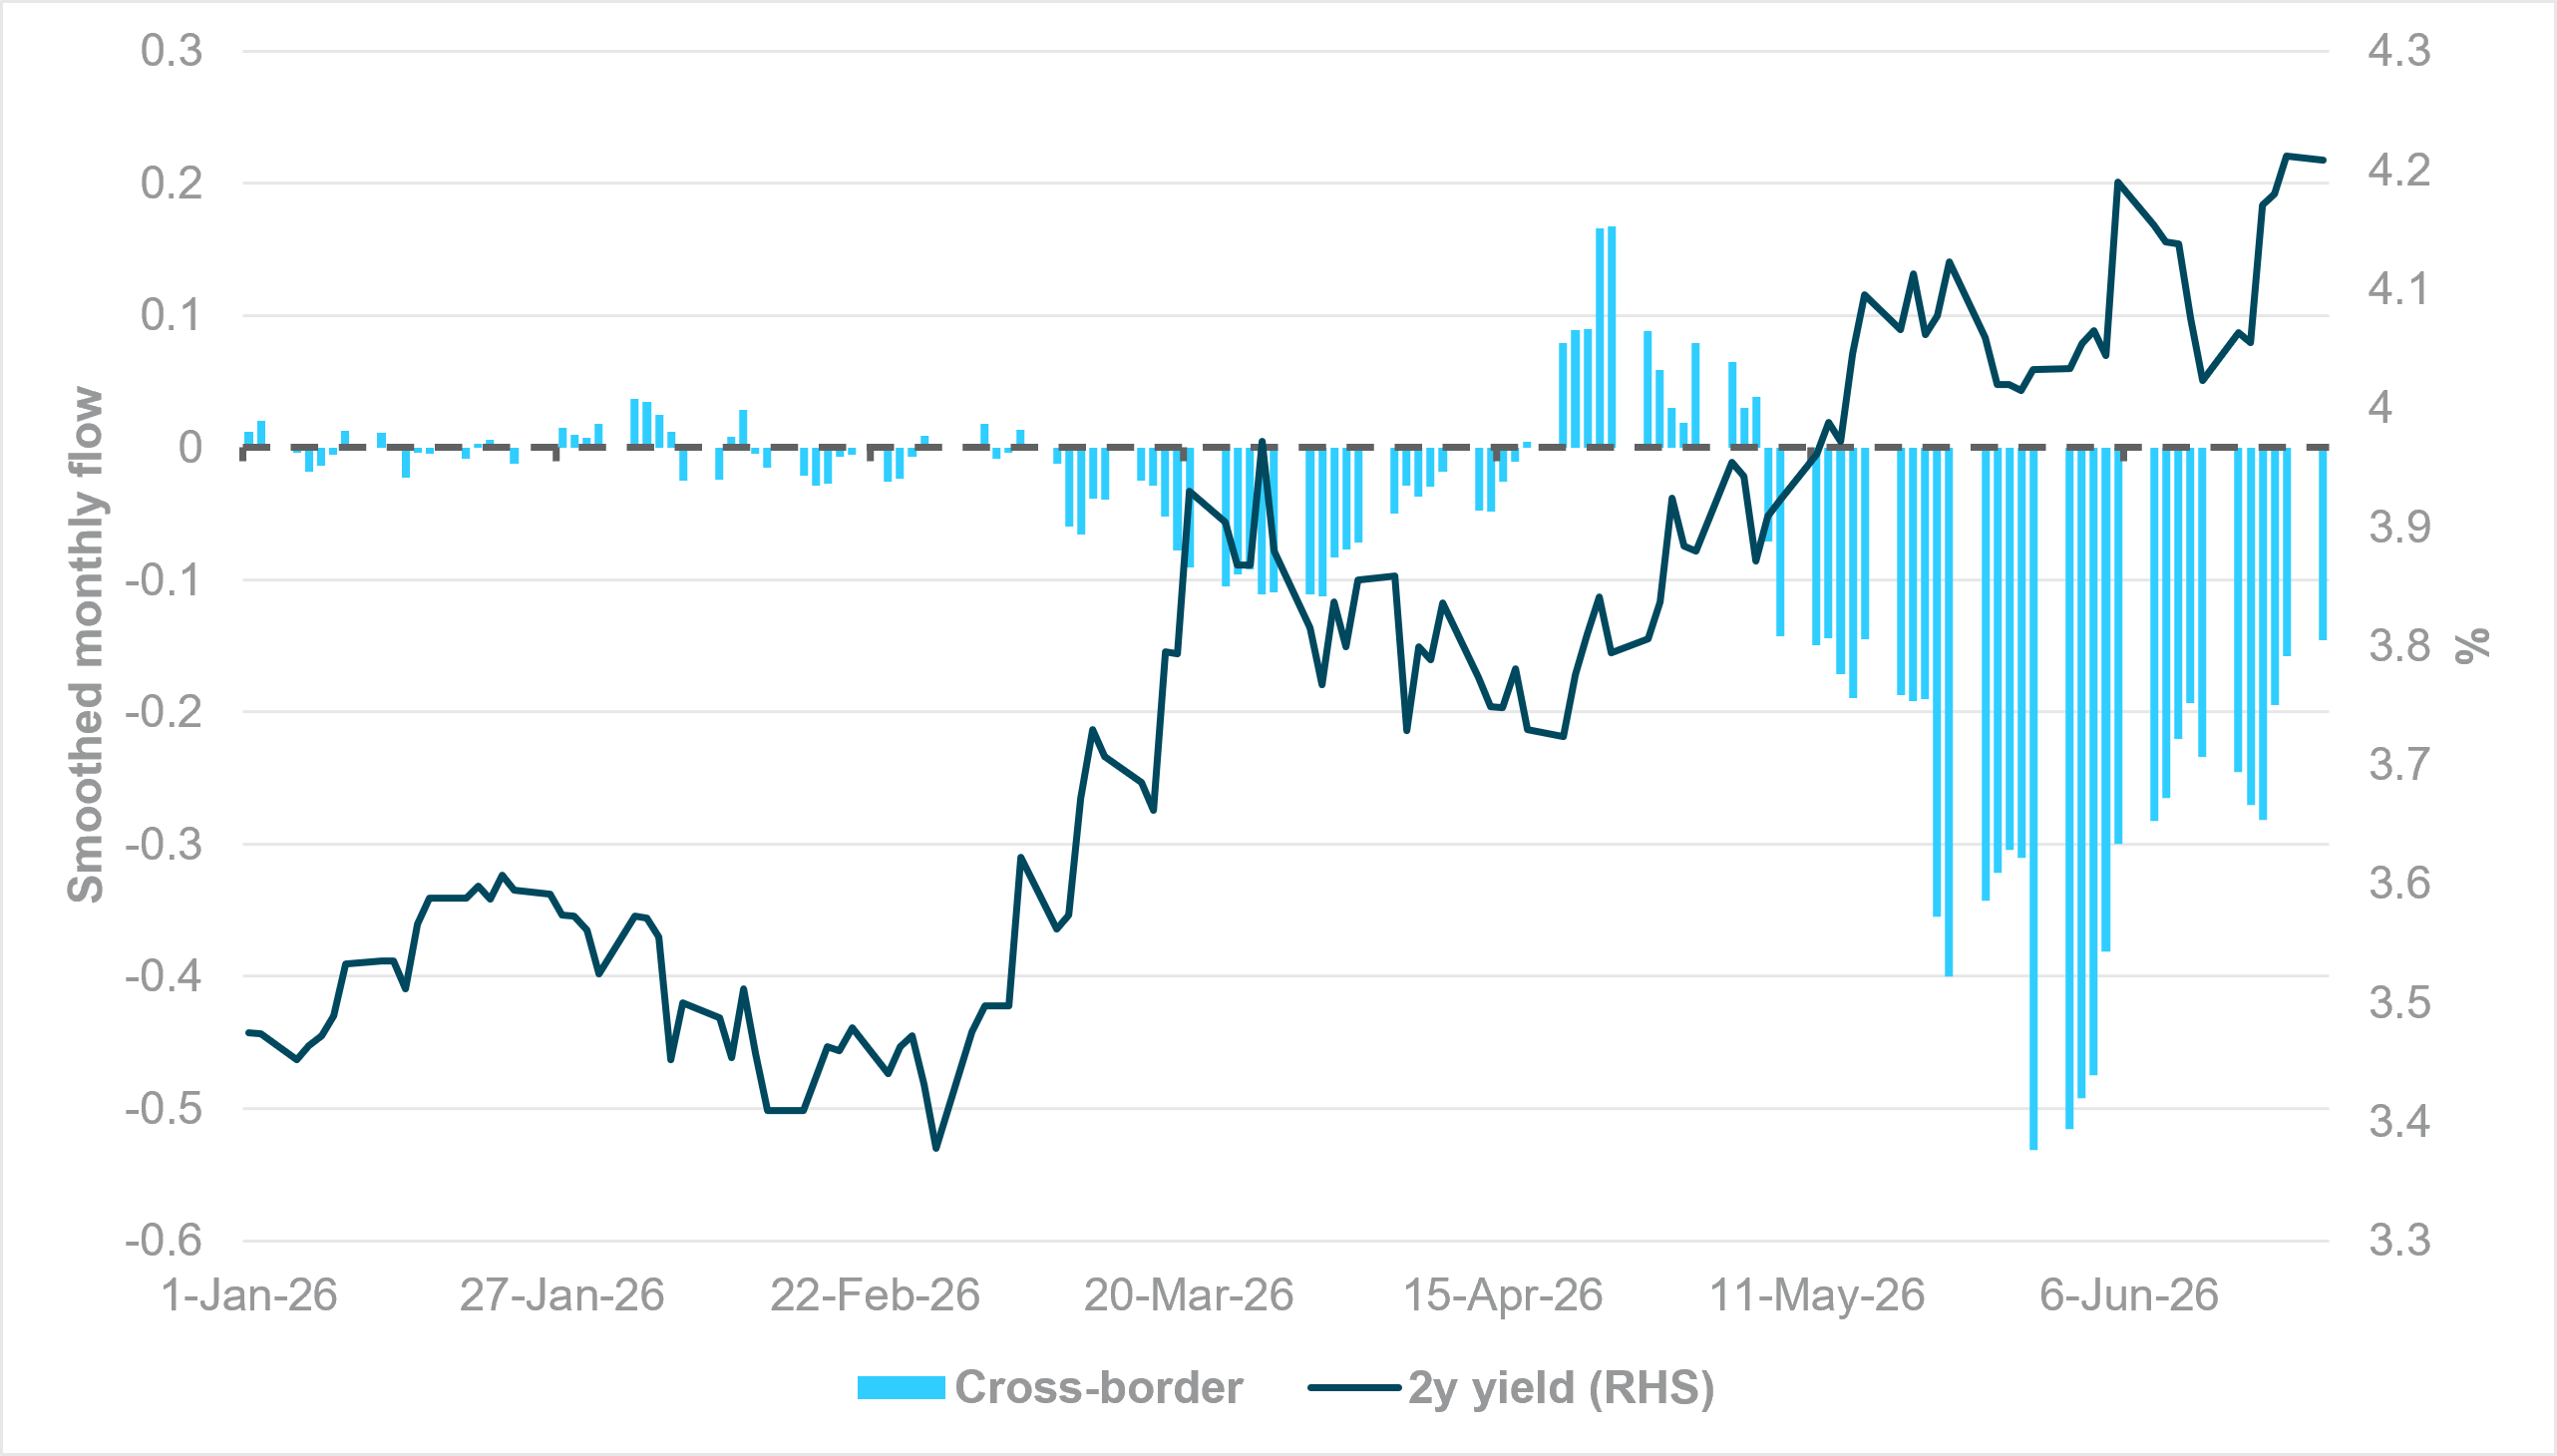
EXHIBIT #3: MONTHLY SMOOTHED USD CAST FLOW (CROSS-BORDER ONLY) VS. 2Y YIELD
Source: BNY
Our take
The dollar did not see aggressive cross-border buying around last week's Fed meeting and IMM dates, largely because hedge reduction has been underway since late April. Our data show that cross-border dollar underweights moved from roughly 10% above their rolling 12-month average (holdings score -1.10) to around 20% below (holdings score -0.80) by the end of last week. We therefore view recent dollar strength as a reflection of renewed U.S. exceptionalism rather than fresh positioning demand, particularly as currency valuations appear more attractive than their equity market counterparts.
However, we are not seeing the same interest in cash and short-term instruments (CAST), despite rising U.S. yields. This asset class is typically highly sensitive to rate expectations and often benefits during periods of market stress as investors raise cash. Instead, cross-border investors are liquidating CAST at the fastest pace of the year, even with higher yields and a generally supportive risk backdrop (Exhibit 3). Aggregate flows remain much more stable, suggesting domestic demand is offsetting foreign selling.
Forward look
While risk appetite has improved, we believe current CAST sales are still linked to the conflict. In March, a sharp rise in risk aversion triggered widespread liquidation of U.S. assets by cross-border investors, regardless of asset class, as investors scrambled for dollar liquidity amid severe balance-of-payments pressures. Some of those liquidity needs persist. Resources are now being redirected to address supply disruptions and funding requirements for the remainder of the year. In addition, several Gulf economies face reconstruction needs, while energy export revenues may take years to fully normalize. Cash buffers are also being drawn down ahead of a busy capital markets calendar, particularly in technology, where the issuance pipeline remains strong. A reversal in CAST outflows would be notable. It could signal that enthusiasm for the current investment themes is beginning to fade and that investors prefer to rebuild cash reserves rather than deploy additional capital.