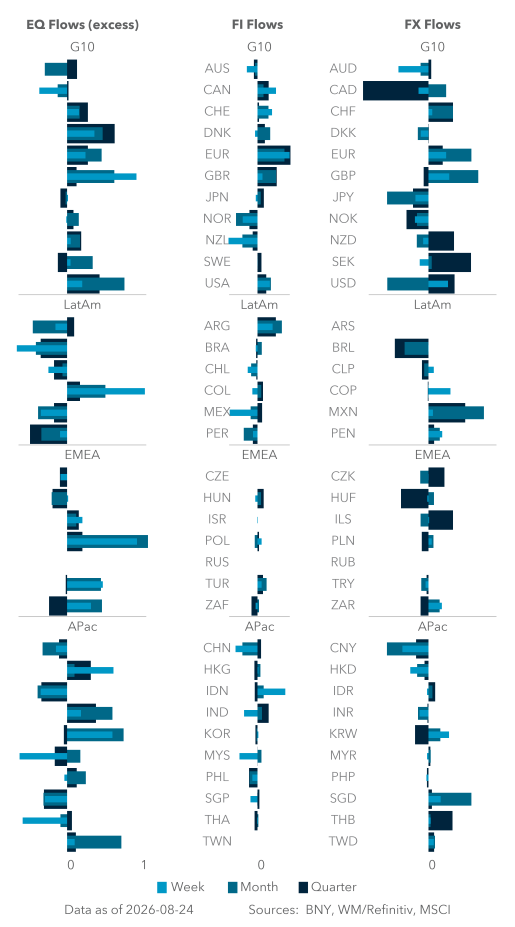
Diversification from U.S. remains selective
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.
iFlow > Investor Trends
Investor Trends provides a deep dive into patterns and behaviors in equity, bond and currency markets around the globe, underpinned with deeper macro insights.

Geoff Yu
Time to Read: 4 minutes
The Treasury buyback shifted prices, not positioning. Cross-border U.S. exposure has stabilized, U.S. equity holdings are recovering, and dollar cash outflows still look tactical rather than the start of a broad exit. EM EMEA equities are the surprise winner but flows remain idiosyncratic rather than evidence of a uniform rotation away from U.S. assets. The key fault line is still U.S. real-rate credibility, with the Fed-controlled front end more important for FX than Treasury support at the long end.
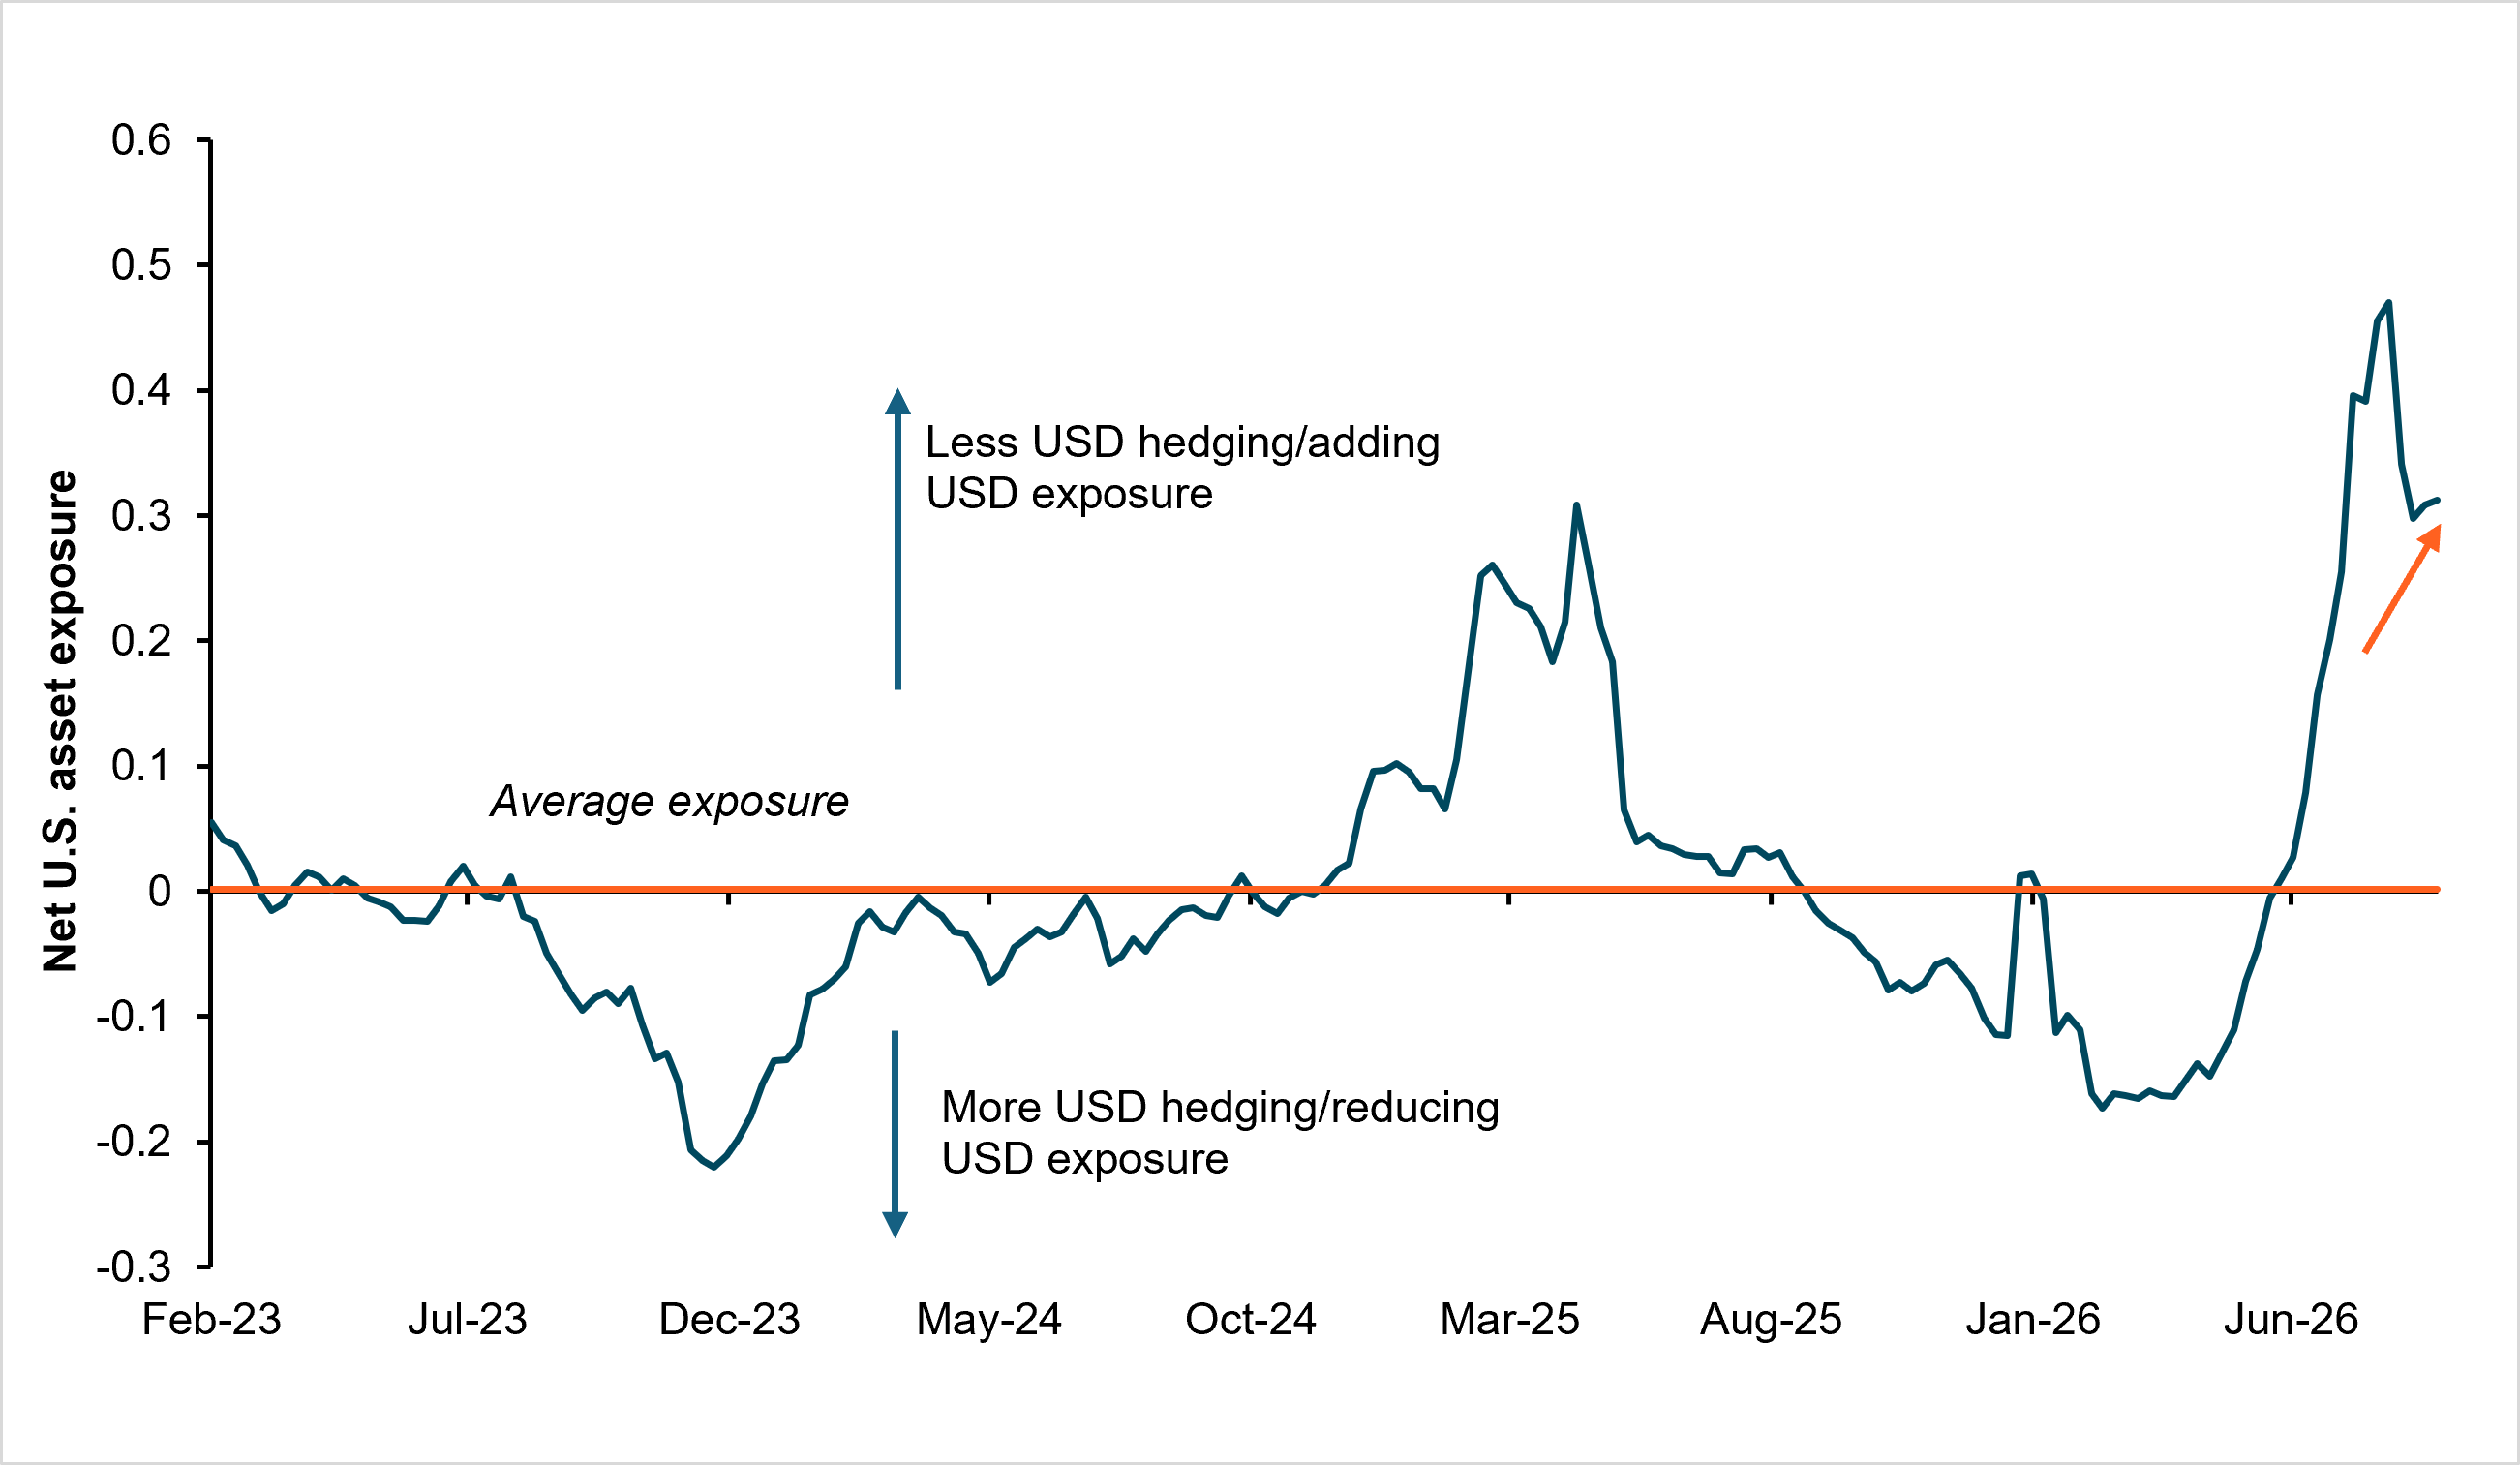
EXHIBIT #1: NET U.S. ASSET EXPOSURES, CROSS-BORDER BASIS
Source: BNY
Our take
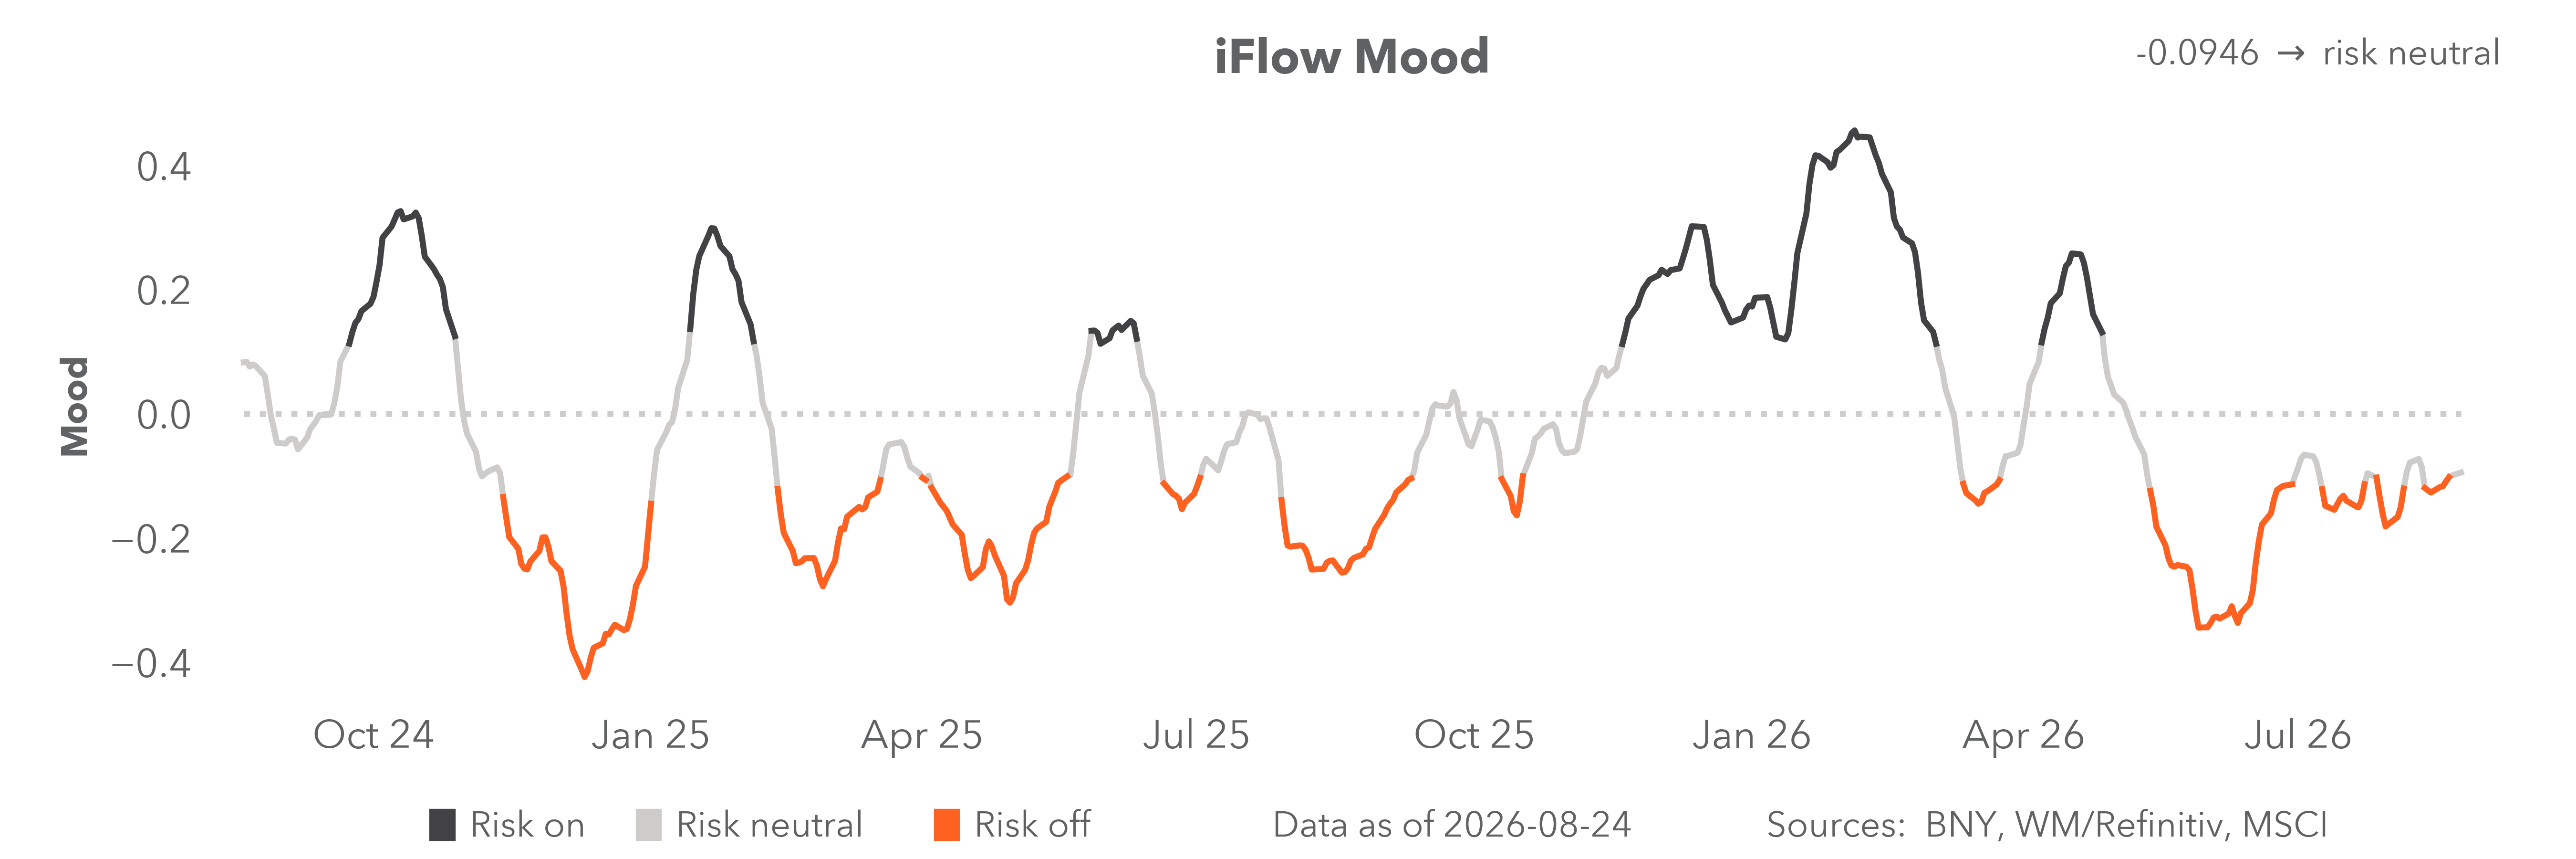
U.S. exposures have stabilized. Based on the latest weekly update to our cross-border net U.S. asset positioning, non-U.S. domiciled investors aren’t pushing to further reduce their exposures. Our data show that outright FX hedges, measured by cross-border dollar holdings, have remained largely unchanged over the past two weeks, while there has been some improvement in equity holdings as risk sentiment stabilized.
The July Fed mattered more for FX. The drop in U.S. exposures was mostly driven by an increase in dollar hedges. In hindsight, although the market reacted to the Treasury buyback decision in a similar manner to any policy result that causes a drop in U.S. real rates, the Fed continues to anchor the front end of the curve, and this is where FX sensitivities matter more. However, as the net result is an easing in financial conditions which boosts equity and Treasury levels, asset holdings improvements can offset FX losses.
Forward look
The buyback’s market impact proves marginal. We stress that this matters in both directions for sentiment. As we highlighted yesterday, the rally and yield retrenchment suggest that the maneuver had limited direct effects on the market beyond the initial impact of the announcement. On the other hand, stabilization in exposures suggests that questions over policy credibility can also wait. If U.S. data and corporate earnings deliver, there is no strong pull toward comprehensive rotation, especially given the lack of alternatives. The dollar has already served its purpose as a release valve, but diversification remains selective as the U.S. macro narrative stays unchanged.
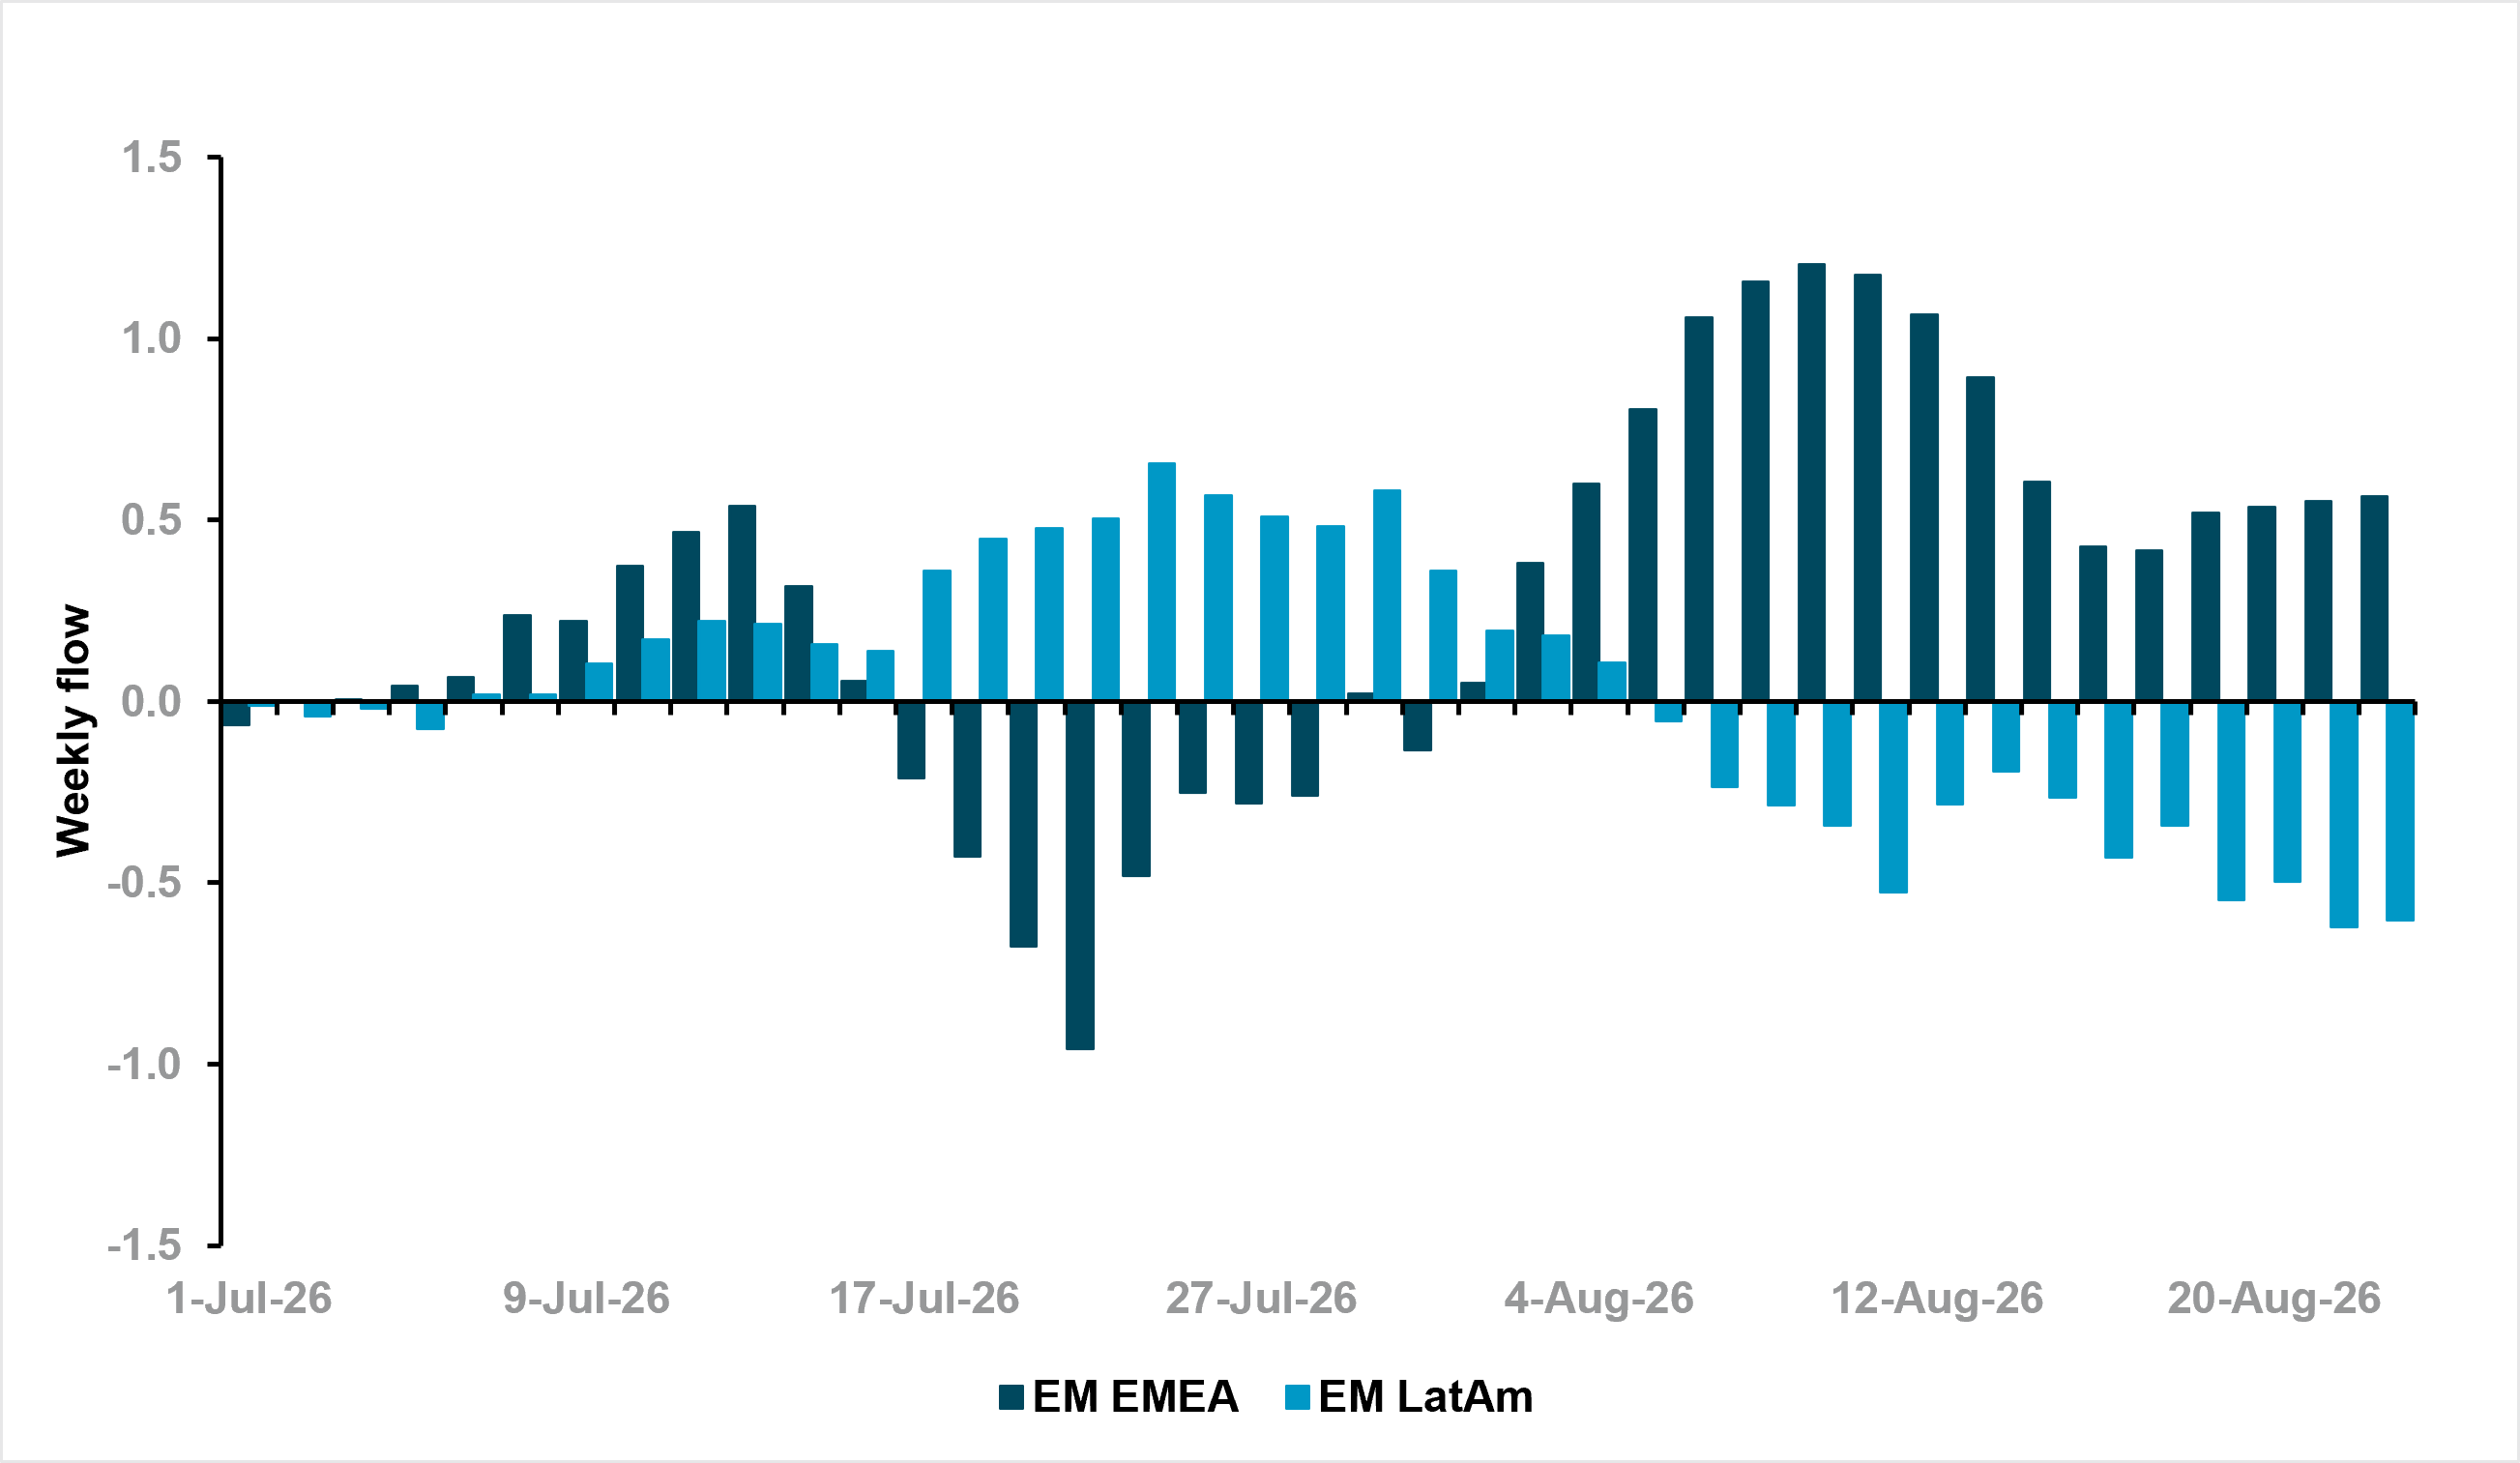
EXHIBIT #2: WEEKLY SMOOTHED FLOW, EM EMEA AND EM LATIN AMERICA EQUITIES
Source: BNY
Our take
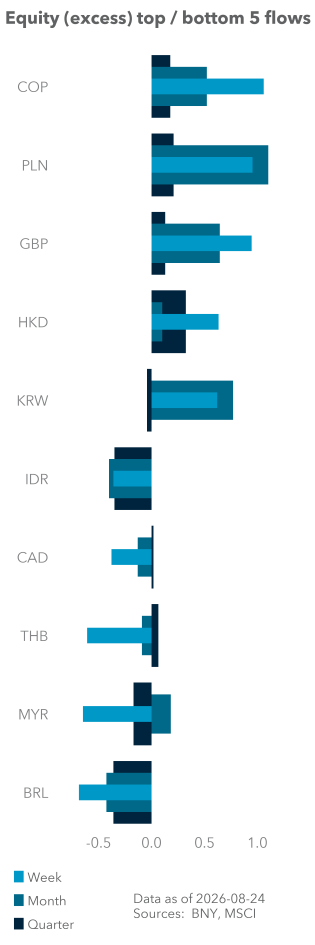
EM EMEA is the regional equity outperformer. Over the past week – covering the Treasury buyback announcement – our flow data indicate Poland, South Africa and Turkey were in the top five of best-bought equity markets. Our data show that this isn’t a one-week story, as the region has been strongly bought since right before the July Fed meeting. This stands in stark contrast to the lack of strength in the region’s currencies and bonds, which stood to benefit more from weaker USD real rates.
EM EMEA markets are diverse, which means it’s important not to read a common narrative into the data. If low USD real rates or general weakness in global real rates is a driver, then Poland, South Africa and Turkey do offer some duration lift, as well as dividend yields. Poland and South Africa currently have dividend yields of around 3.5%, while Turkey’s is higher at 6.33%. In real terms, these aren’t exactly stellar and are a poor substitute for duration in an EM asset allocation context.
Forward look
U.S. equity diversification isn’t an EM play. As stated above, cross-border holdings of U.S. equities have improved. There is only room for additional flow on the margins and in a highly selective manner. On a sectoral basis there are other factors in play, such as industrials in Poland and Turkey, while metals and mining drives South African market performance.
We don’t see a uniform “U.S.” theme in EM equity flows. If the market were to push for “debasement,” EM Americas should be the prime beneficiary due to much heavier commodity exposure. This was the case in Q1 in markets such as Brazil and Peru, with the latter benefiting significantly from the surge in silver prices. We continue to target better performance in high-carry EM duration as a hedge against dollar risk, whereas EM equities will need to rely on idiosyncratic factors and a broader shift in asset allocation preferences.
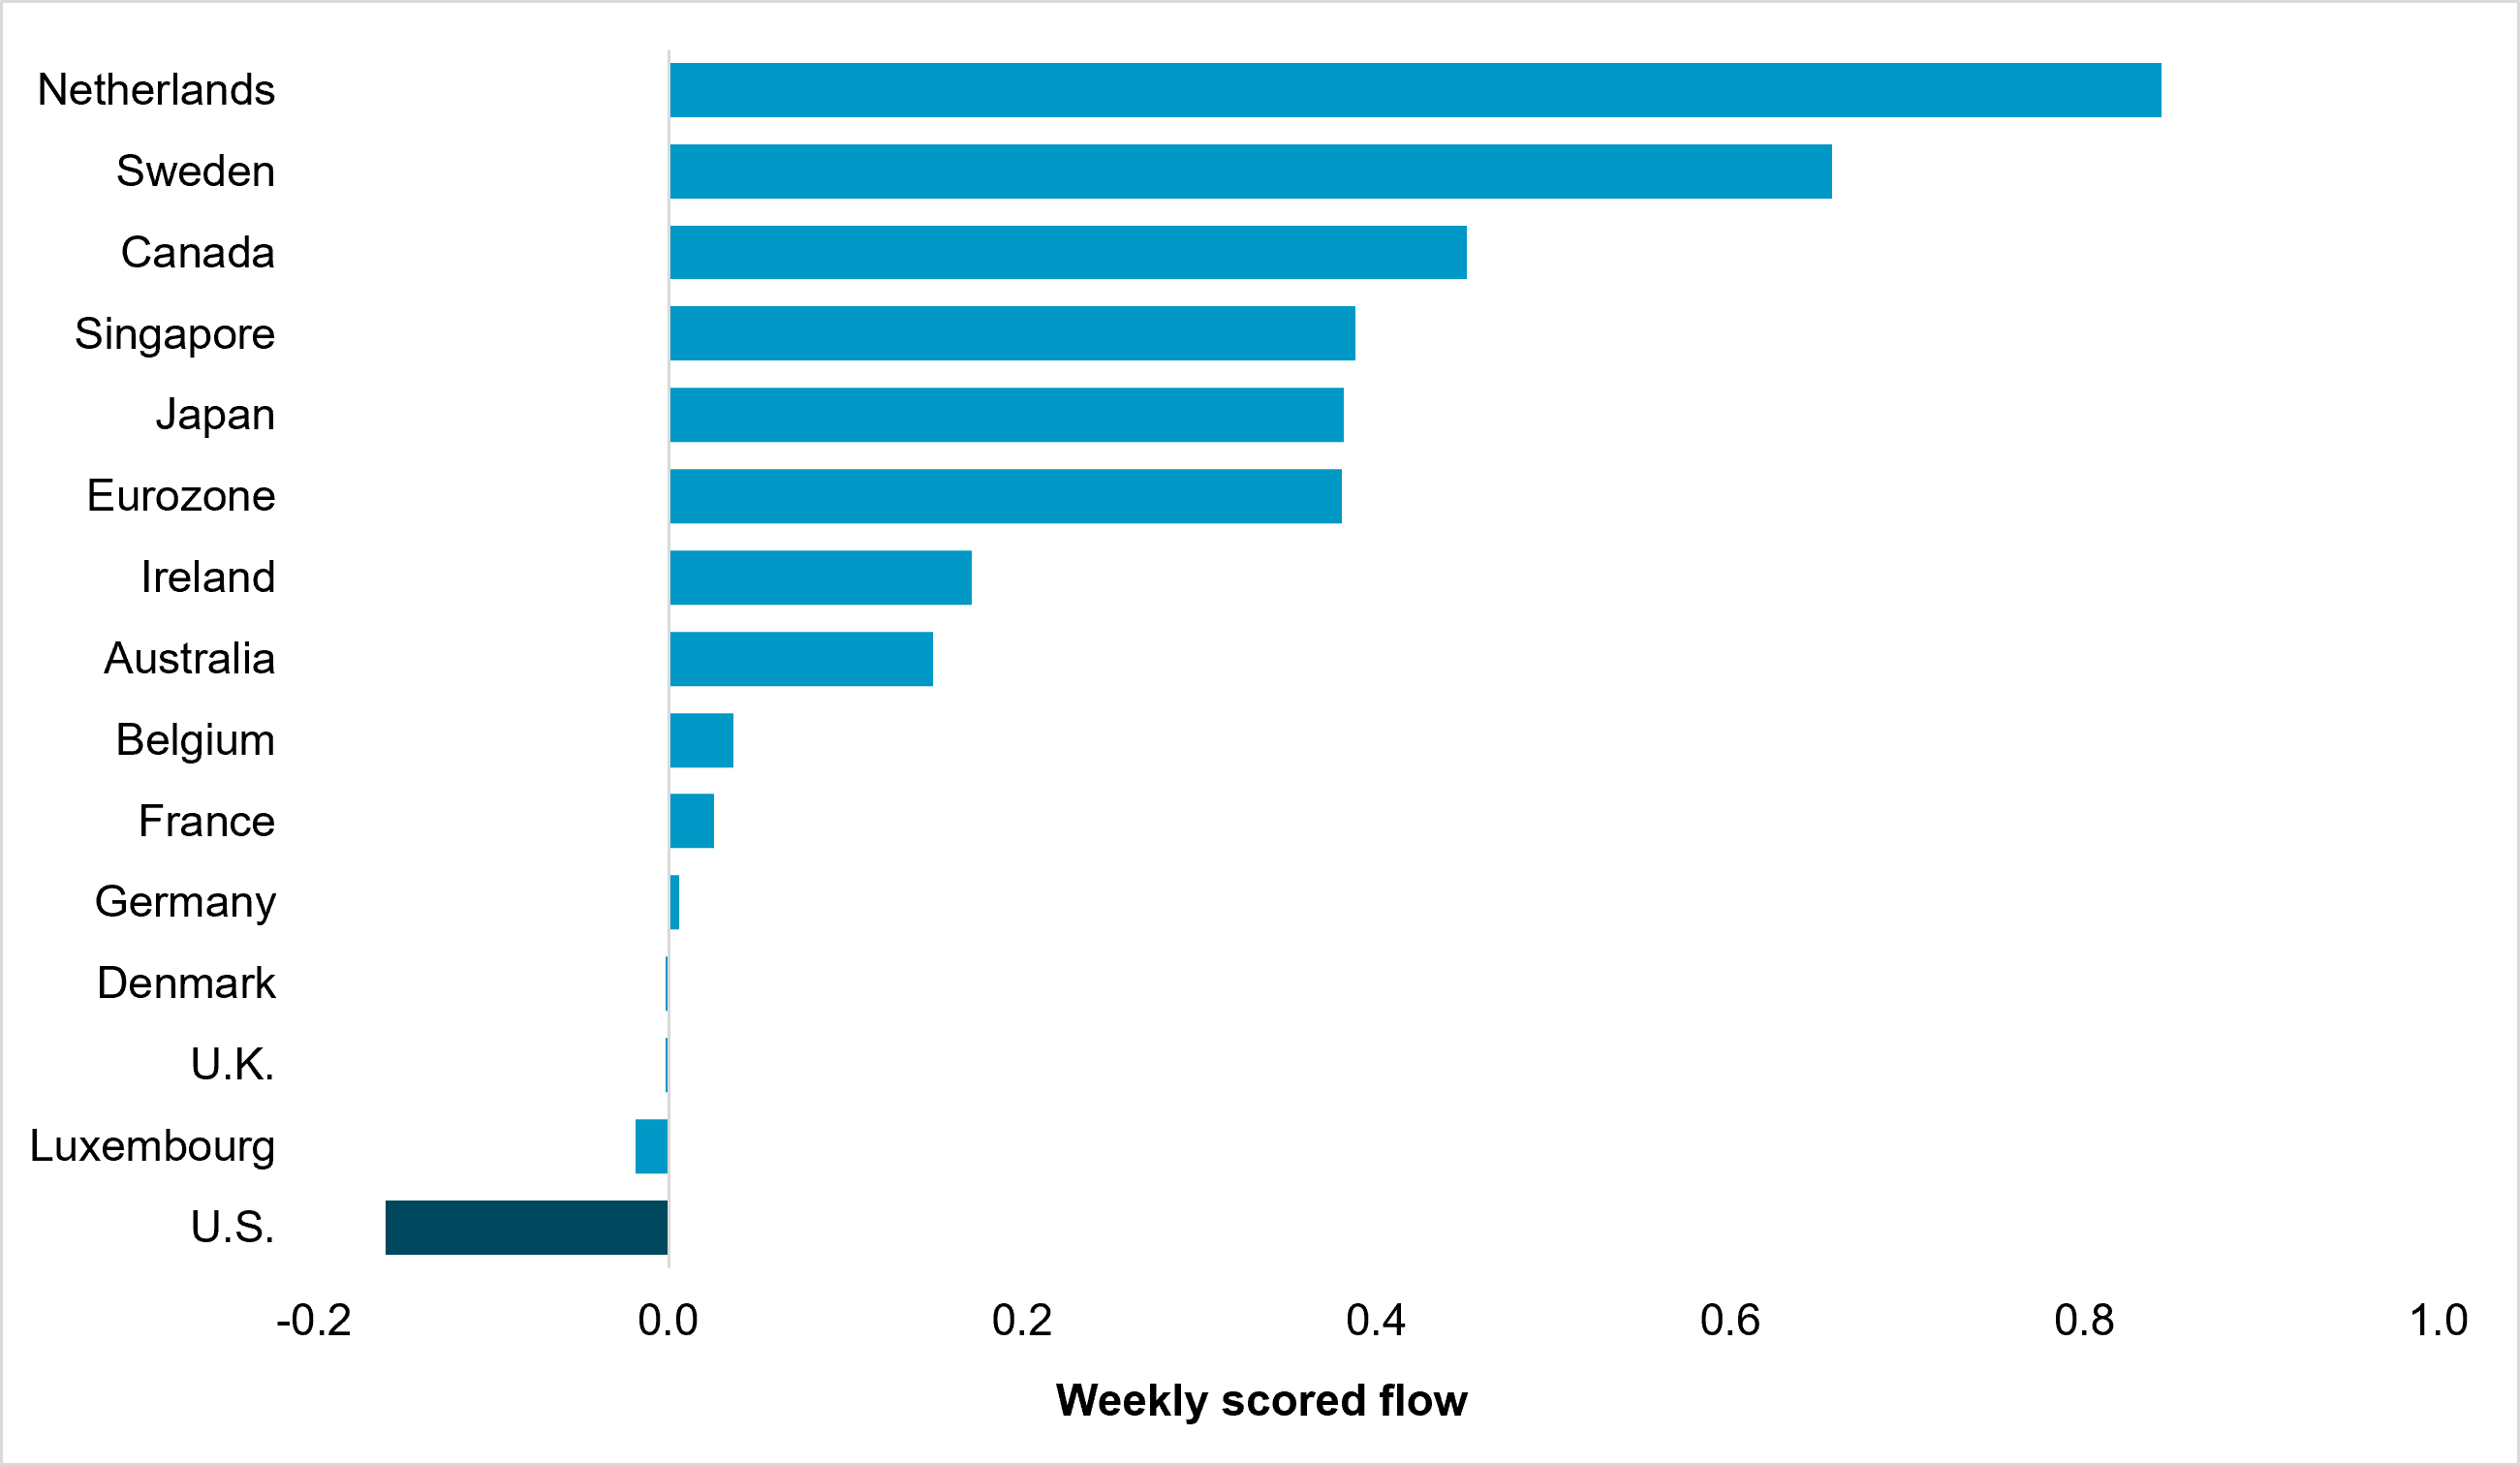
EXHIBIT #3: CAST WEEKLY SCORED FLOW
Source: BNY
Our take
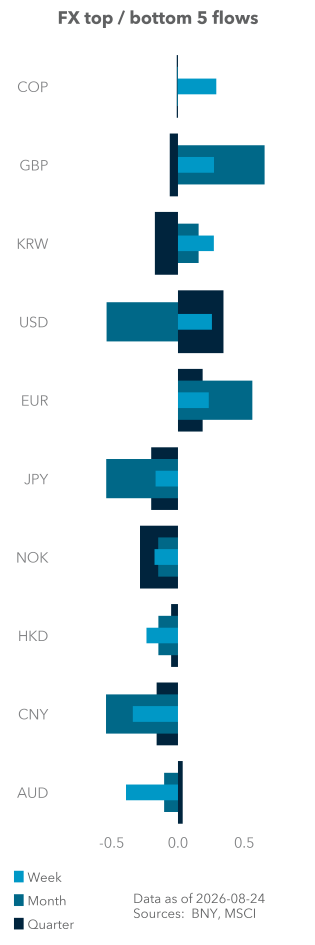
Cash and short-term instruments (CAST) are the weak link. Cash markets remain highly sensitive to outright yields and rate expectations, and the dollar appears to be faltering on the latter. While dollar real rates retain a slight advantage ahead of G10 peers, the direction of travel is increasingly concerning. Over the past week, the greenback was materially sold relative to other major markets, which all found bids, even in markets where nominal yields are already low.
Financial conditions clearly matter. Dollar cash flows lost out – not due to yield levels, but on fears that they were incongruent with financial conditions. If real rates are currently too low relative to growth and financial conditions are too loose, flows will deteriorate. The fear at present is that U.S. actions could cause financial conditions to loosen further which will lead to a pick-up in hedging flows and related cash outflows.
Forward look
Anchoring inflation expectations remains essential. The U.S. Treasury’s decisions have been interpreted as a loosening in financial conditions, but so far there’s no suggestion that inflation expectations are becoming unanchored. Nor have inflation prints begun to surprise strongly to the upside in the wake of the July Fed and more recent Treasury buyback announcement. Consequently, the outflow in U.S. CAST is likely tactical for now. The weeks ahead will provide the true test of policy credibility, as enough time has elapsed since the relevant decisions to register in prices and economic behavior.
Don’t chase a broad debasement or EM beta trade. Maintain selective high-carry EM duration as the cleaner hedge against further dollar and real-rate erosion, while treating EM EMEA equities as a country and sector-selection exercise. Watch dollar cash flows, FX hedging, inflation expectations and U.S. data. A sustained deterioration across these signals would confirm a shift from tactical diversification to structural U.S. exposure reduction.