Strong yuan, more chips
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.

Geoff Yu
Time to Read: 4 minutes
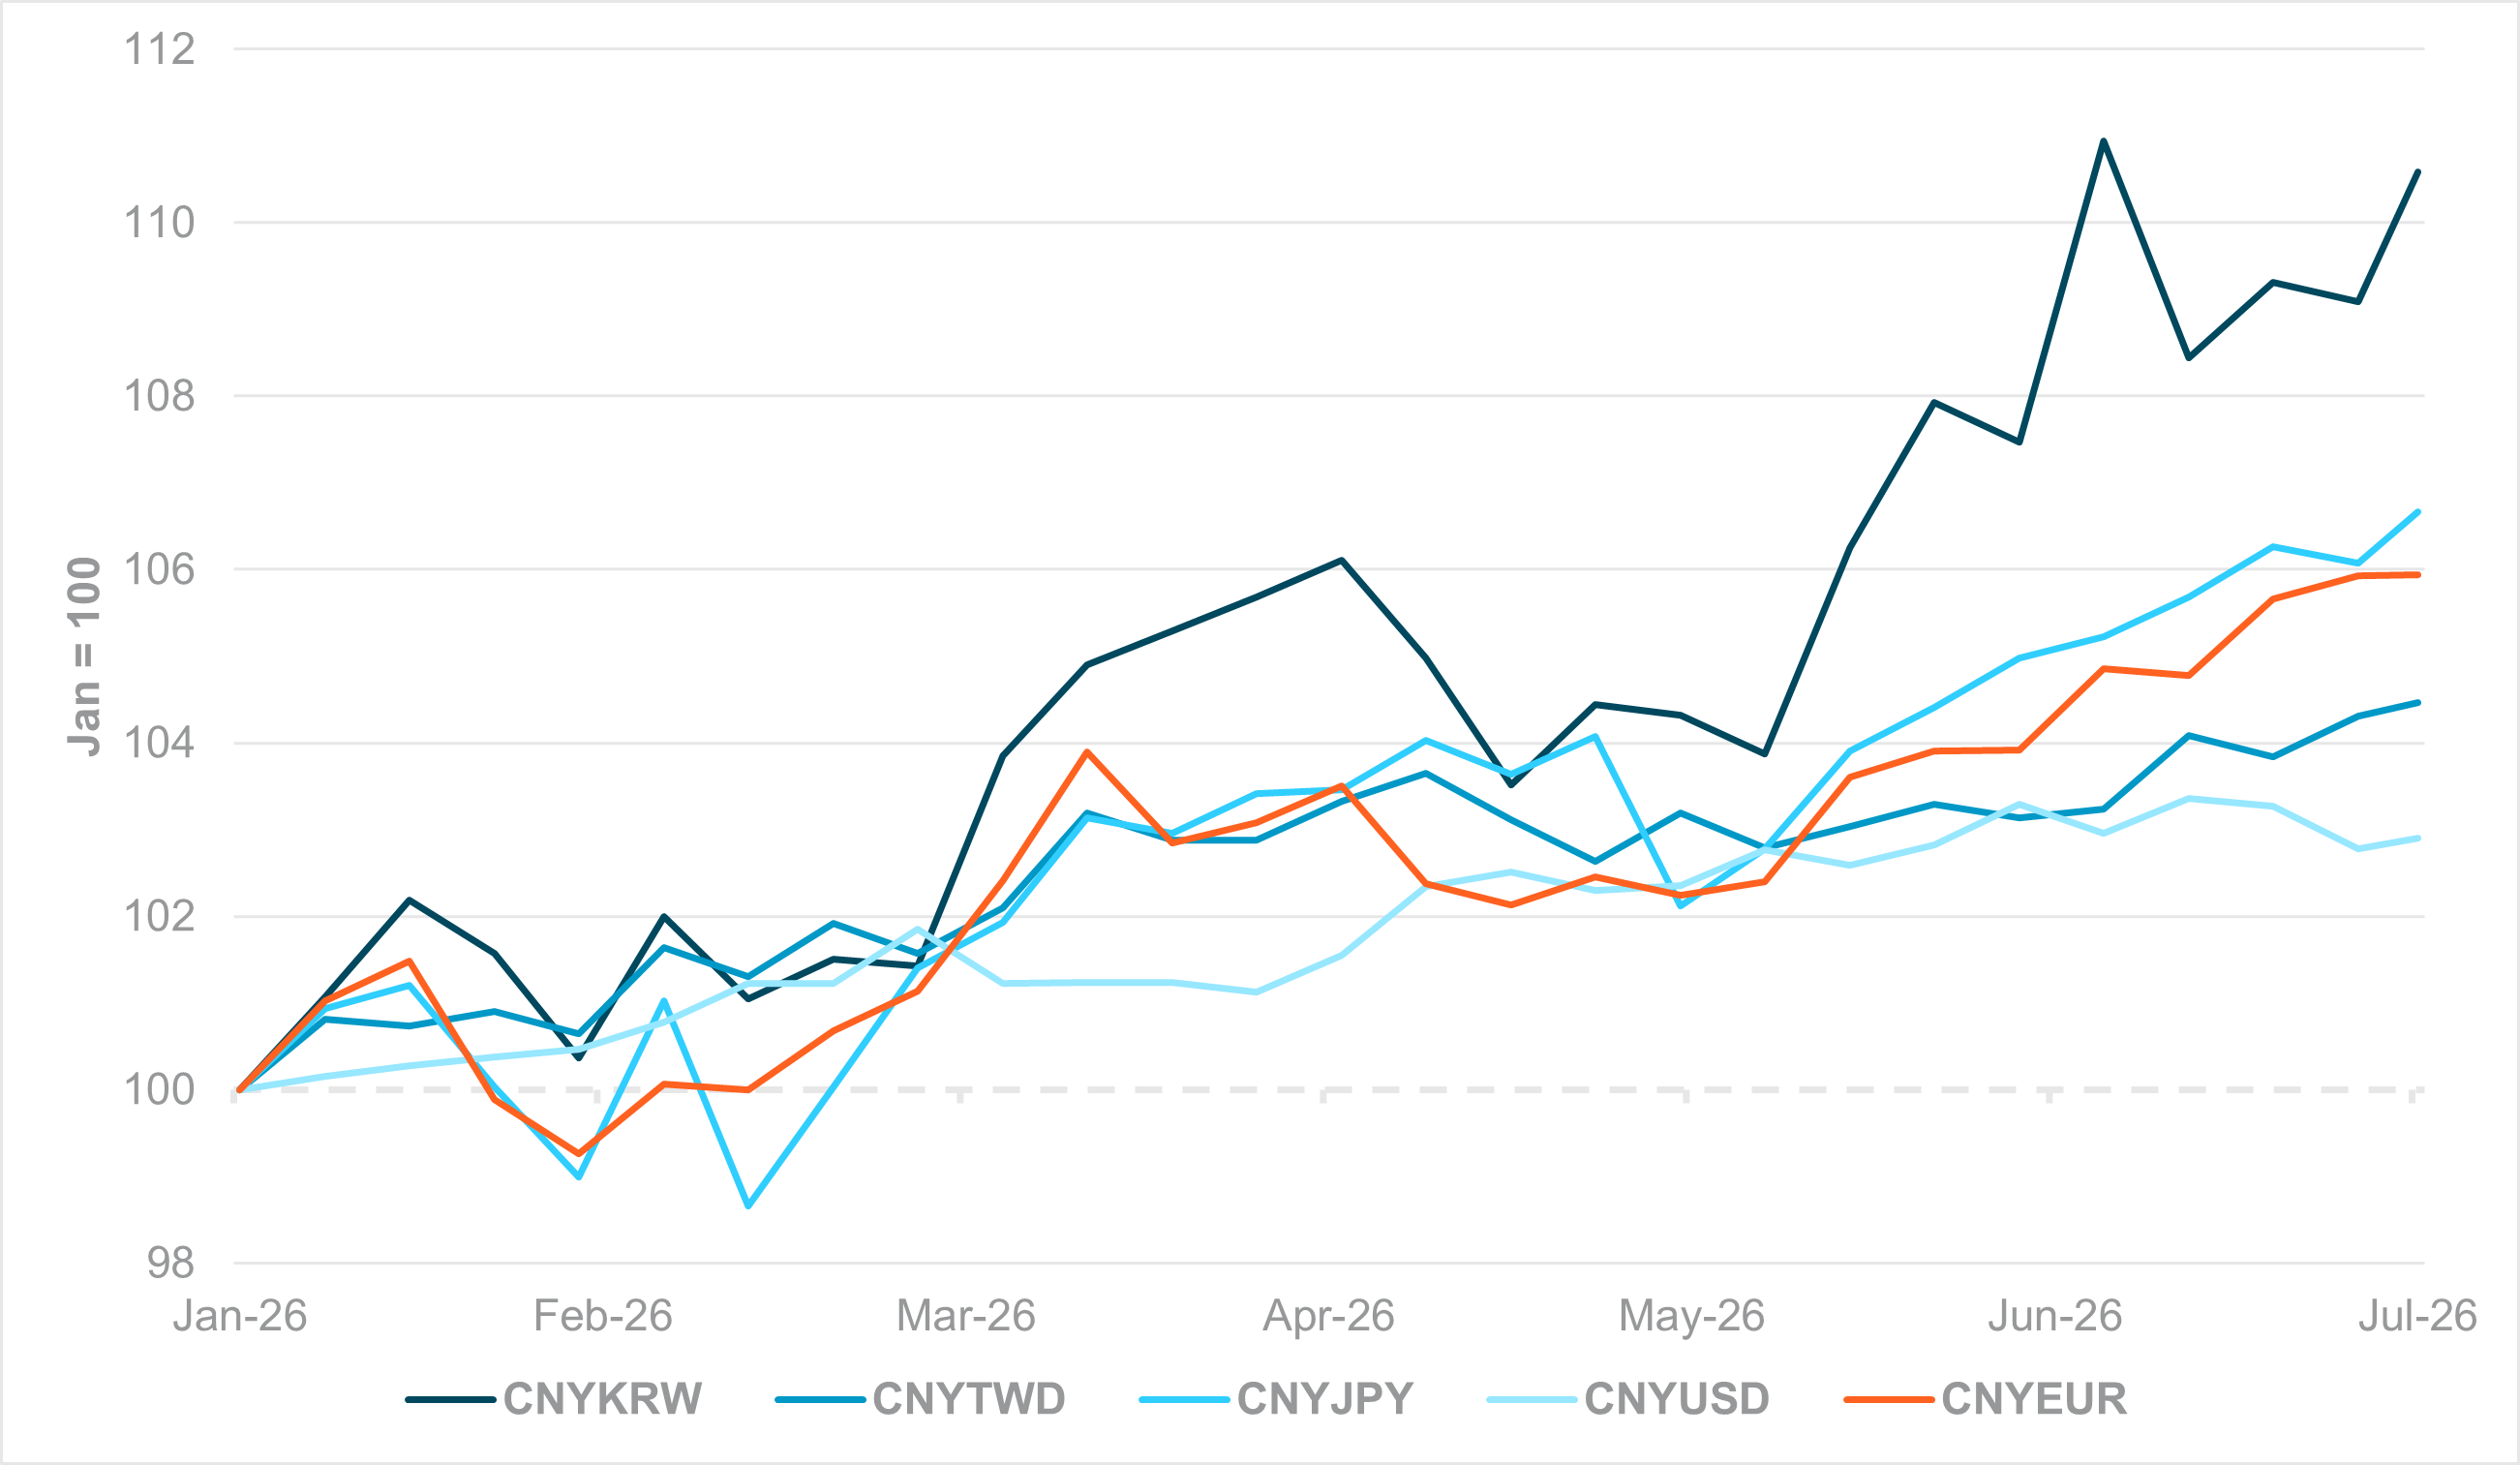
EXHIBIT #1: CNY PERFORMANCE VS. NORTH ASIA 3 CURRENCIES, EUR AND USD
Source: BNY, Bloomberg
Our take
USDJPY is reaching new highs, and FX markets are looking to jump on the USD carry trade again, funded by low-yielding APAC currencies. Although trade is currently less of an issue, we’re surprised that the U.S. and EU are not pursuing the currency misalignments case against North Asian exporters more broadly. Although outright currency management and intervention along China’s lines is comparatively less pronounced, the ongoing large-scale asset manager flows from Japan, South Korea and Taiwan into the U.S. with limited hedging are clearly affecting valuations. We’ll group these three top chip-exporting economies as North Asia 3, or NA-3. As trade surpluses continue to surge – South Korea has become only the fourth economy to ever print a single-month $100bn trade surplus – the volume recycling will only continue.
Forward Look
Current exchange rate misalignments are both exacerbating imbalances and making any case by the U.S. and EU against China’s practices much weaker. In mid-June, German Chancellor Friedrich Merz called for a new Plaza Accord to help address the EU’s trade deficit with China, implying that it was 30% undervalued. Yet in nominal terms, the renminbi has strengthened against the USD, EUR and NA-3 currencies year to date, including close to 11% against the KRW. There are plenty of sectors in advanced manufacturing where Germany competes with the NA-3. Beijing – wary of the impact of the Plaza Accord on the Japanese economy since the mid-1980s – is unlikely to entertain such entreaties.
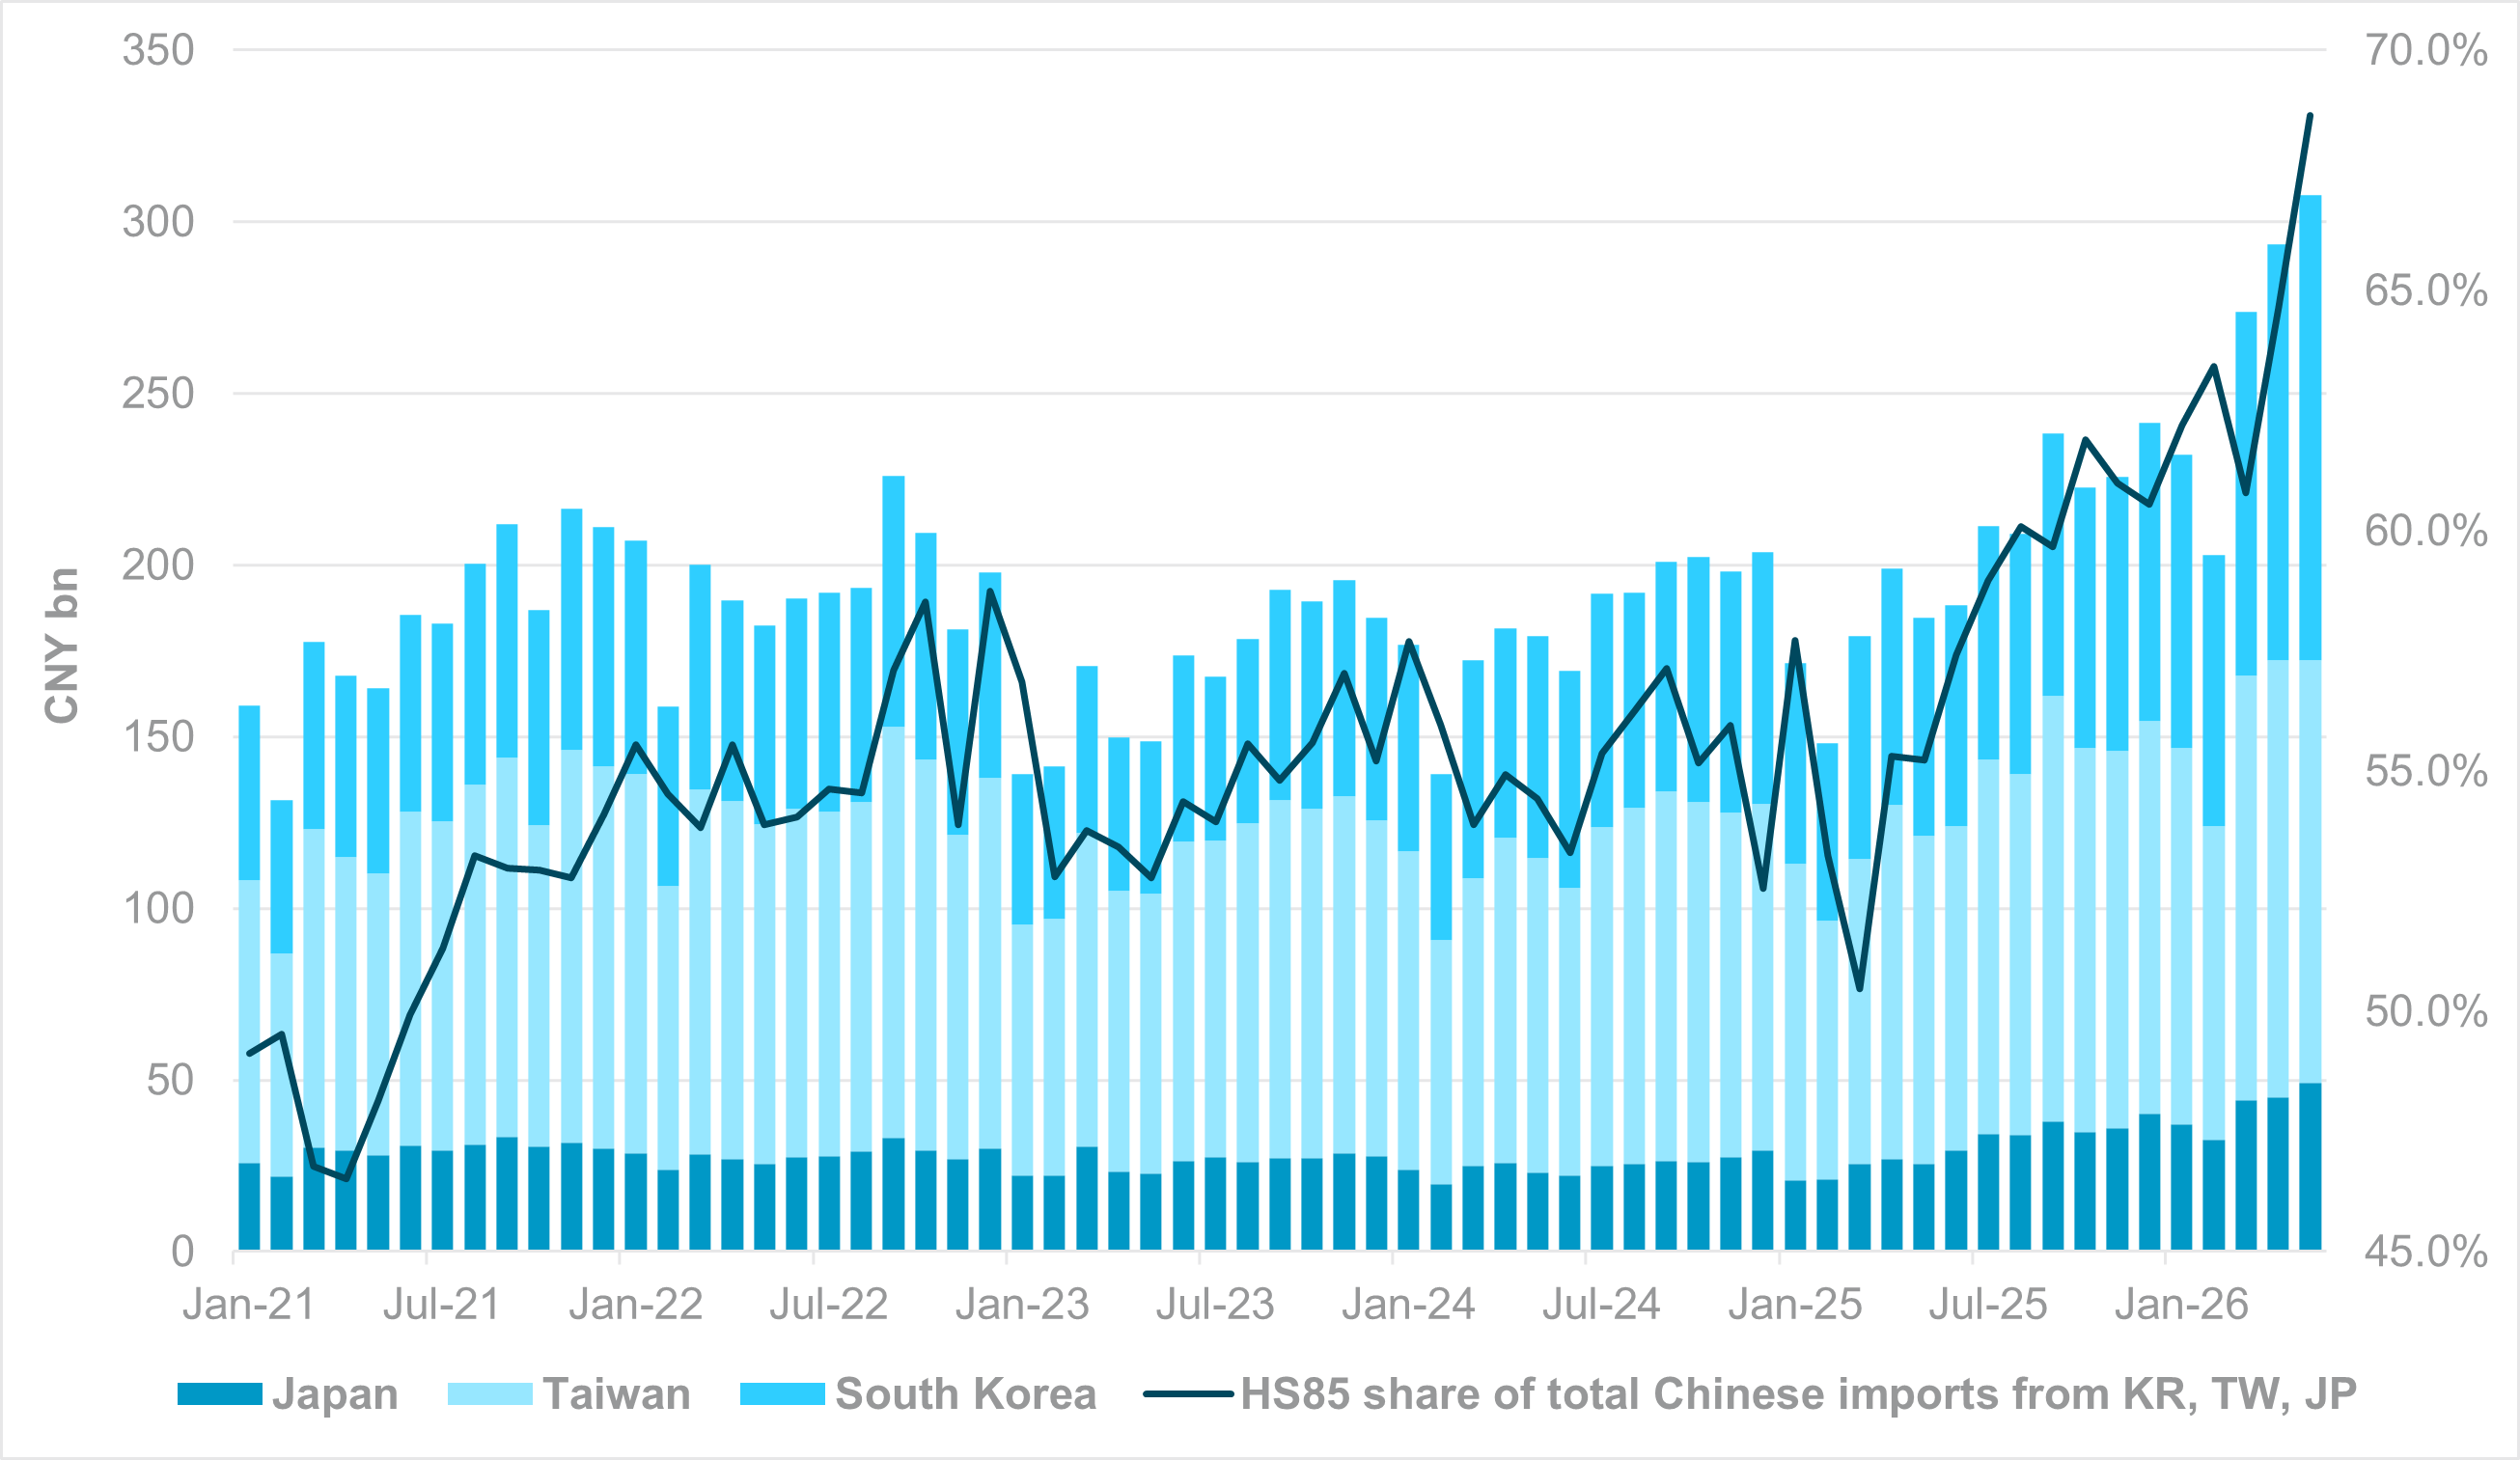
EXHIBIT #2: CHINA HS 85 IMPORTS FROM JAPAN, SOUTH KOREA AND TAIWAN, AND SHARE OF TOTAL
Source: BNY, HS 85 represents Electrical Machinery, Equipment and Parts, etc.
Our take
We believe the bigger surprise is why China is letting the renminbi strengthen aggressively in nominal terms. Weak inflation is clearly limiting real effective exchange rate (REER) appreciation, but even so, the moves are hardly conducive to reflation efforts. Beijing has also been relatively silent on such matters. This differs from episodes in previous decades where a weak JPY caused concern as China was moving up the value chain in manufacturing. China’s trade surplus is large, but profitability and margins are thin, suggesting that exchange rate gains should be limited. Our call this year has been for REER gains in CNY, but more through inflation differentials rather than the nominal. Reality has been the opposite.
Forward Look
We see a clear strategic reason behind the tolerance for CNY strength. Official data show that imports from Japan, South Korea and Taiwan have surged, with demand for semiconductors the clear driver. Using the Harmonized System for trade classification, total imports from the three jurisdictions in the category (HS 85), which encompasses semiconductors, surged to over CNY 300bn in May alone, a near 60% y/y increase. The share of this category of imports in total imports from the same economies has hit 75%, a 20pp surge from last year. China’s strategic focus on AI is clear; having a strong exchange rate against the main producers of semiconductors clearly helps with the economics of the plan.
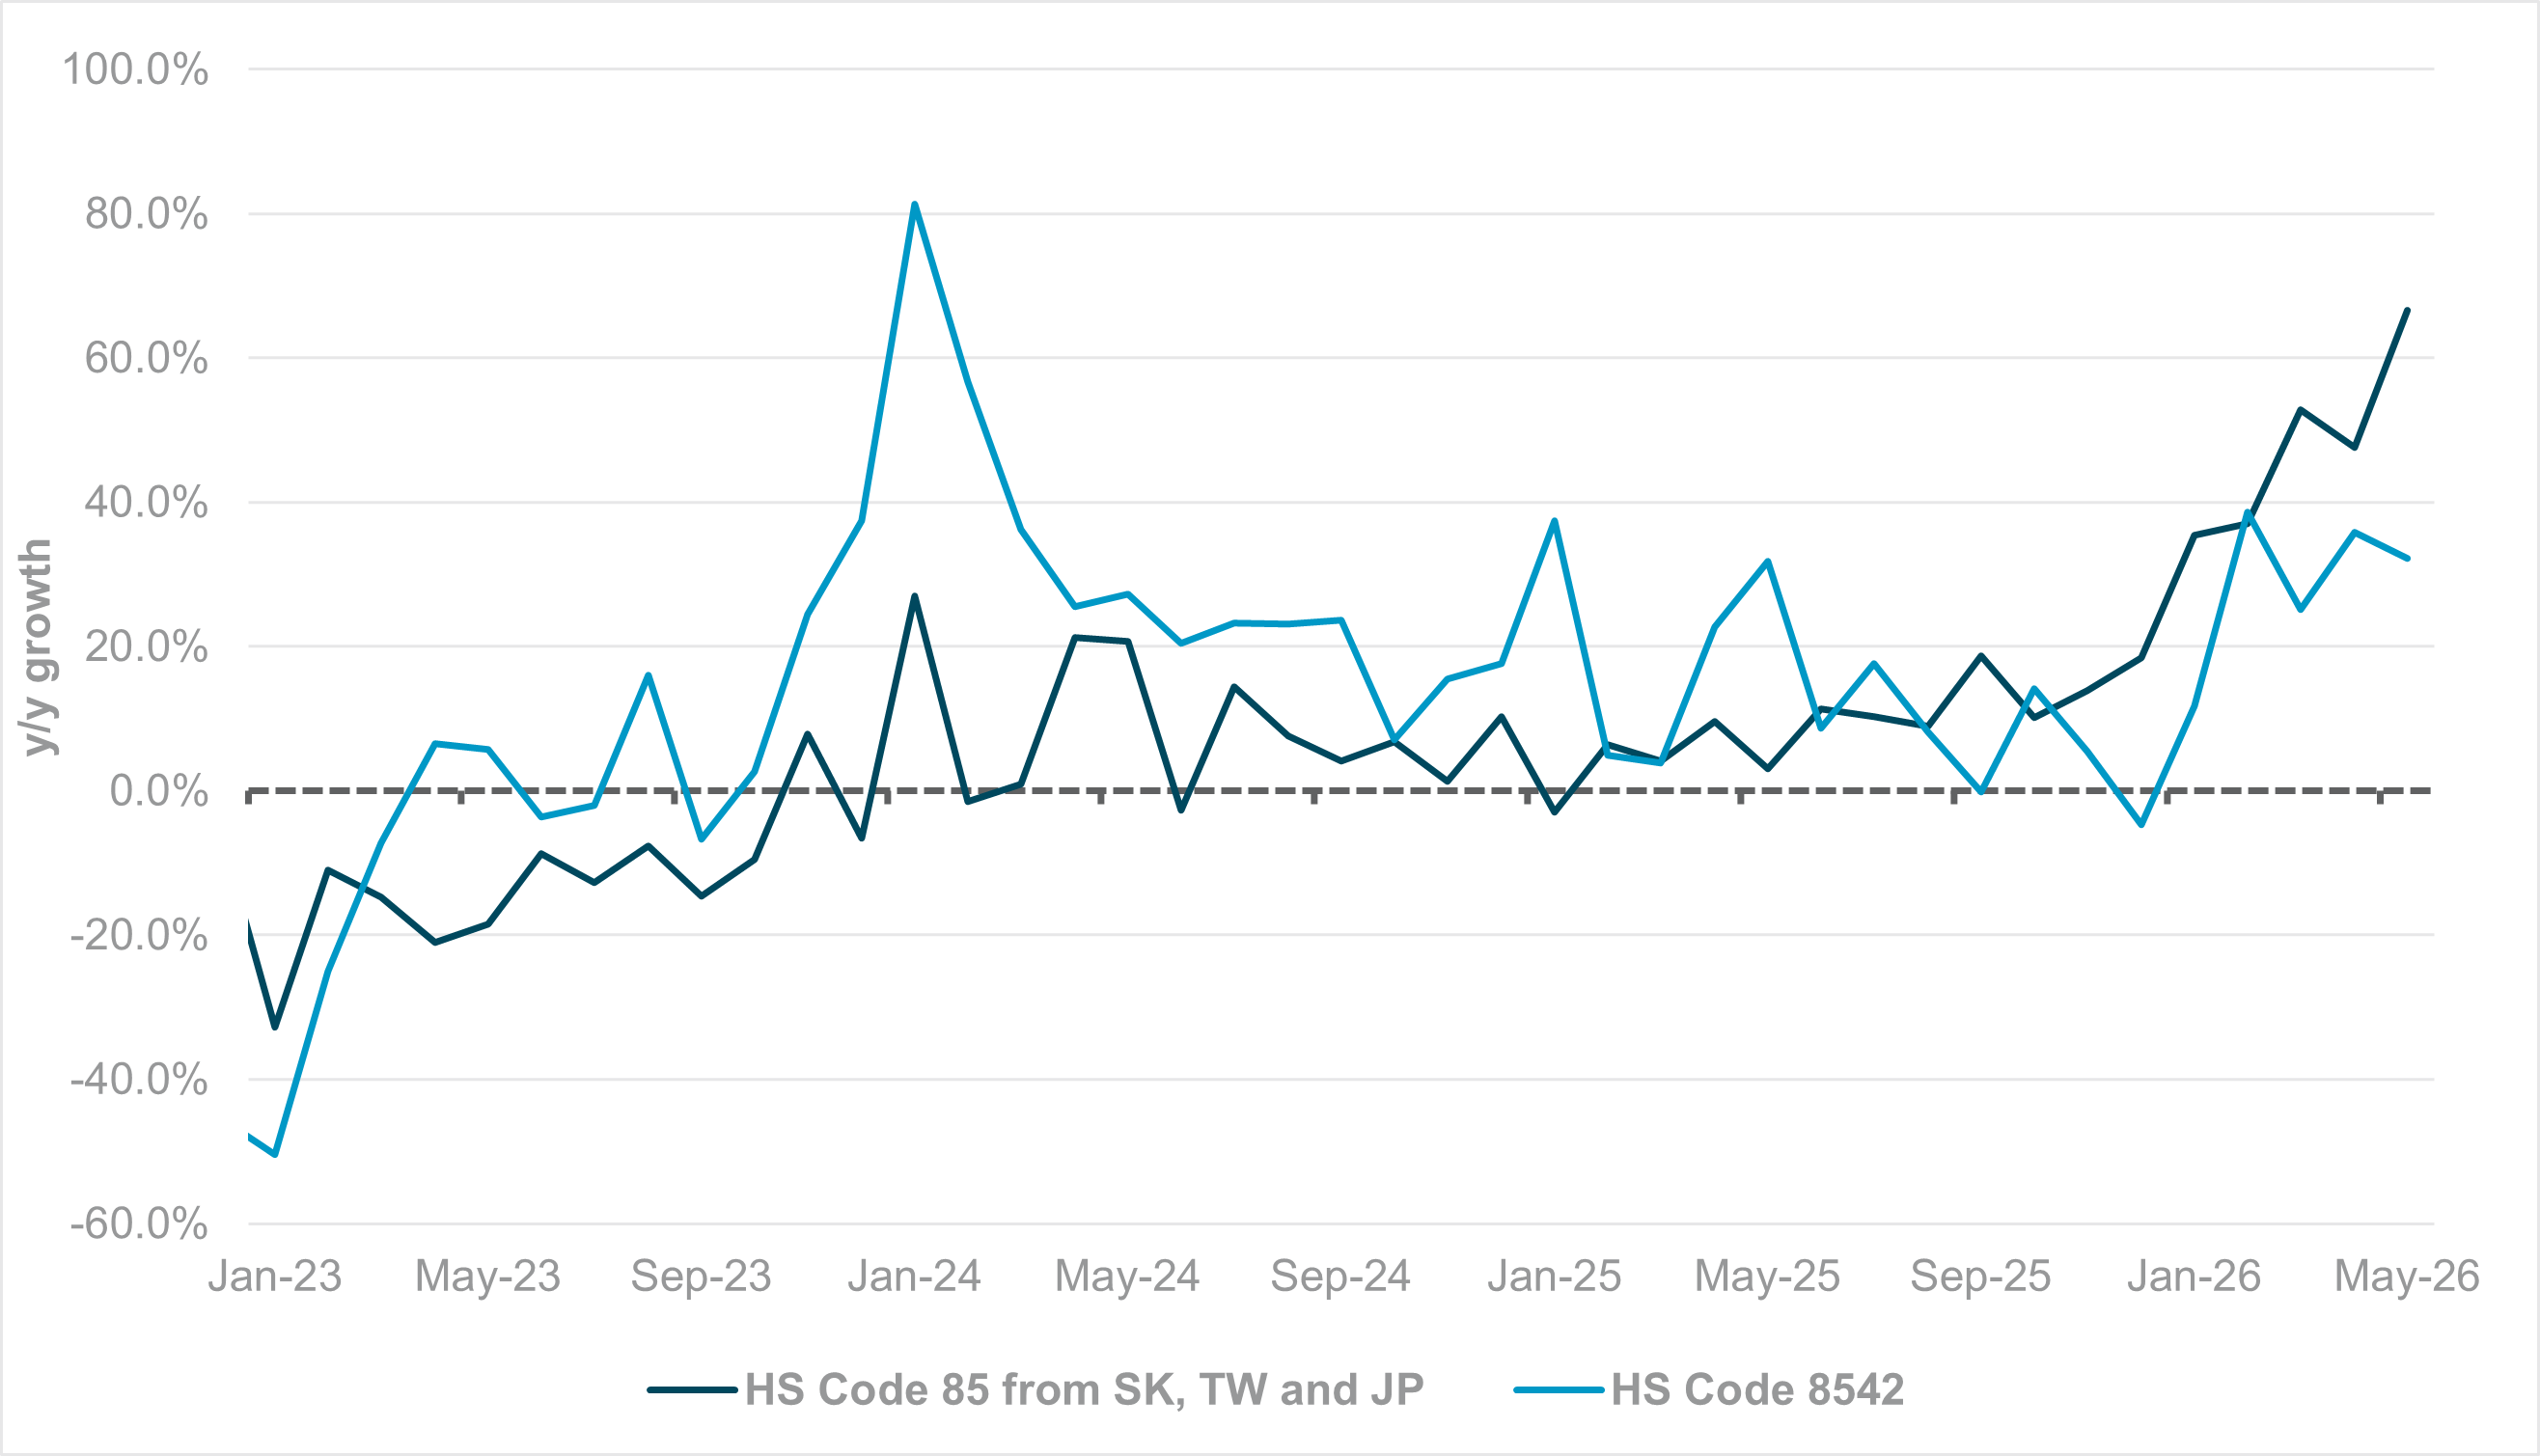
EXHIBIT #3: NA-3 ALL MACHINERY (HS 85) VS. REST OF WORLD SEMICONDUCTOR (HS 8542) EXPORTS TO CHINA, Y/Y GROWTH
Source: BNY, 8542 represents Electronic Integrated Circuits
Our take
Strategic competition on AI will be one of the defining geoeconomic themes over the coming years, and the scramble for chips is being felt globally. While China is increasing self-sufficiency, in the near term there is no sign of any slowdown in demand. Efforts to restrict access have not had any impact on import growth from the region’s top producers in value terms. Chinese imports of electronic integrated circuits (HS 8542) from the rest of the world are also strong but not increasing.
Forward look
The cost component is playing a role as well due to supply shortages in memory and storage chips, so the volume element is likely lower than what value numbers indicate. In the near term, Chinese importers will have to pay more, like any global customer, but this is where having a strong currency helps in a supply crunch. We expect the renminbi to arrest its gains versus NA-3 currencies once these pressures ease, and there may be a strong case for CNY to weaken when China’s own production is ready to challenge current dominant exporters.
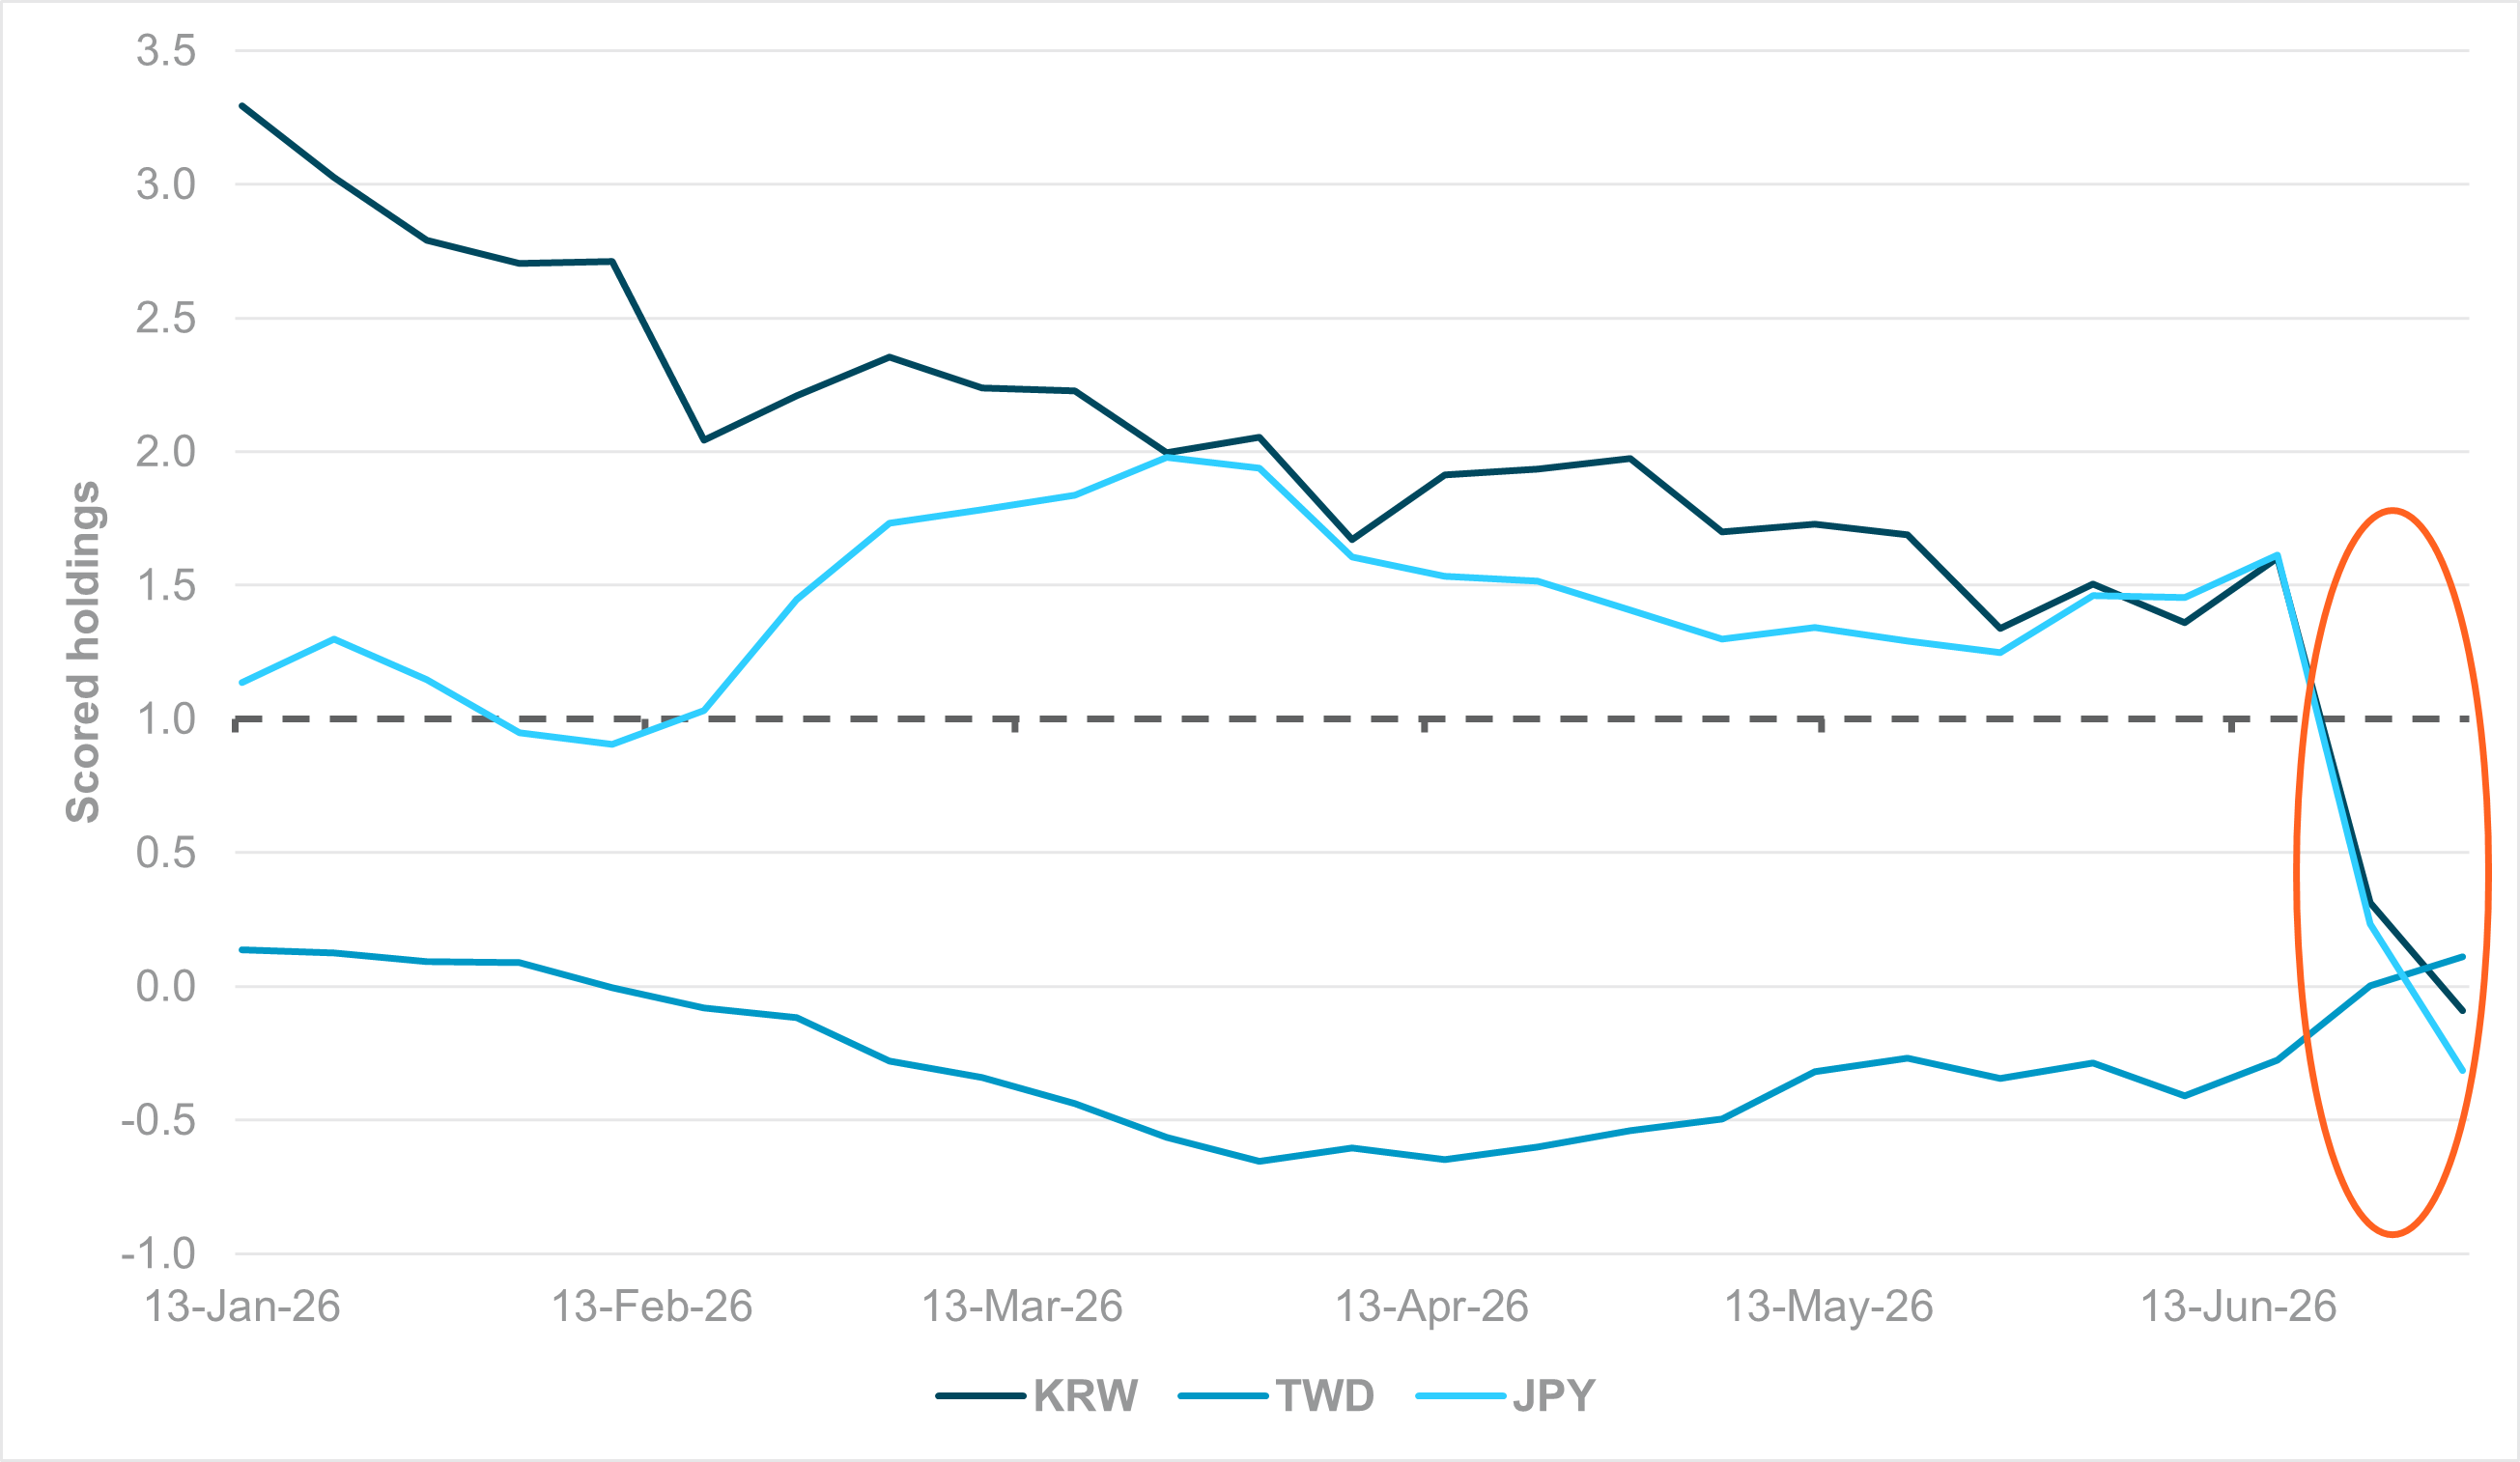
EXHIBIT #4: SCORED HOLDINGS, JPY, KRW AND TWD
Source: BNY
Our take
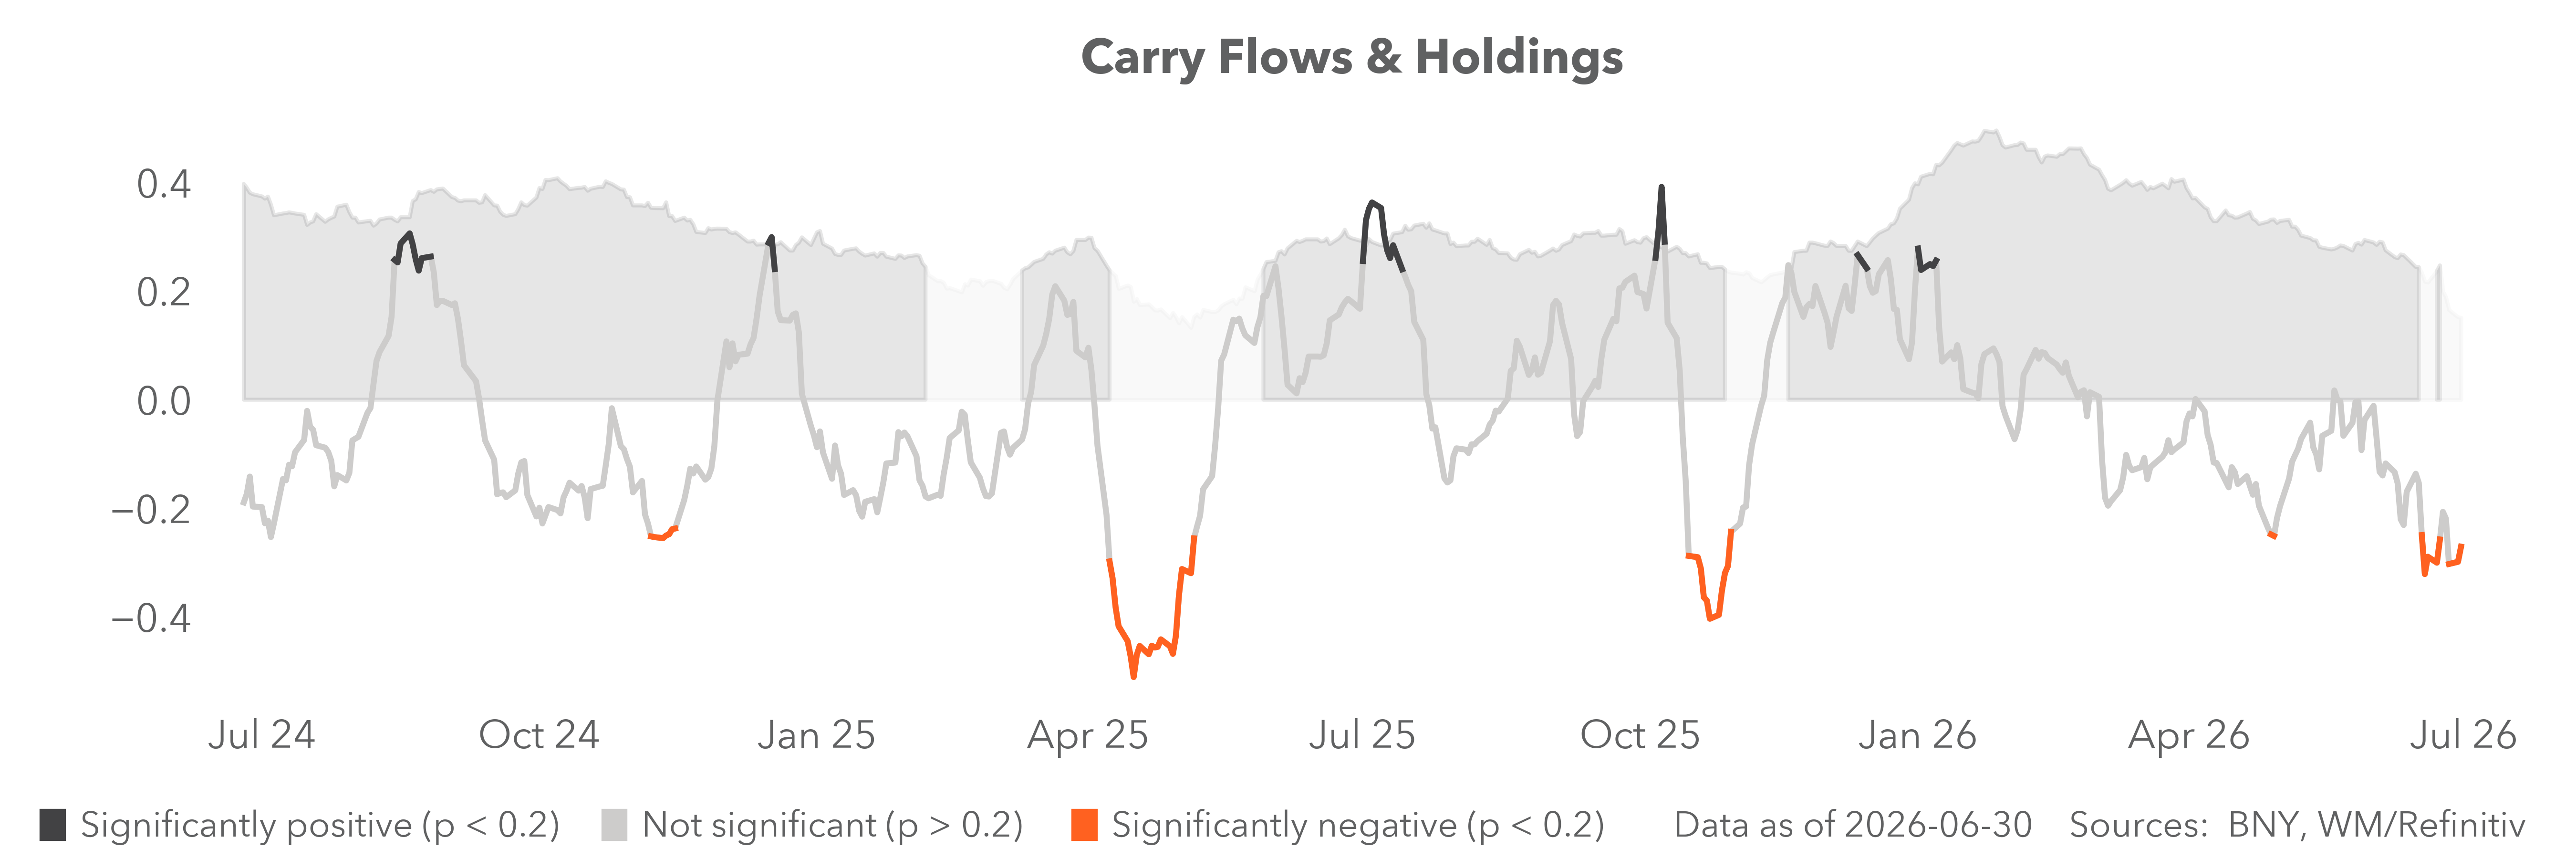
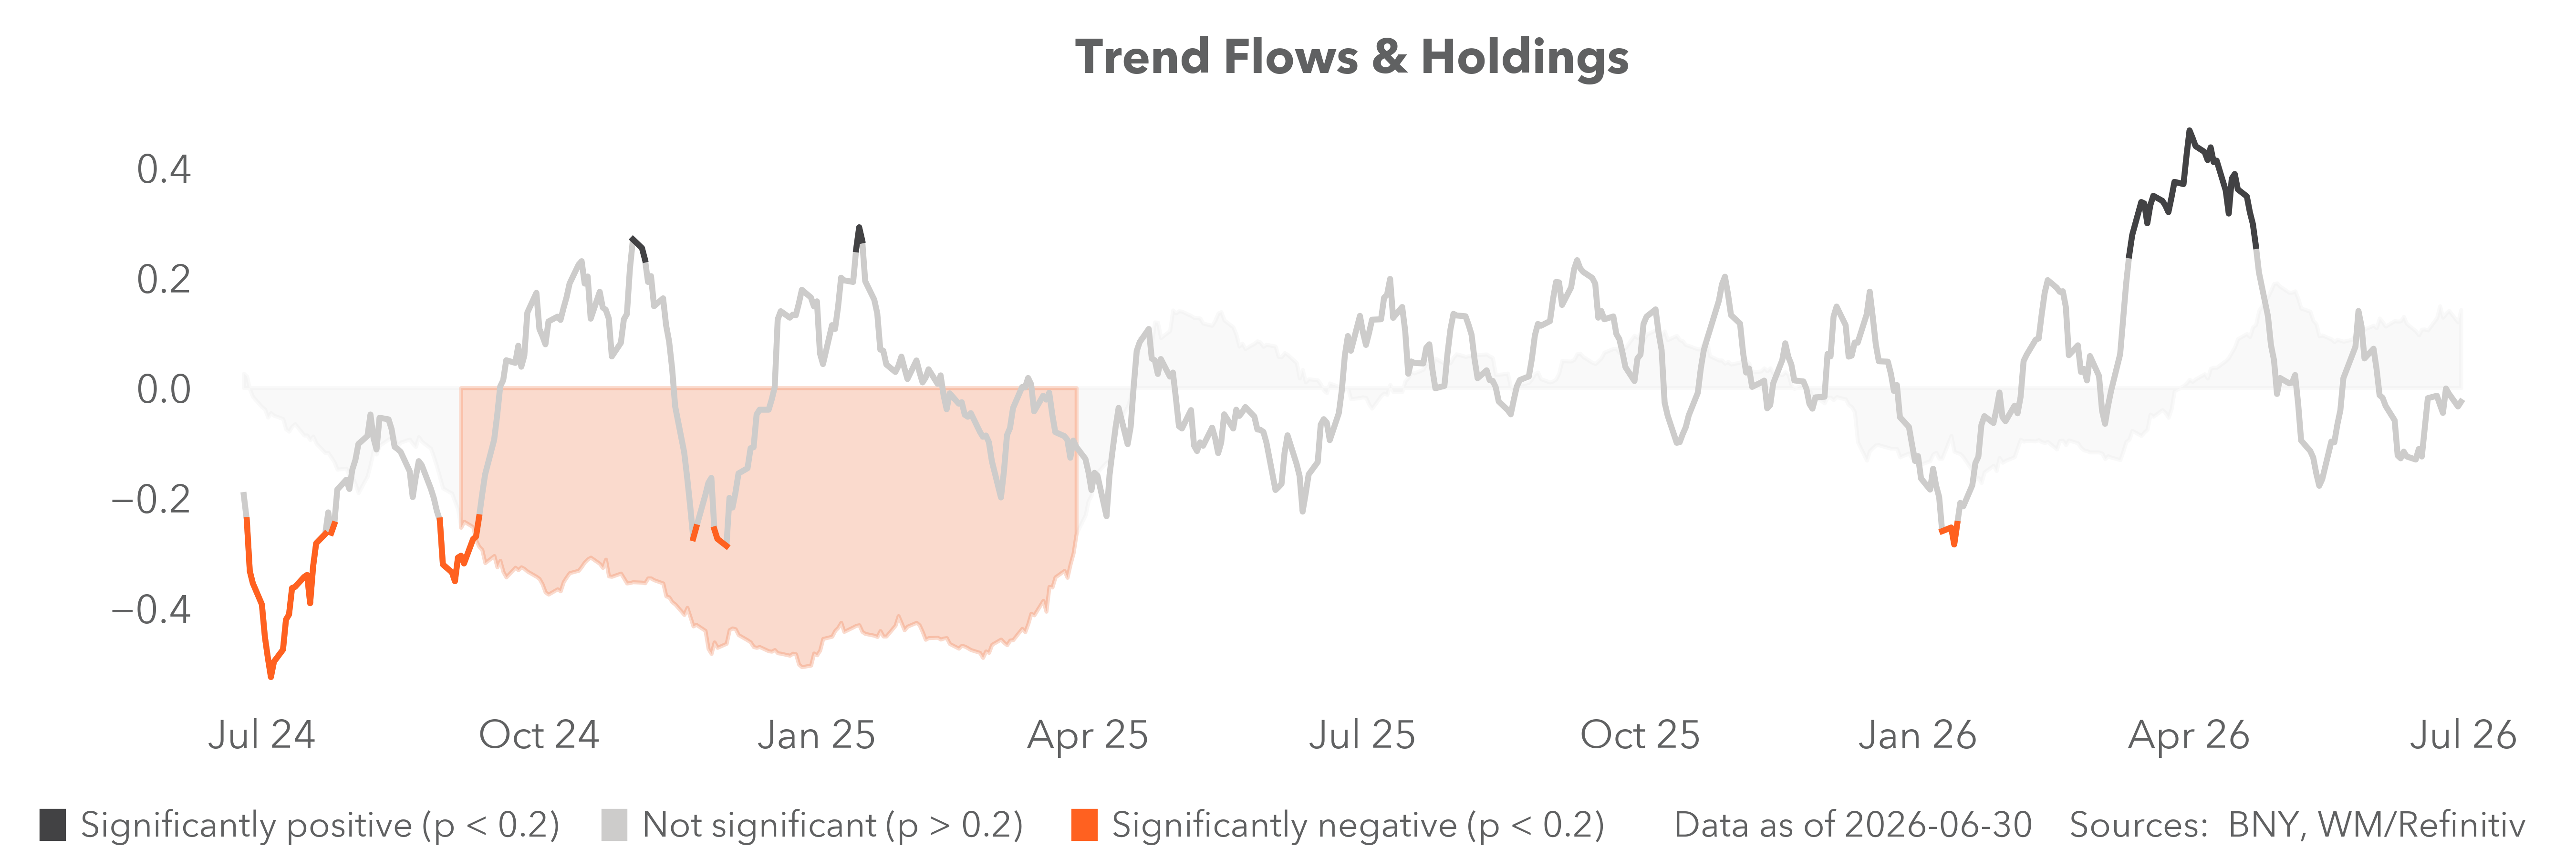
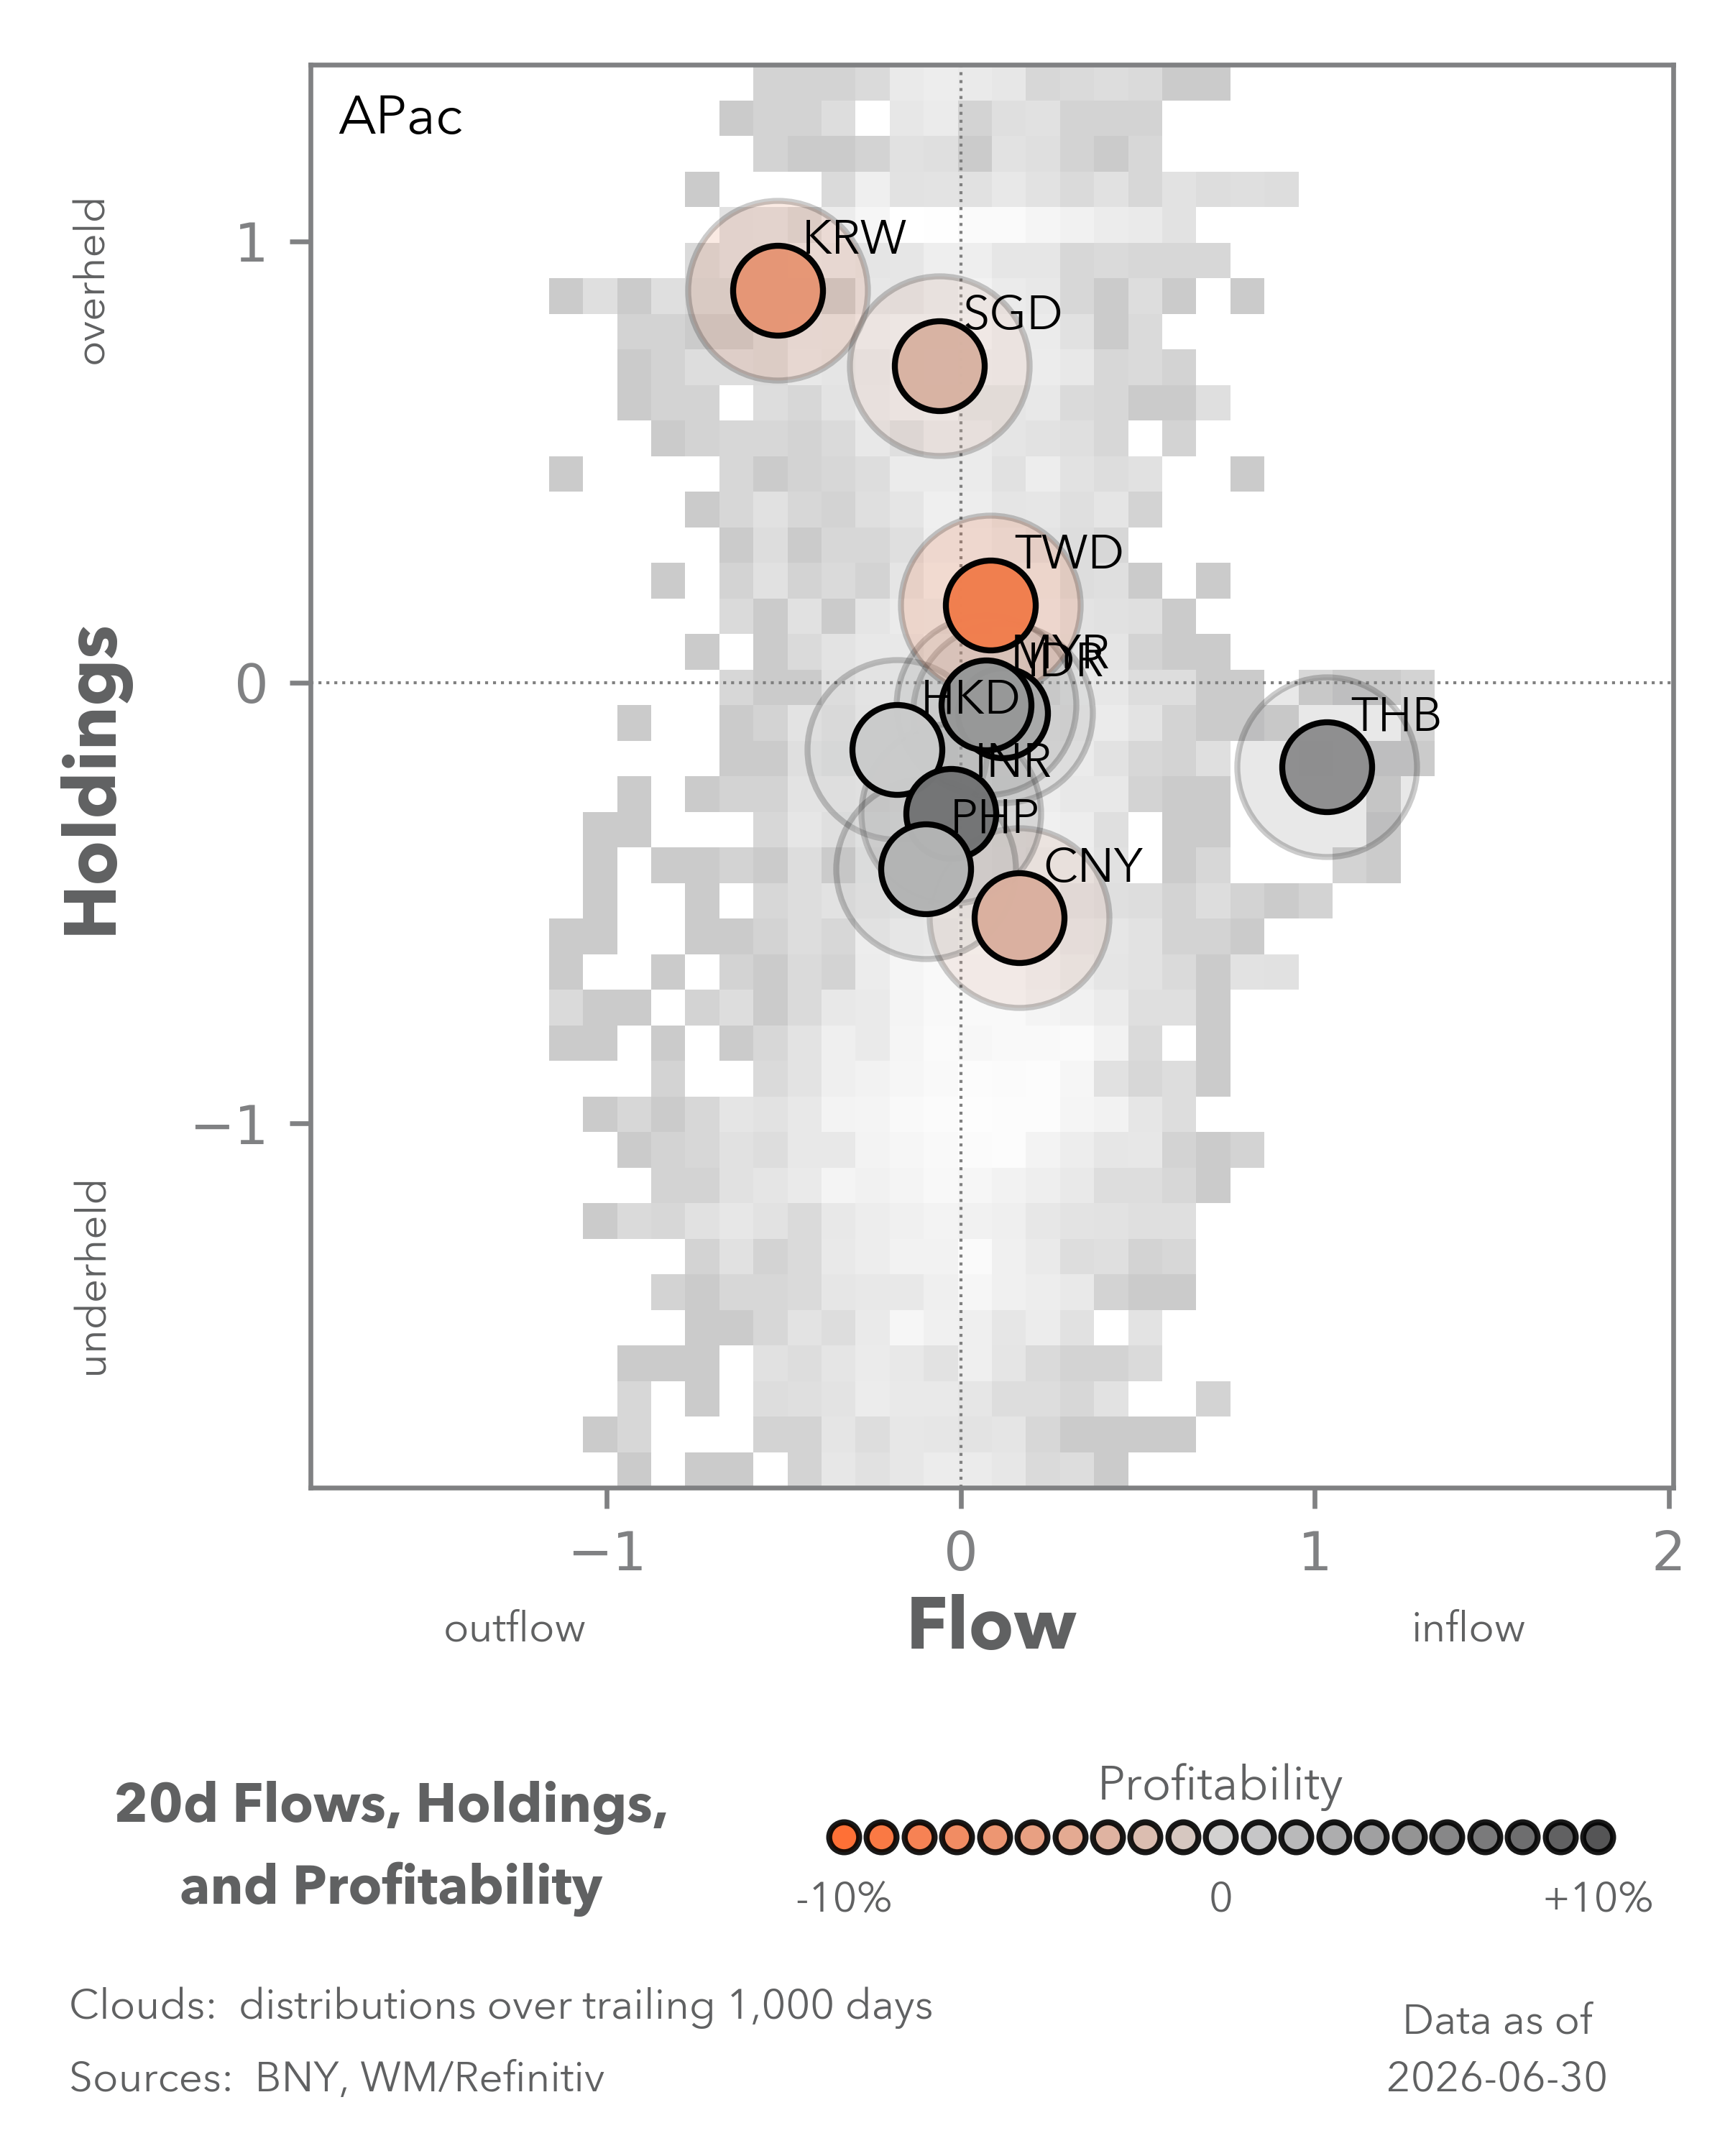
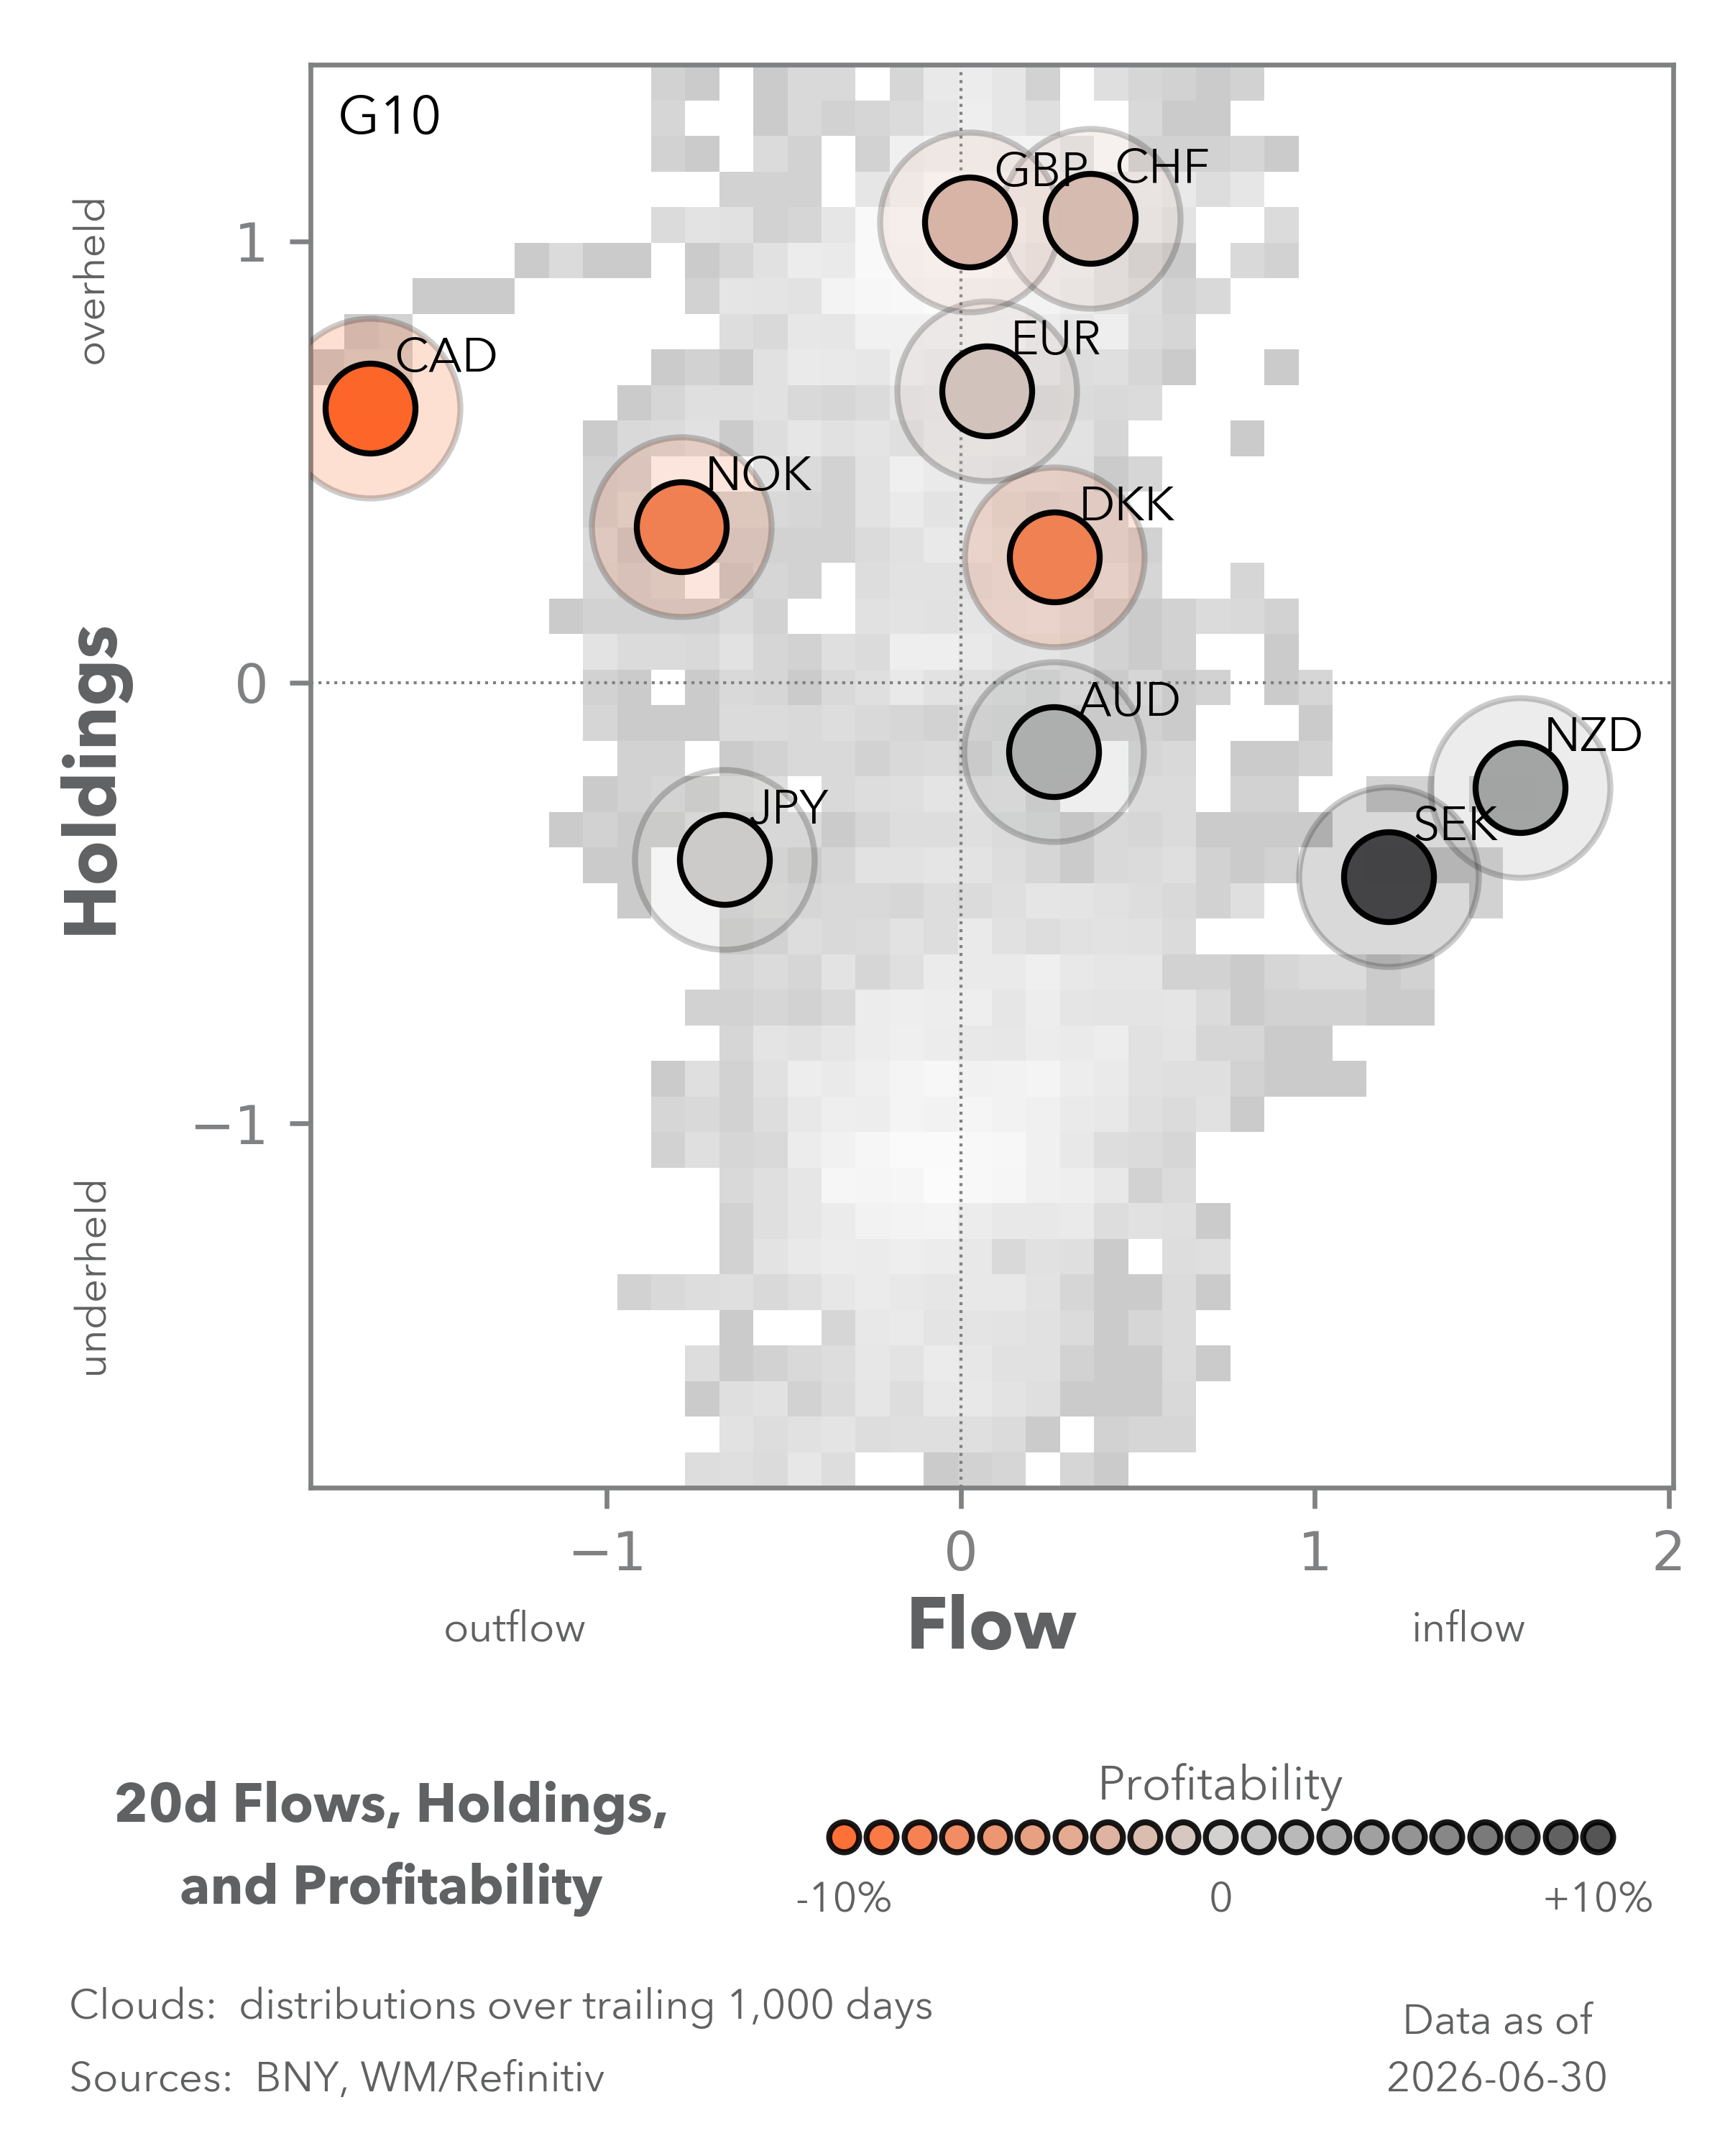
China’s silence on JPY, KRW and TWD valuations is as surprising as the lack of U.S. pushback. Although Treasury Secretary Scott Bessent highlighted in January that the KRW wasn’t trading in line with fundamentals, the KRW has weakened further but hasn’t generated much pushback. The decline in oil prices means the fundamental justification from a balance-of-payments perspective is also much weaker. iFlow indicates that any residual positioning in JPY and KRW longs by cross-border clients has collapsed (Exhibit 4). Intervention clearly isn’t designed to strengthen currencies structurally, while potential rate hikes by central banks in the region will also be soft relative to developed market peers outside of Asia. Fed Chair Kevin Warsh’s comments yesterday weren’t seen as excessively hawkish, so the USD carry angle is weakening as well as a driver.
Forward look
If the U.S. can’t make an argument for USD to adjust versus JPY, KRW and TWD on a fundamentals basis, geopolitics and strategy could be the more relevant angle. Current weakness in these currencies versus the USD and CNY is dampening the cost of purchases. The U.S. may take a view on whether this aligns with strategic priorities in AI. A new push, either openly or behind the scenes, could change behavior, especially with JPY and KRW where markets are now positioned the other way. This means that a sudden adjustment could pay off in material strength for JPY, KRW and TWD. Signaling through the semiannual currency report is another option. Either way, something needs to give.