Rate hikes alone won't anchor inflation expectations
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.

Geoff Yu
Time to Read: 4 minutes
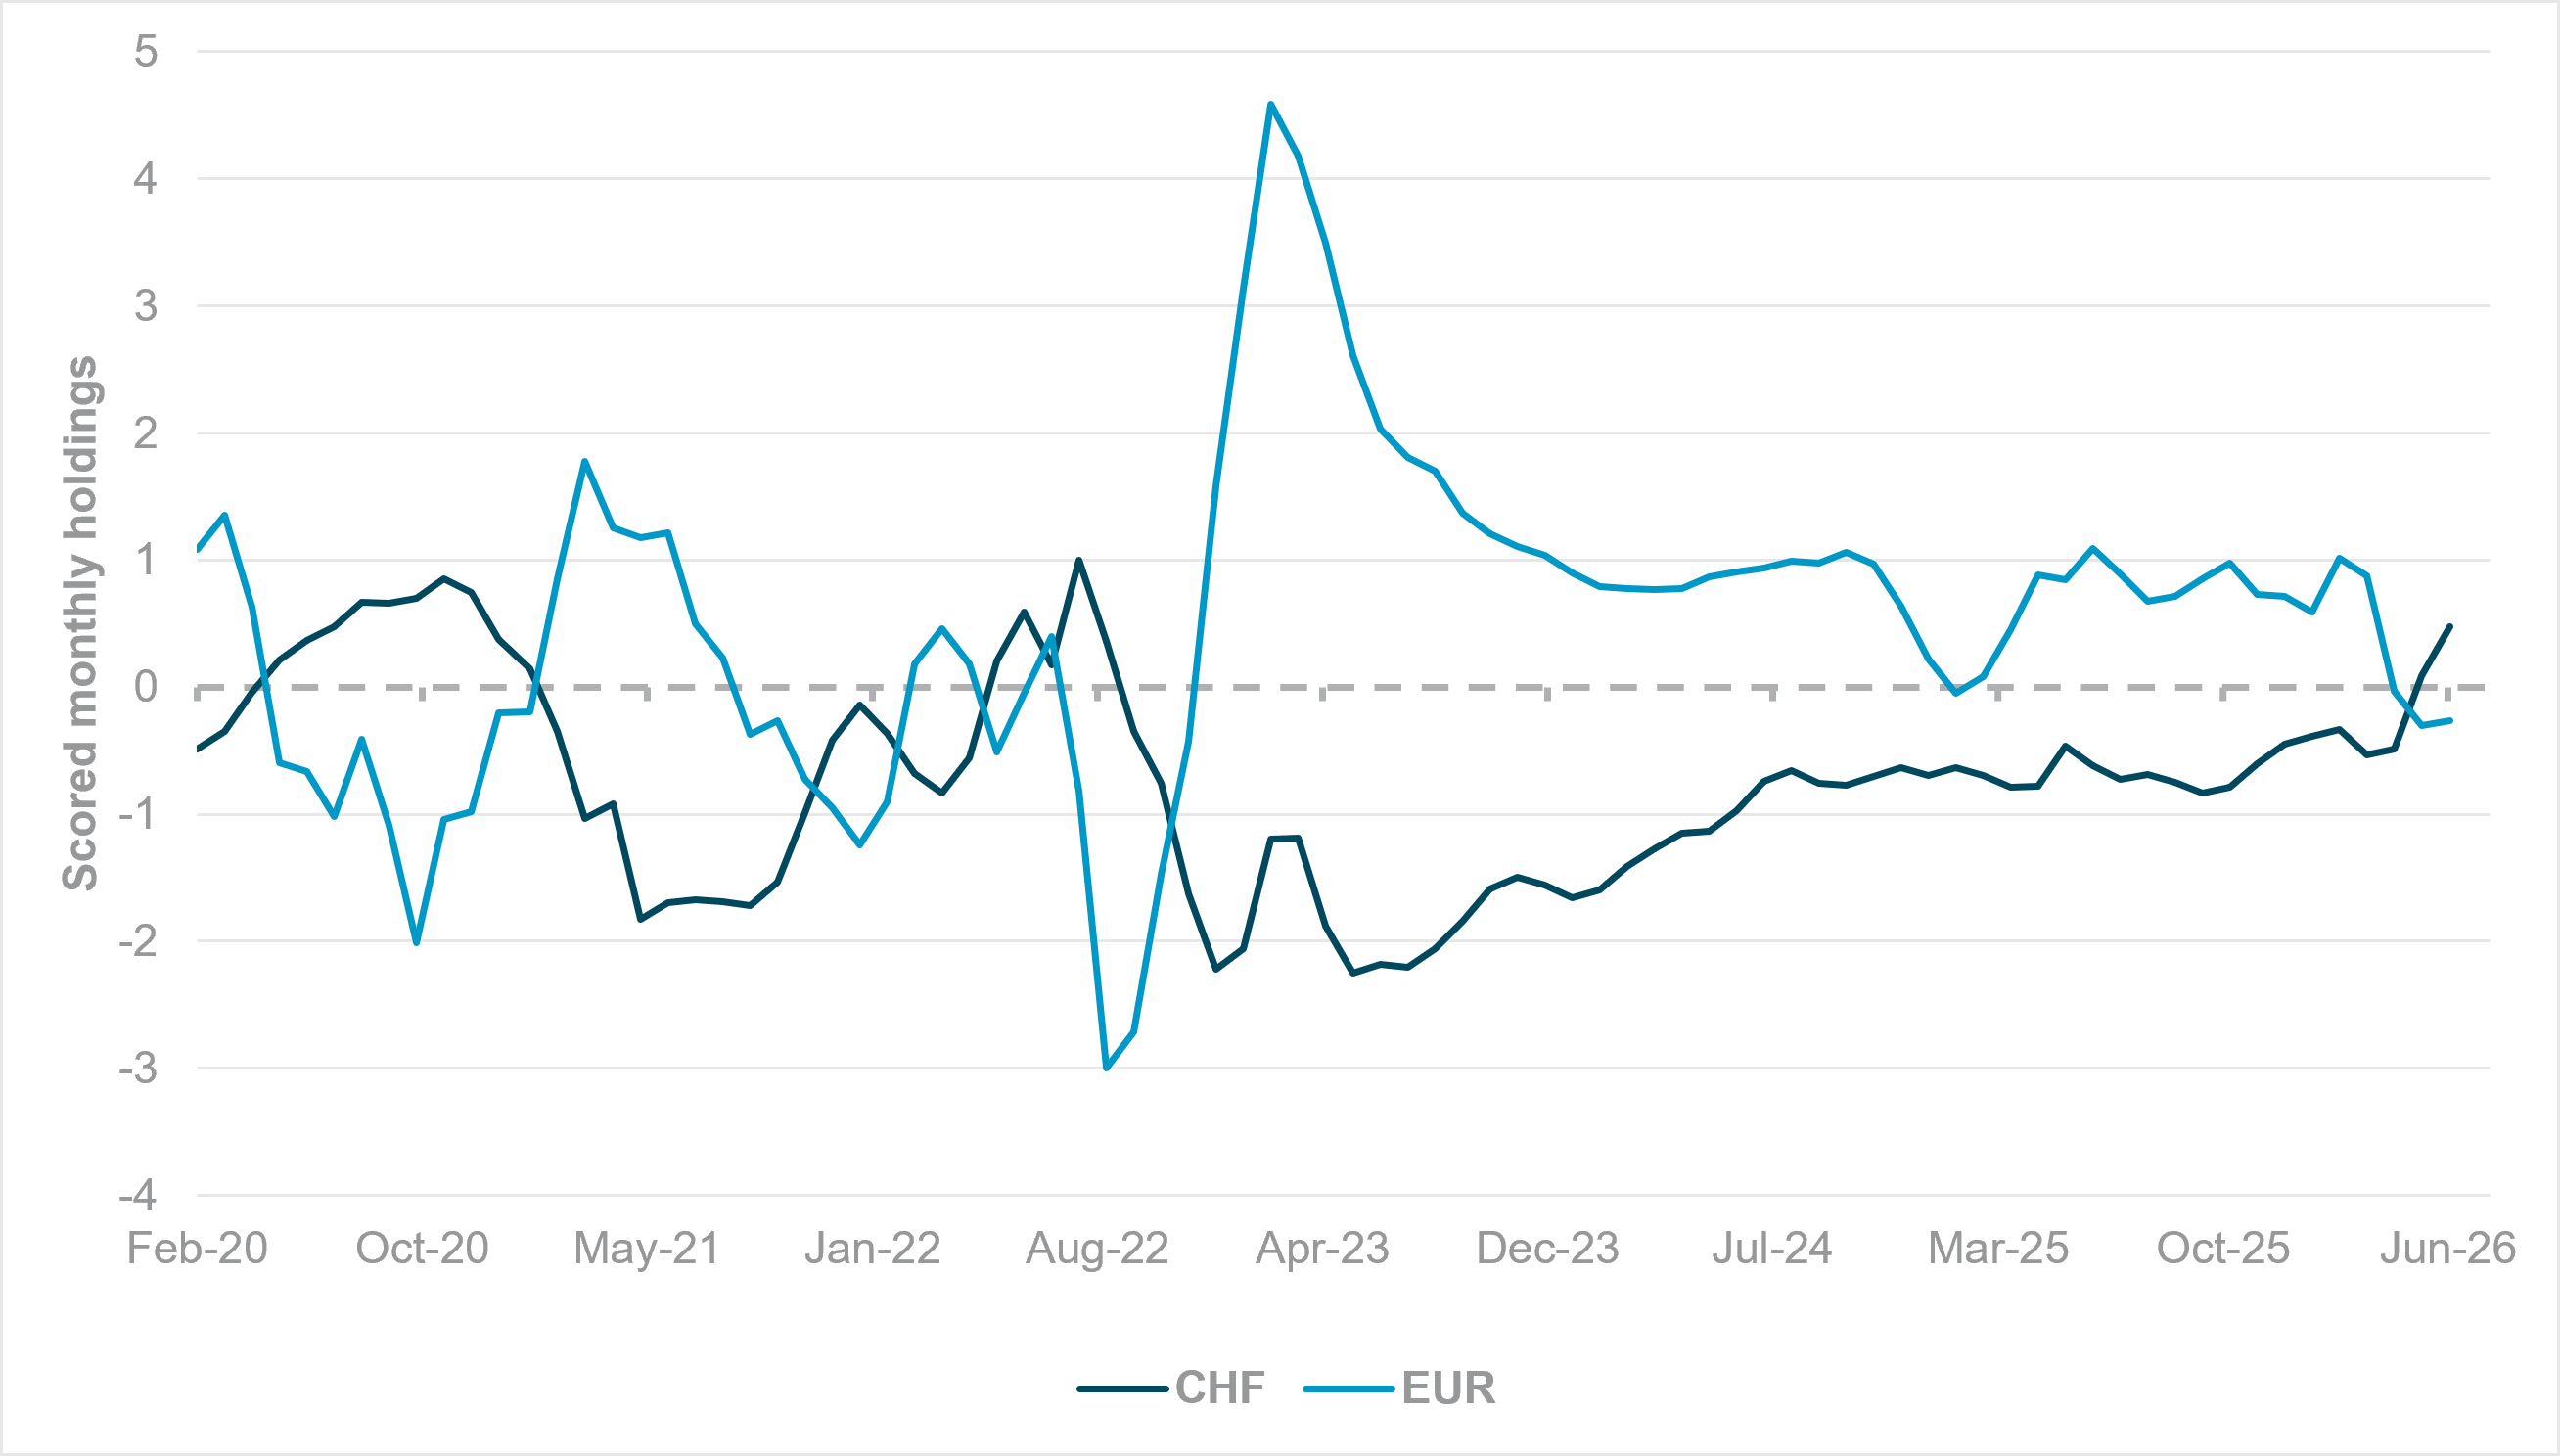
EXHIBIT #1: CHF HOLDINGS VS. EUR AGGREGATE HOLDINGS, 2020 TO PRESENT
Source: BNY
Our take
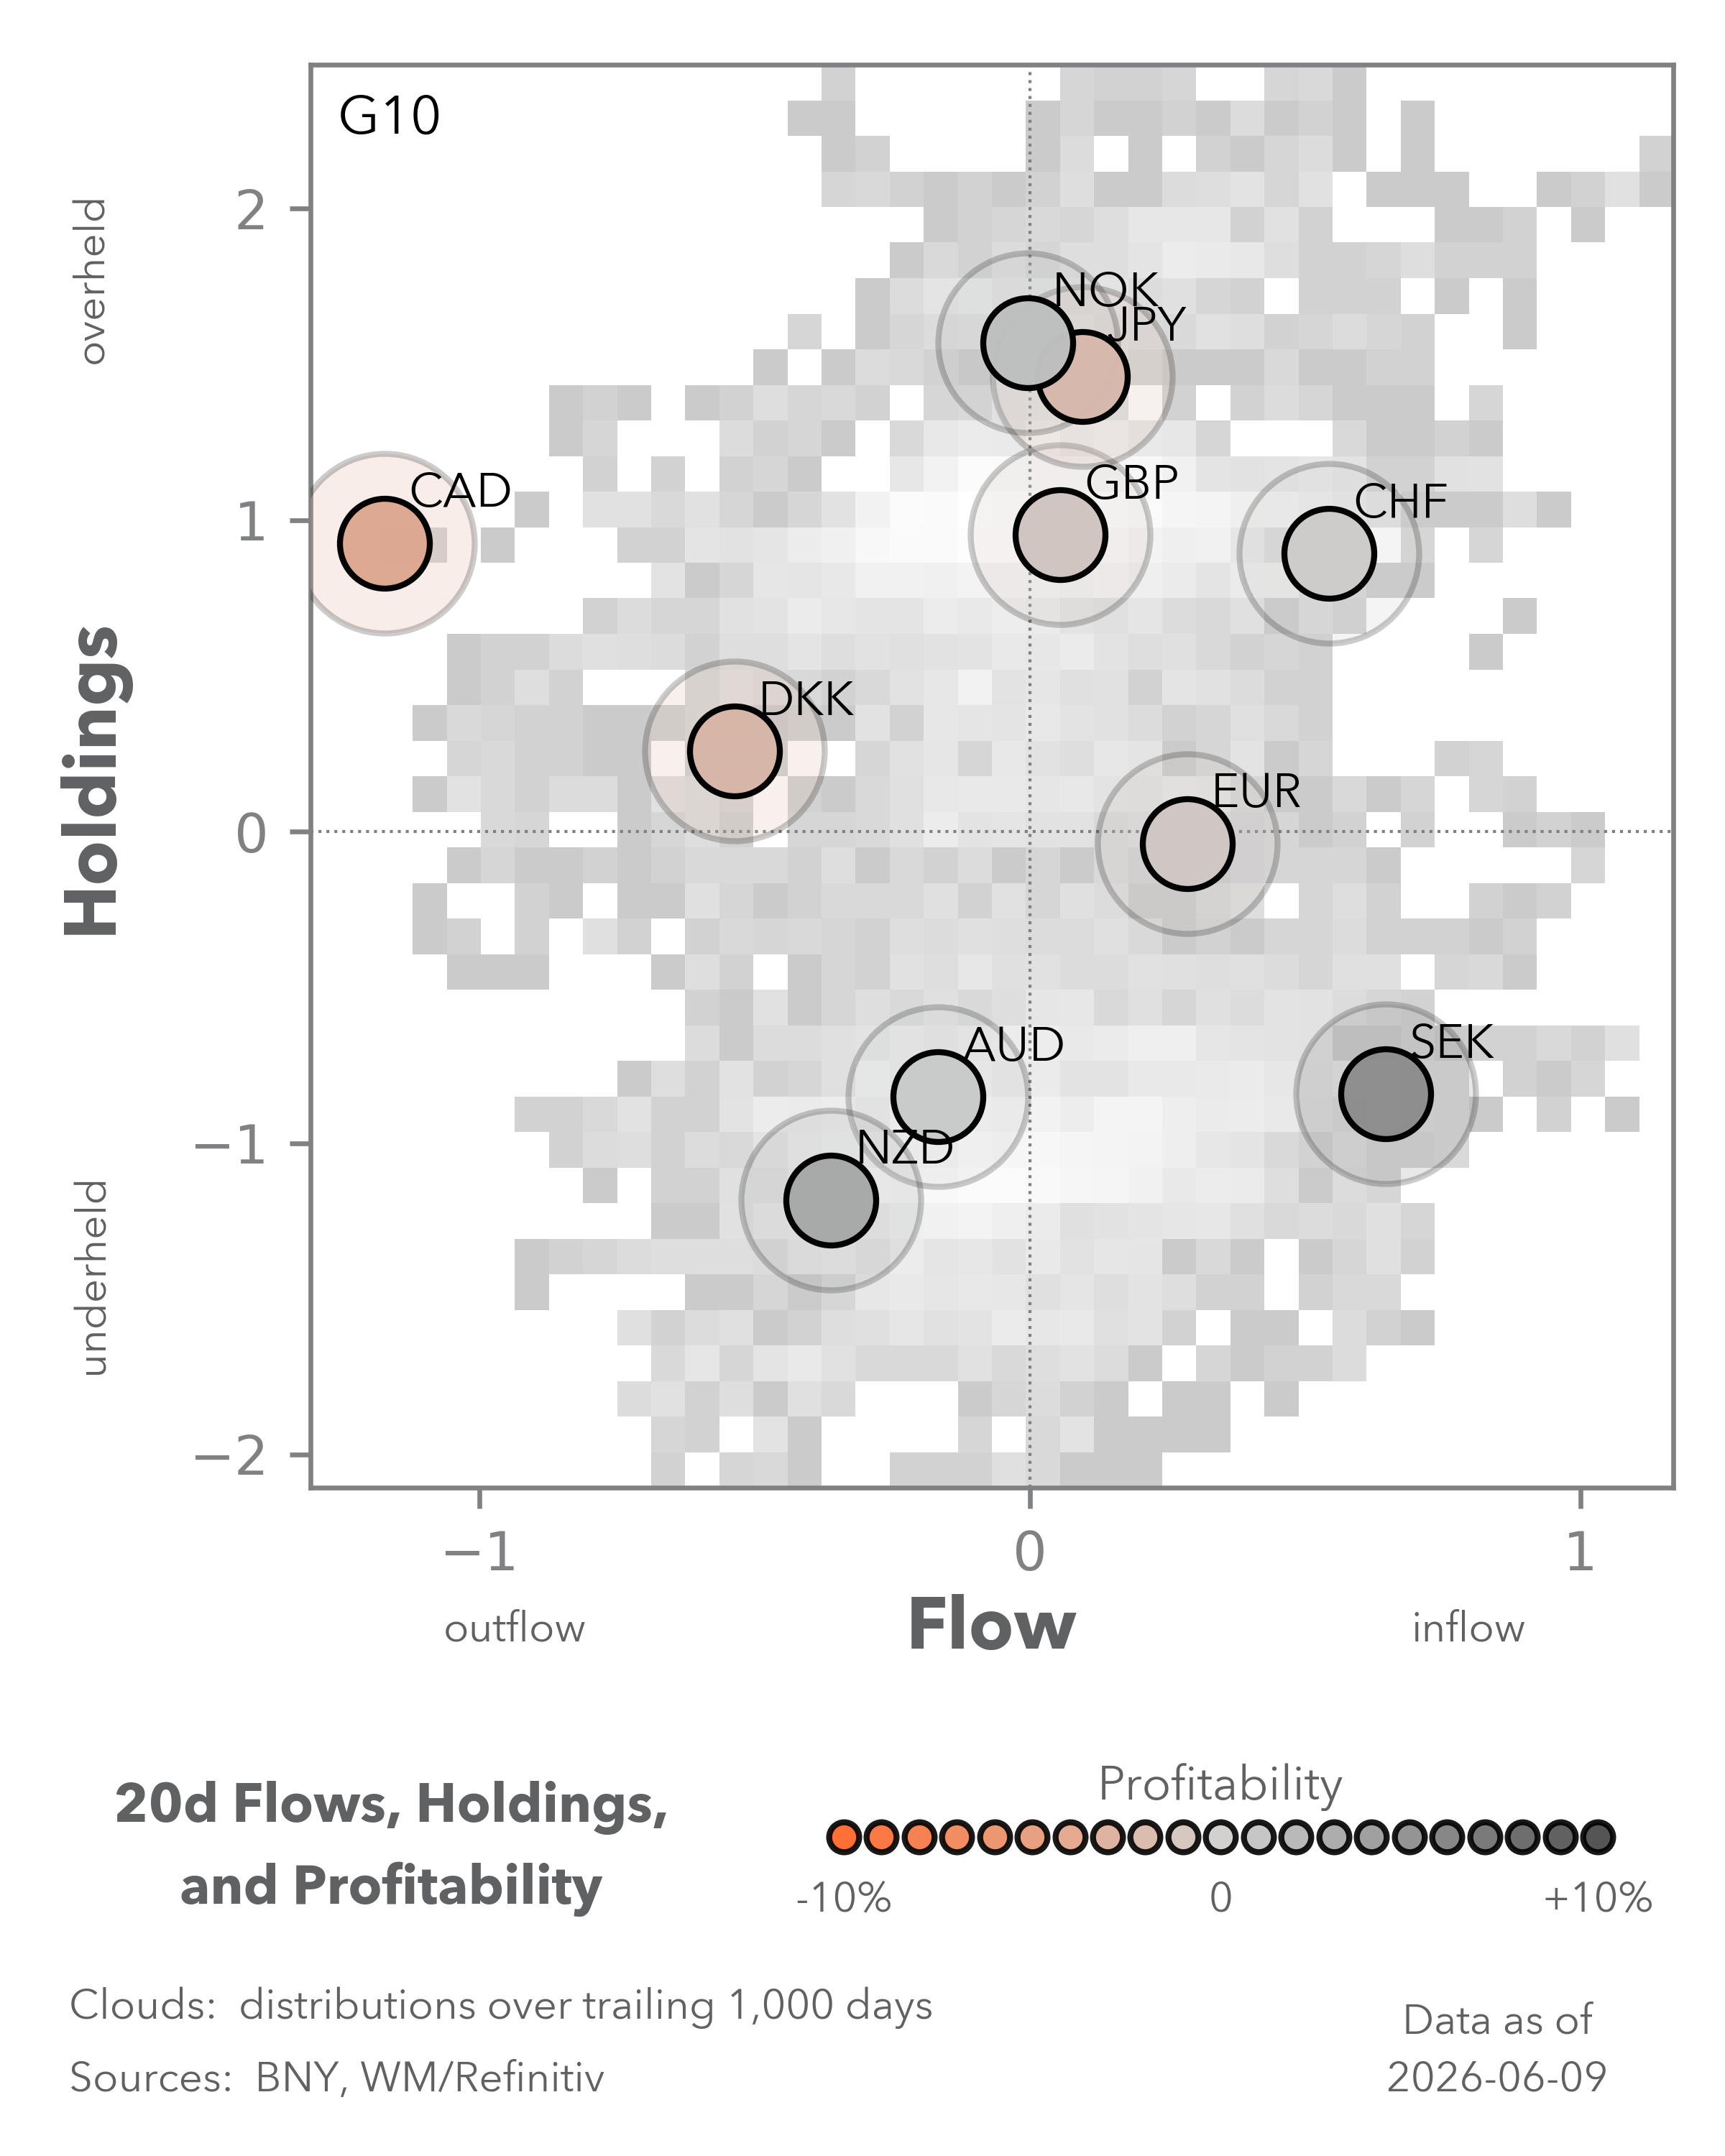
As a generally zero- or even negative-yielding currency, the franc is rarely in an overheld position due to carry loss. There is passive hedging in place by CHF-denominated investors, but beyond regulatory mandates, we doubt such purchases are strongly encouraged – they conflict with the SNB’s general approach of deterring CHF purchases in normal times. Hence, when CHF moves into overheld territory on a standalone basis and is even better held than EUR (Exhibit 1), circumstances must be “abnormal.” The last time this took place was when the SNB moved ahead of the ECB during the normalization process in June 2022, and it appears that the market wants to position for at least the risk of a similar scenario. With the ECB moving toward a rate hike, circumstances are still very different, and there’s little chance the SNB can suddenly shift course. Headline inflation continues to run at relatively “normal” levels on a sequential basis, while Q1 GDP (sports-adjusted) surprised to the downside. There’s simply no demand-driven inflation impulse; if anything, the ECB’s hike will further slow demand among Switzerland’s key trading partners, and the SNB may even view hawkish policy as a risk to Swiss growth.
Forward Look
Fundamentally, we continue to see a glaring inconsistency in how the market actually “prices” SNB policy. Interest rate futures still point to a 60% chance of a 25bp hike by the end of the year, perhaps in sympathy with the ECB, which is signaling a hawkish tilt. Despite current ECB guidance on rate hikes (which we expect to change as the Eurozone economy slows), options markets still point to marginally lower EURCHF via risk-reversals. This reflects the franc’s safe-haven status and structurally low inflation that supports real rates. Whatever the SNB’s own messaging, which we see as internally consistent, rate markets and FX options continue to point in opposite directions. If the SNB were truly worried about inflation, especially from external supply factors, there would be much greater tolerance of currency strength rather than an “increased willingness” to intervene. Ultimately, it comes down to the conditional inflation forecasts. Barring an unprecedented upward revision of CPI – from barely 0.8% y/y to close to the 2.0% y/y target through the forecast horizon to early 2029 – there’s no need to change their stance. We would also keep an eye on the Swiss Population Cap referendum, as its passage will have material implications for Swiss–EU relations in the long term.
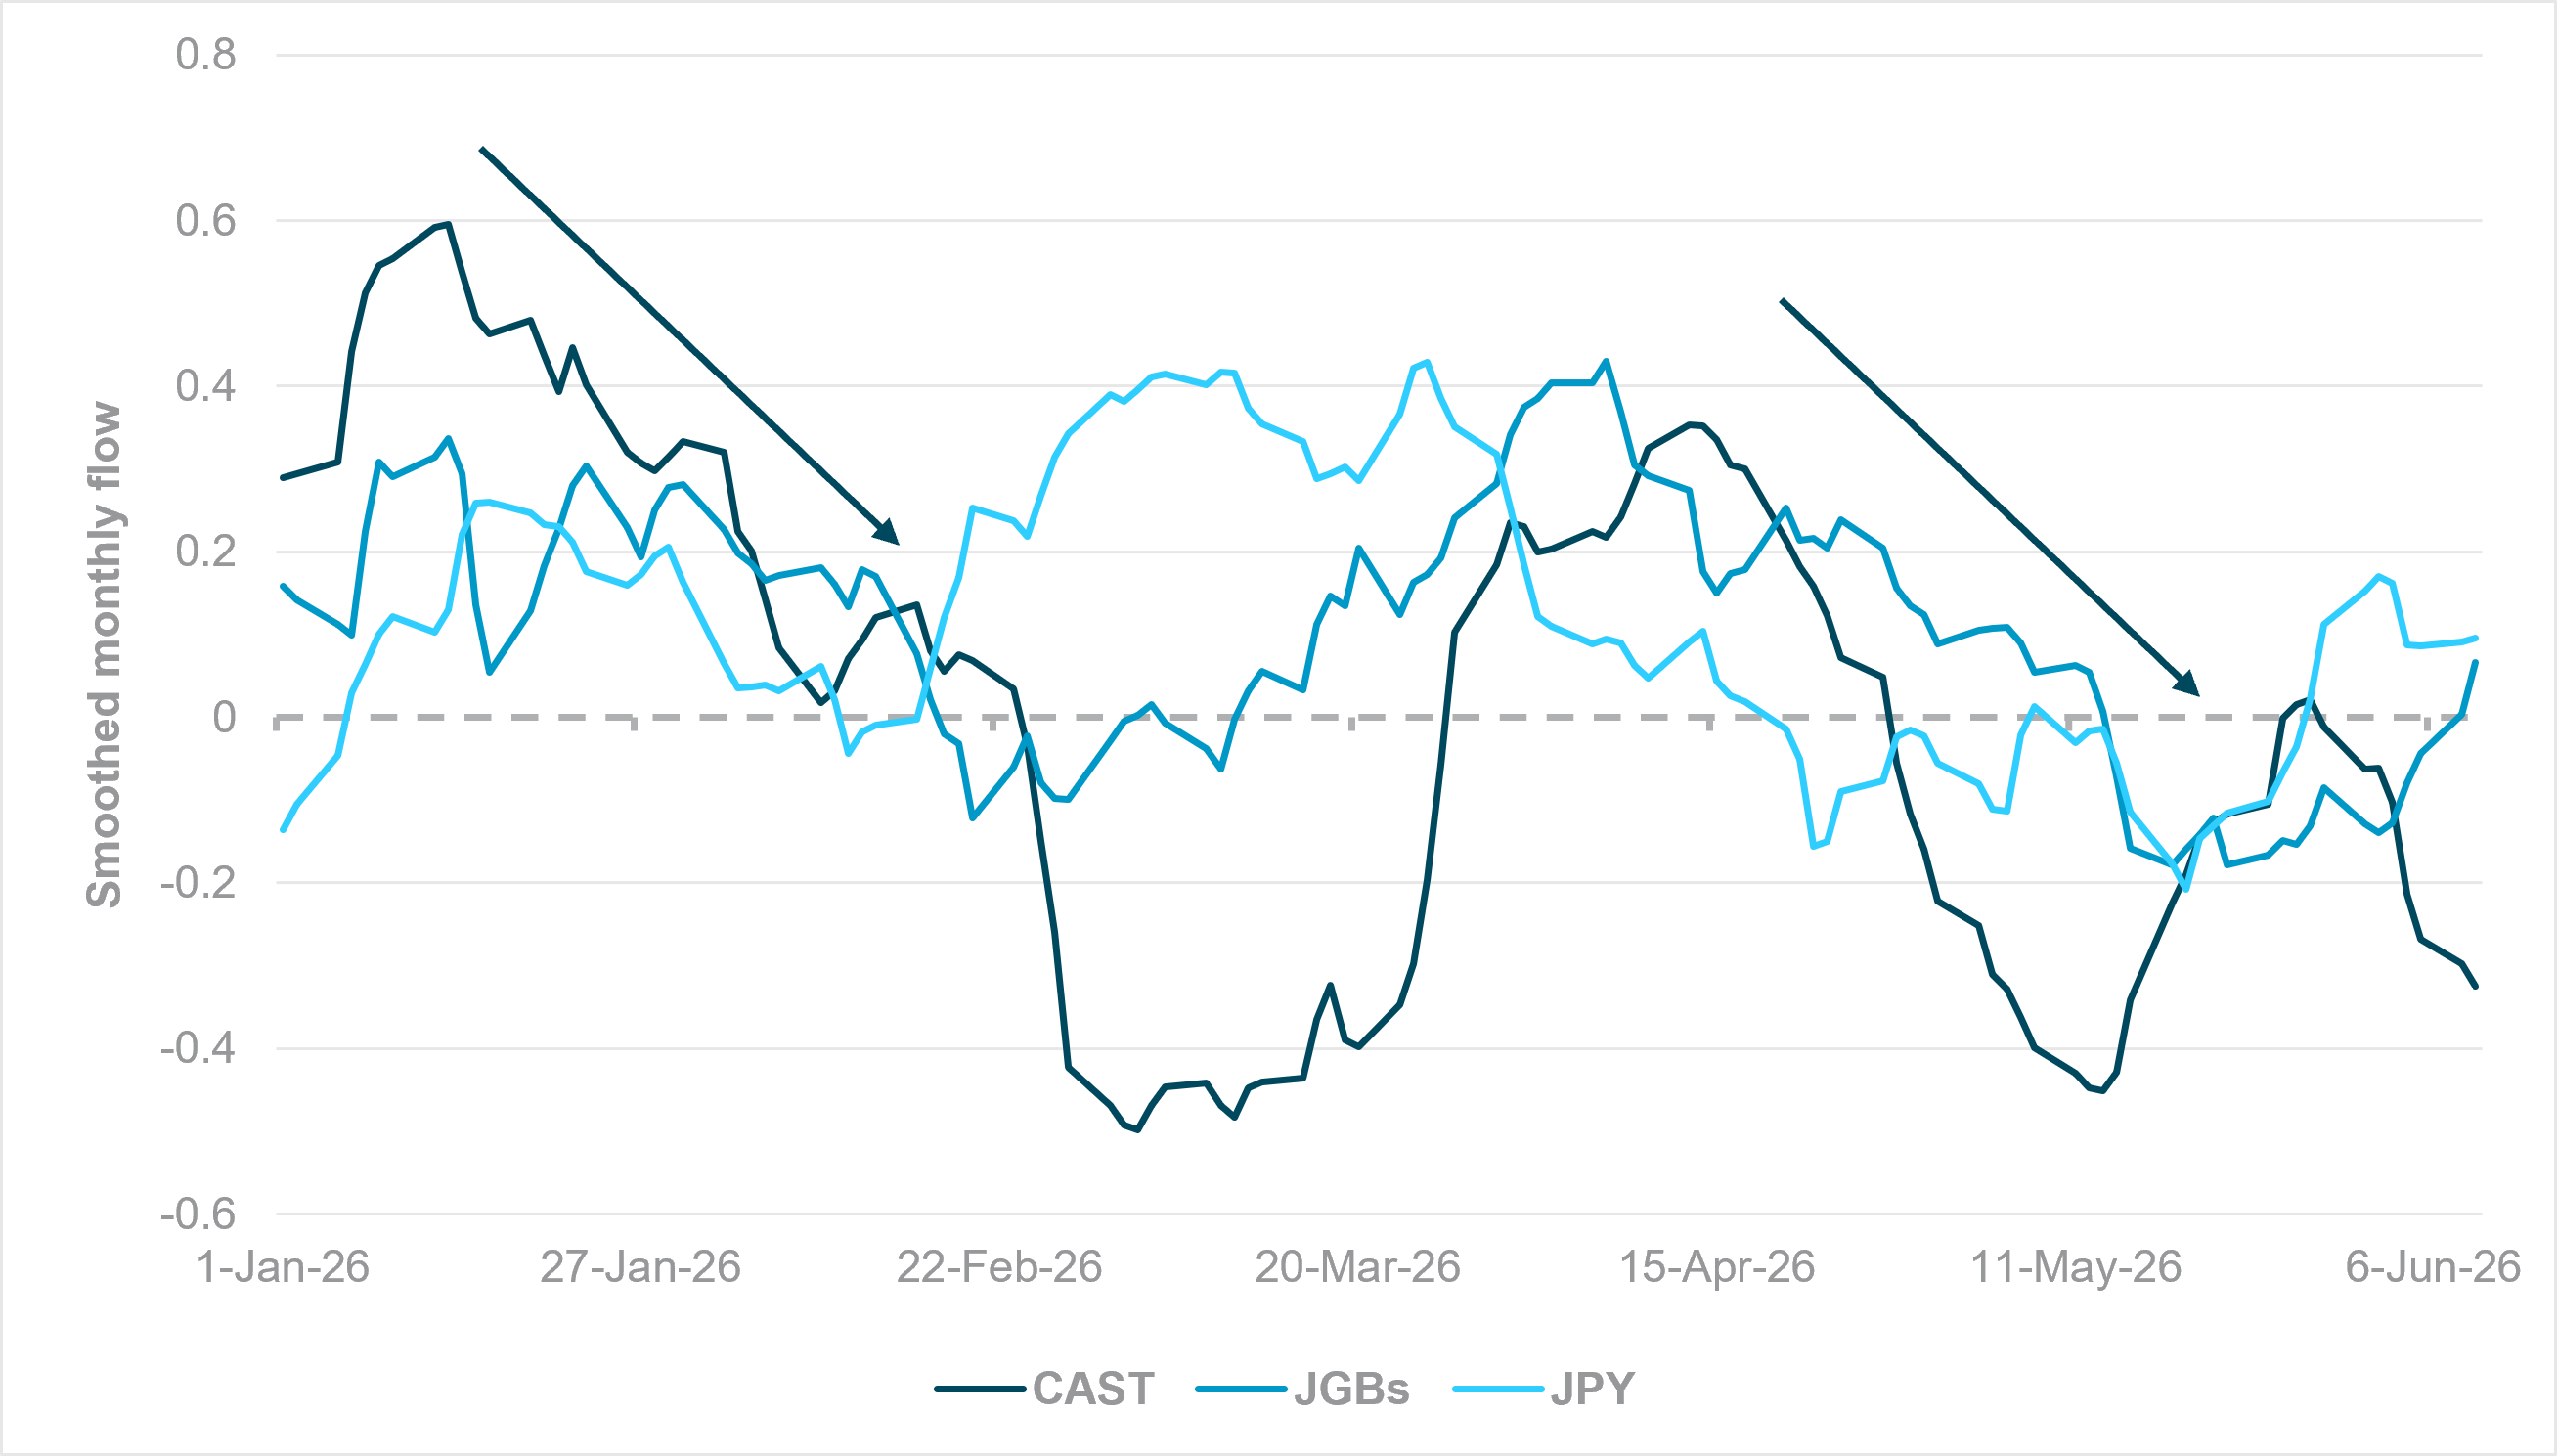
EXHIBIT #2: FLOWS IN JAPANESE CASH AND SHORT-TERM INSTRUMENTS, JGBS AND JPY
Source: BNY
Our take
Six weeks after a “final warning” against FX markets in USDJPY, the key 160.00 level is being breached without much incident, and the reaction from Japanese authorities has been relatively muted. Moderate Bank of Japan (BOJ) tightening and a steady drift higher in nominal yields is seen as sufficient for now. But that could change if the Federal Reserve outlook is repriced – even a marginally hawkish FOMC result next week could negate what the BOJ delivers. Meanwhile, our flows indicate that there is ongoing deterioration in asset flows by cross-border investors. Around mid-May, Japanese government bonds (JGBs), the JPY and cash-equivalent instruments were all net sold for the first time this year (Exhibit 2). This was hardly reassuring for authorities trying to stabilize the JPY amid currency pressures across the region’s net-energy importers.
Forward Look
Governor Kazuo Ueda’s recusal from the upcoming meeting has added to the uncertainty around the policy outcome, though we don’t see it changing things materially. The market appears positioned for dovish surprises. Reports already point to the end of BOJ’s tapering of JGB purchases as a potential decision, and this would be sufficient to negate any tightening move. The BOJ and Ministry of Finance are evidently concerned about the risk pf disorderly moves in government bond markets, with inflation expectations becoming embedded. However, authorities are far from convinced that having a stronger currency is an asset in managing such moves, at least amid a supply shock that damages Japan’s balance of payments. Hence, this “one step forward (on rates), half a step back (on balance sheet operations)” remains the preferred path, but it’s unlikely to leave much room for JPY strength, particularly as intervention will be used sparingly.
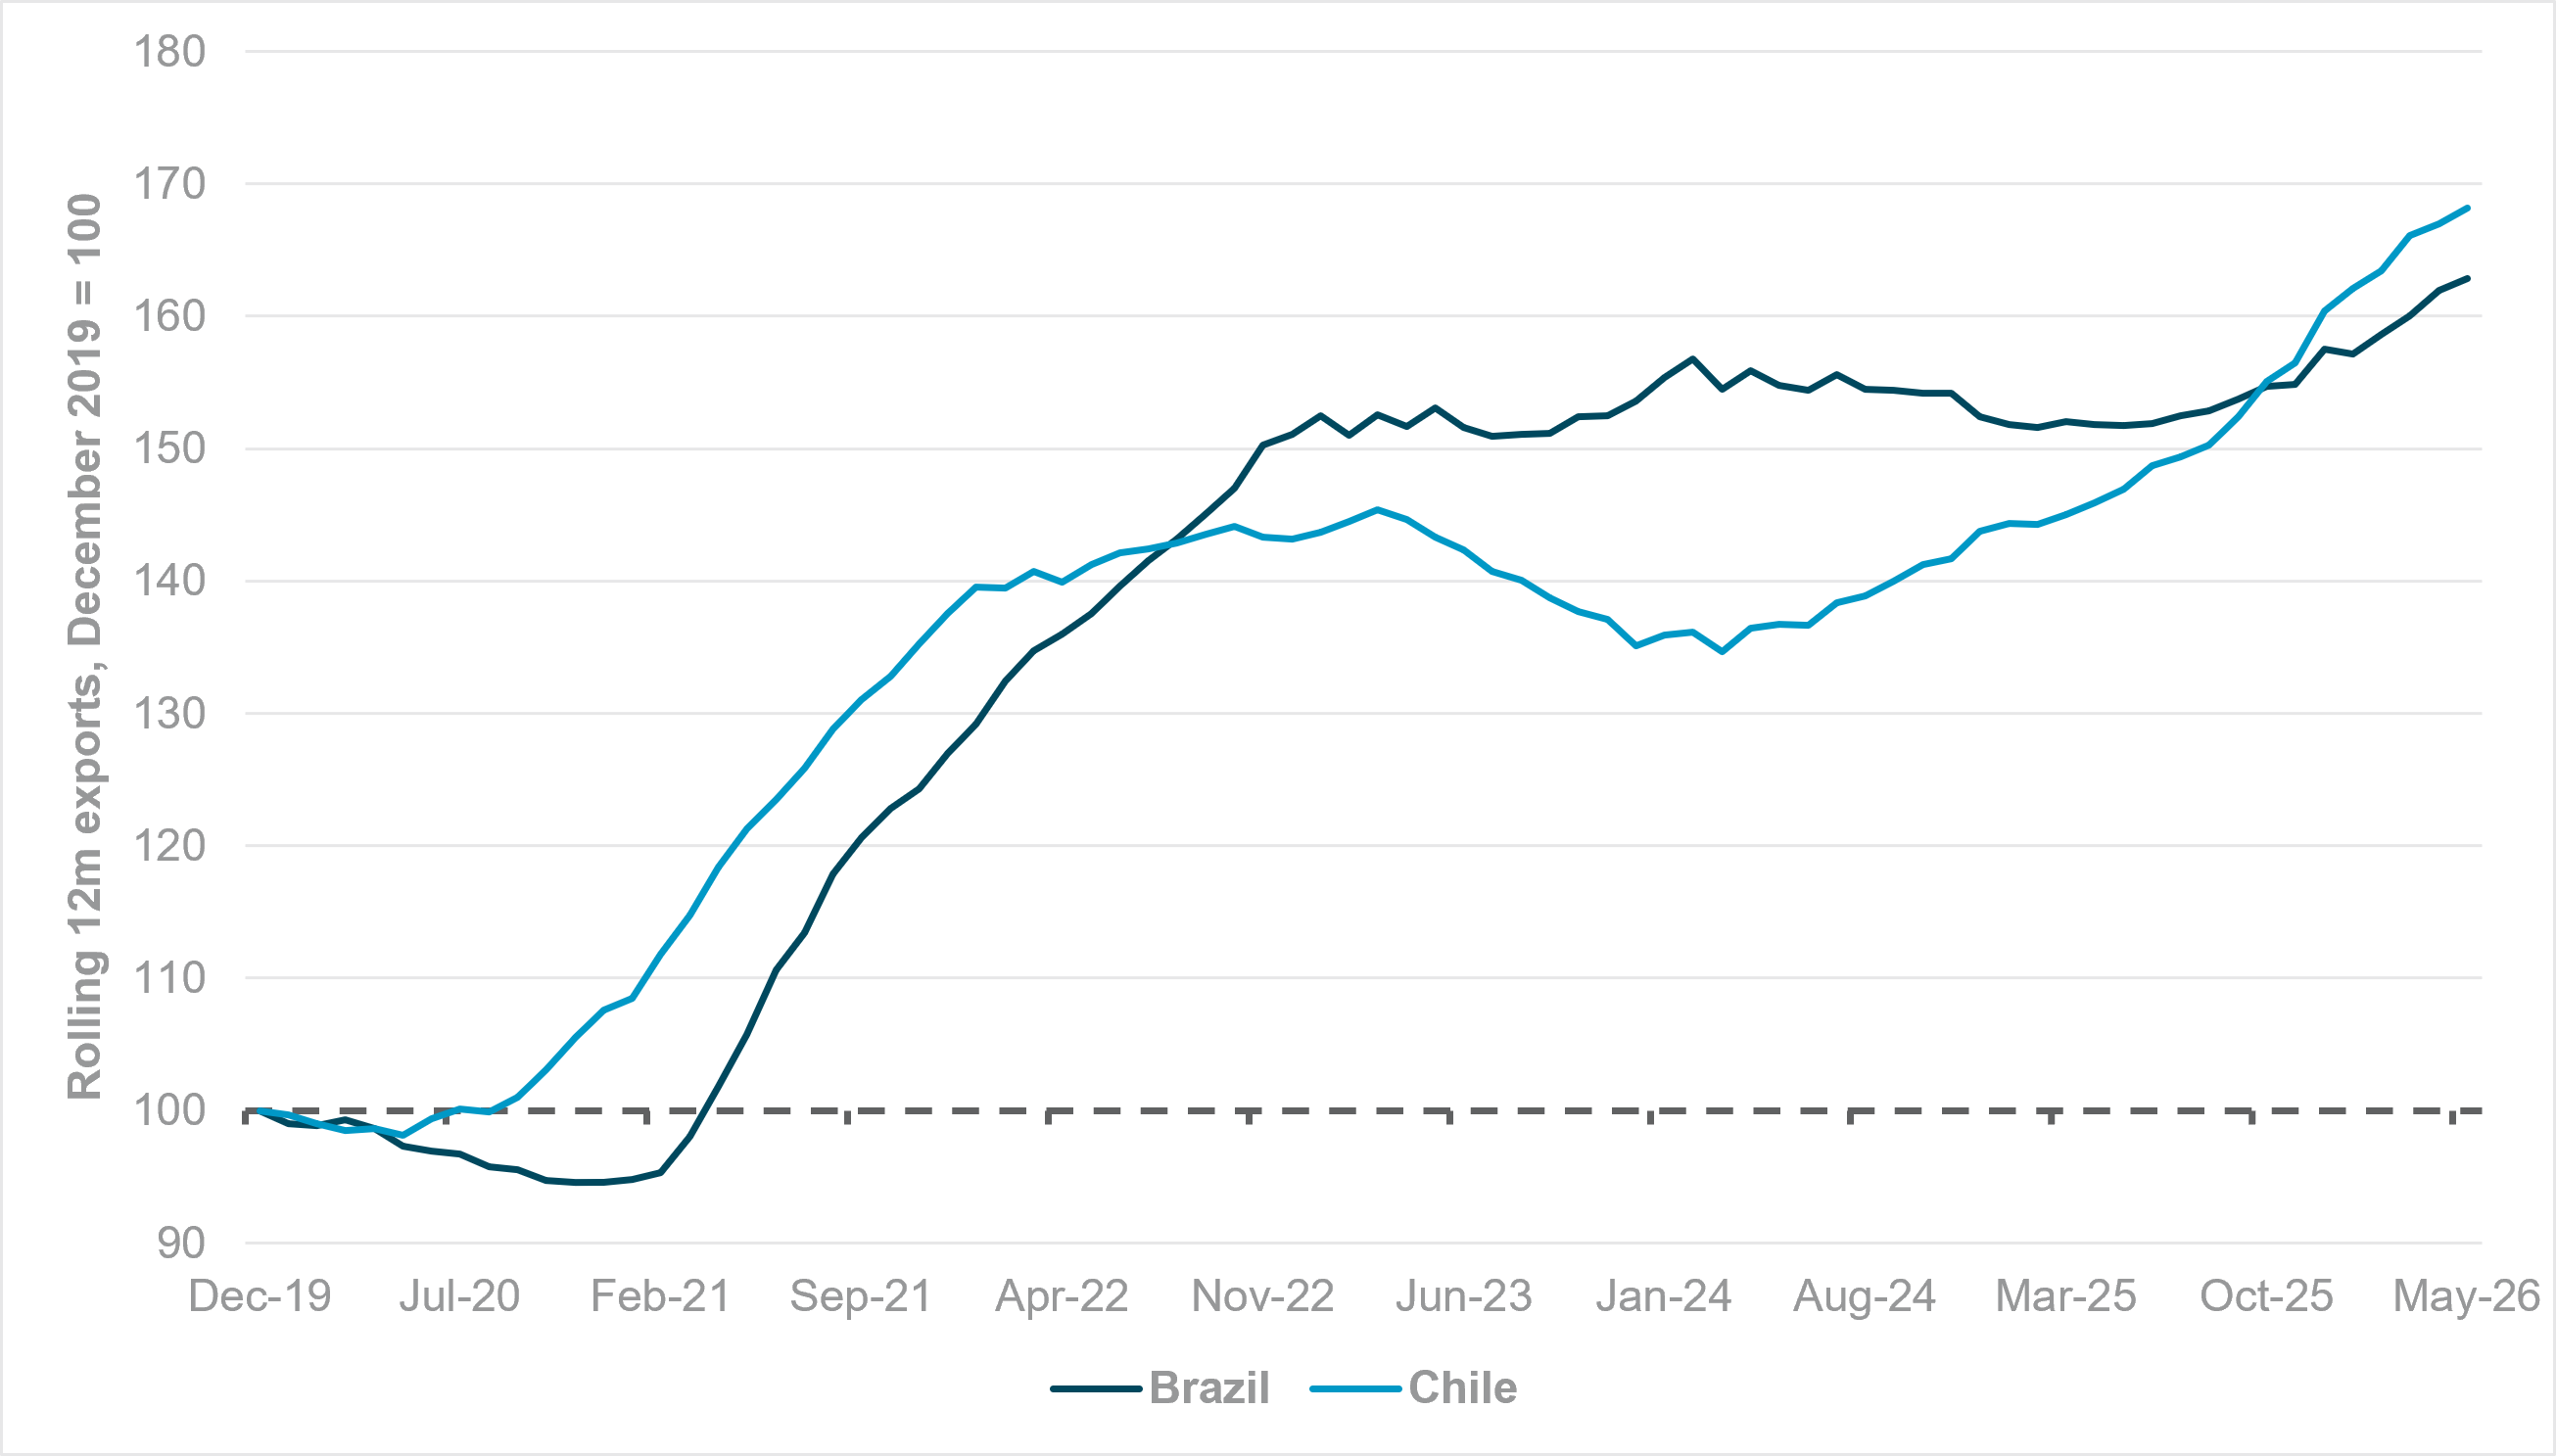
EXHIBIT #3: ROLLING 12-MONTH EXPORTS (USD BN), INDEXED TO DECEMBER 2019 = 100
Source: BNY, Bloomberg LP
Our take
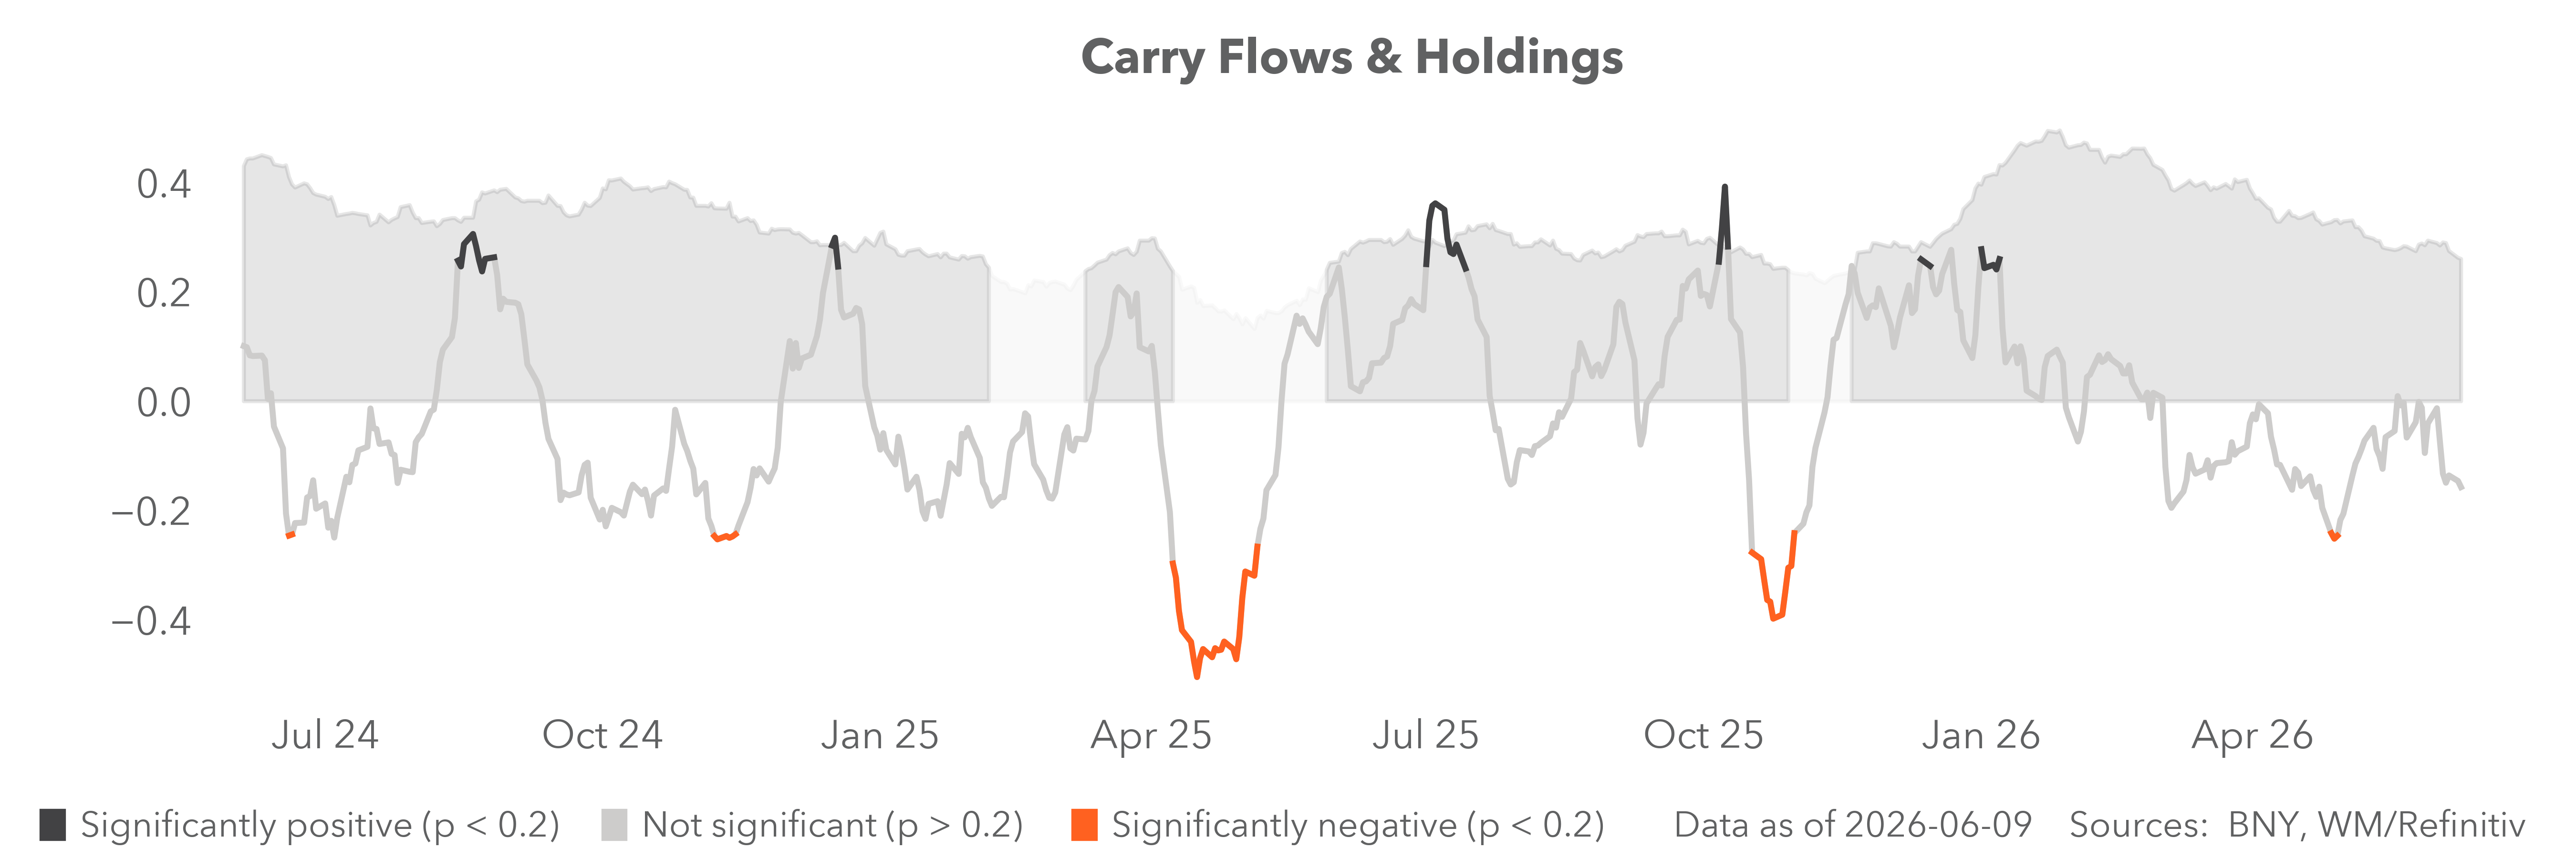
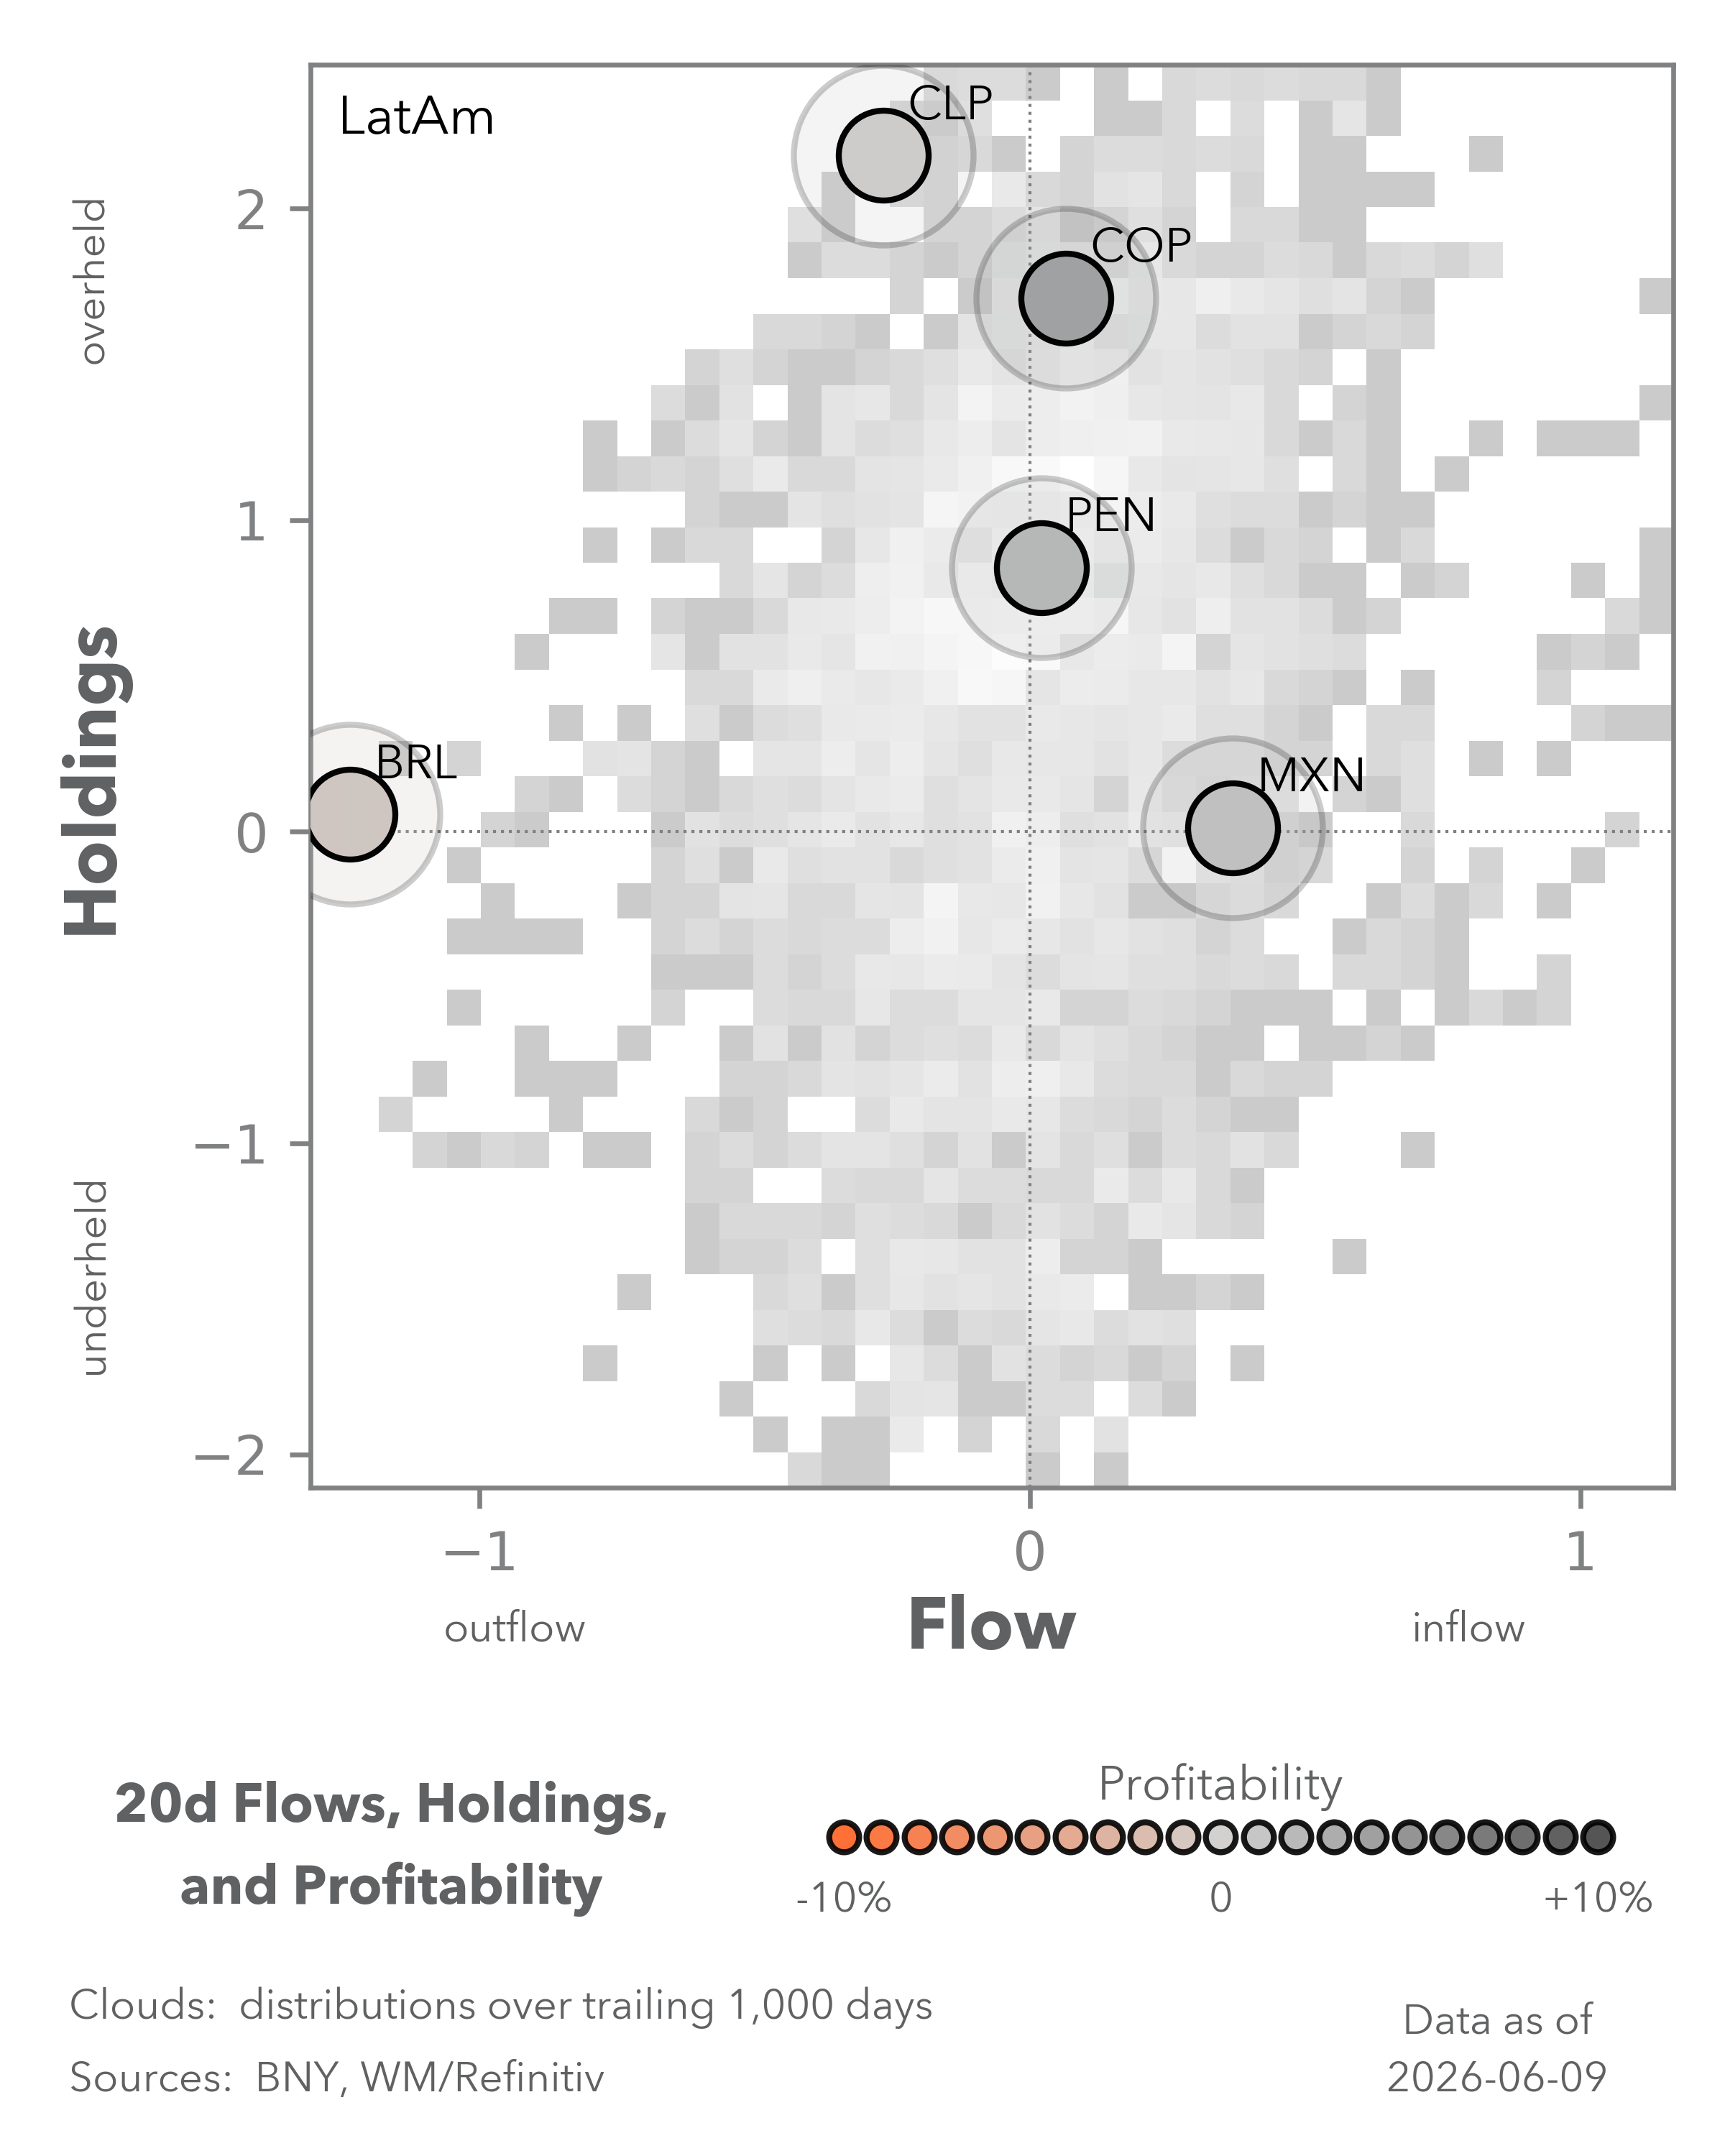
Our iFlow Carry indicator is pointing to declines in holdings in high-yielding currencies, and the process is likely to continue as markets adjust to a new Fed reality. Even so, we continue to distinguish between a steady reduction in carry holdings – the situation at present – and outright liquidation. LatAm currencies are the most resilient group in this context, but transmission of Fed rates is swift into the region, while political developments are also influencing investment flows, in both directions. That said, we shouldn’t discount the positive terms-of-trade shock to the region. For the likes of Brazil and Chile, export values have risen to multi-year highs due to the conflict and other structural factors (Exhibit 3). In contrast to much of Asia, these natural flows will help offset the rise in global dollar preference, but central banks will need to stay vigilant and ensure real rates adjust to new Fed dynamics.
Forward look
Rate decisions in Peru, Chile and Brazil over the next trading week should not yield any major surprises, but LatAm currencies will need to monitor elevated short-term dollar preference. USD rates aside, the need to generate dollar liquidity to fund share sales and U.S.-market offerings remains high, and the market may move toward higher-hanging fruits. In FX markets, LatAm carry trades and fixed income positions are the last expression of “risk-on”, particularly as cross-border dollar hedges have fully unwound the excess short positions built before the conflict. Yields and the policy outlook are now only sufficient to limit large-scale liquidation. But if the aim is to attract fresh inflows to ease onshore financial conditions, policy decisions may need to lean more hawkish.