In search of relief from Hormuz normalization
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.

Geoff Yu
Time to Read: 4 minutes
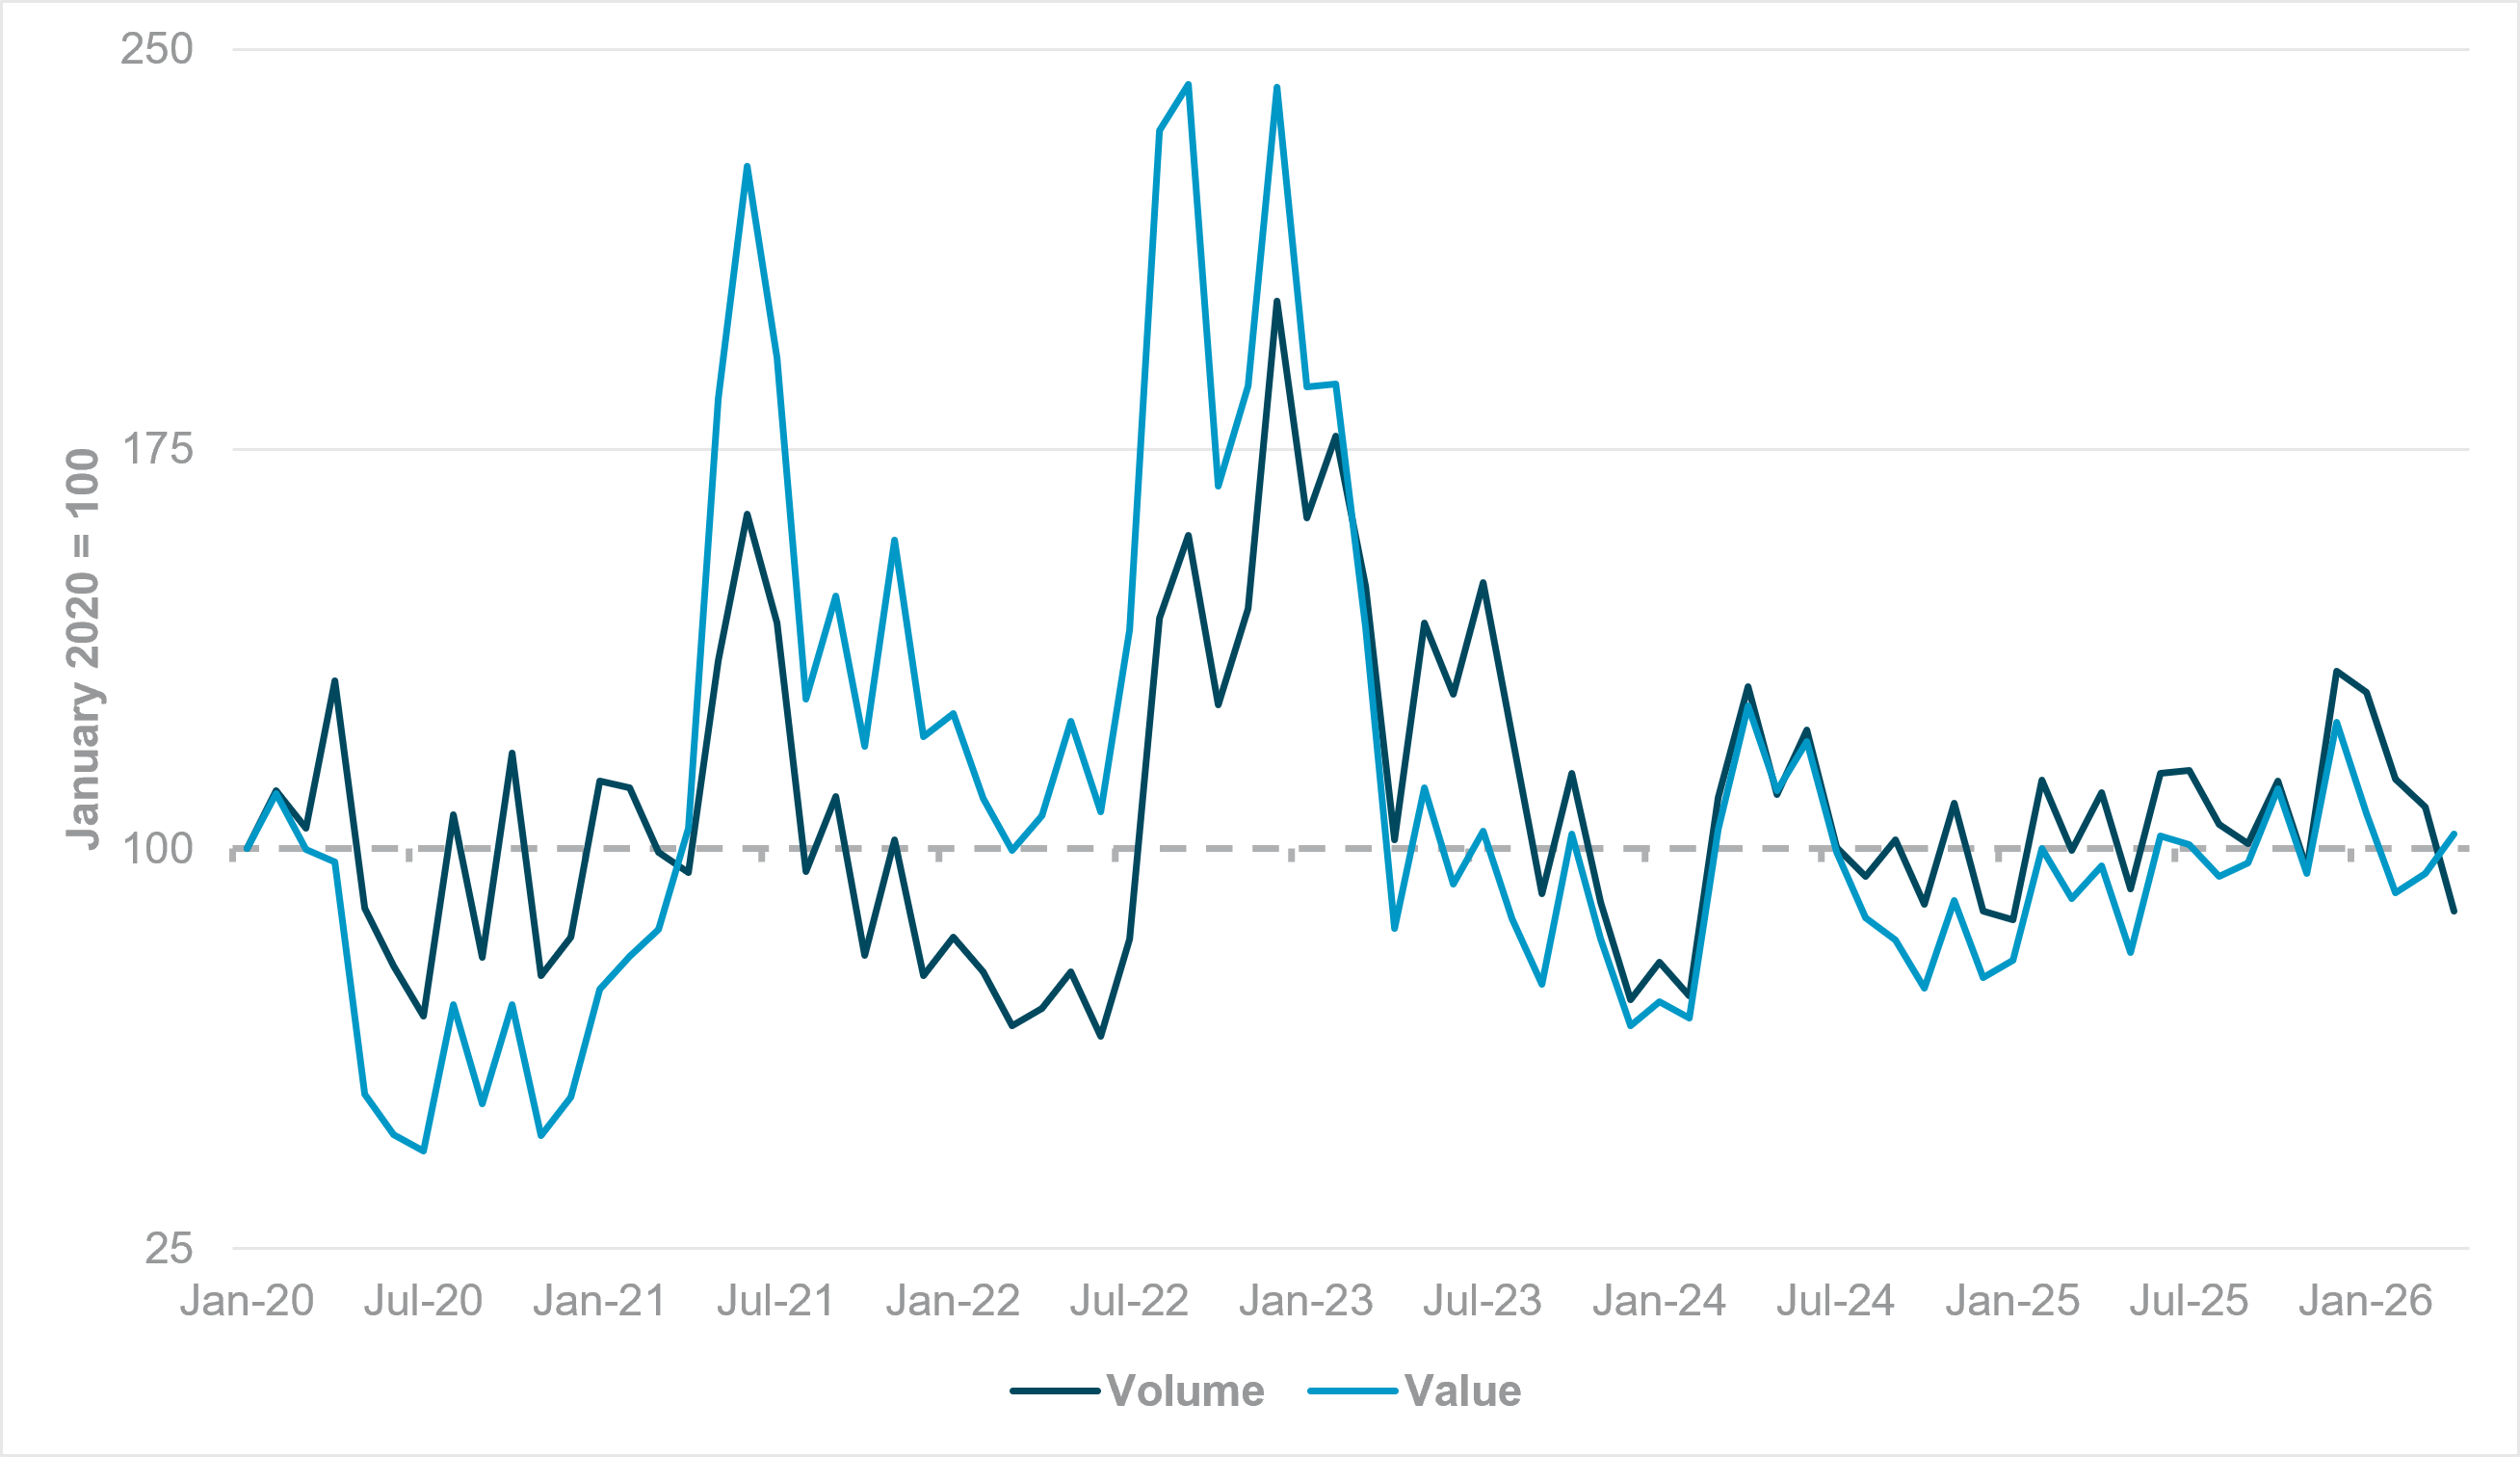
EXHIBIT #1: CHINESE REFINED PETROLEUM EXPORTS, QUANTUM AND VALUE
Source: BNY
Our take
Assuming the ceasefire takes full effect, many currencies around the world can look for further relief, even if the Fed’s stance has now raised the bar for performance. Southeast Asian economies were heavily affected by the oil shock during the early days of the conflict, to the extent that the rapid depletion in energy stocks and FX reserves led to concerns over a new balance-of-payments crisis. High levels of dependency on imported crude aside, China’s sudden blocking of refined products also played a critical role in risk aversion, particularly in the Philippines, and in developed markets such as Australia. Export data show a clear drop in the volume of refined mineral fuel products from China as the conflict began (Exhibit 1), though we note that the cumulative drop in 2023 was far bigger. That said, policymakers in the region deserve some of the blame for failing to build energy market resilience.
Forward Look
Weak Chinese demand for crude has been cited as one of the reasons behind prices not surging further during the more difficult phases of the conflict. The latest round of data from Beijing suggest that this won’t change anytime soon. Potentially, this means there will be surpluses of refined products from China returning to the market. The data indicate that a period of export surges after a decline need not result in high-value gains, e.g., in H2 2023. This could represent the best of both worlds for importers of refined products – more supply at low cost.
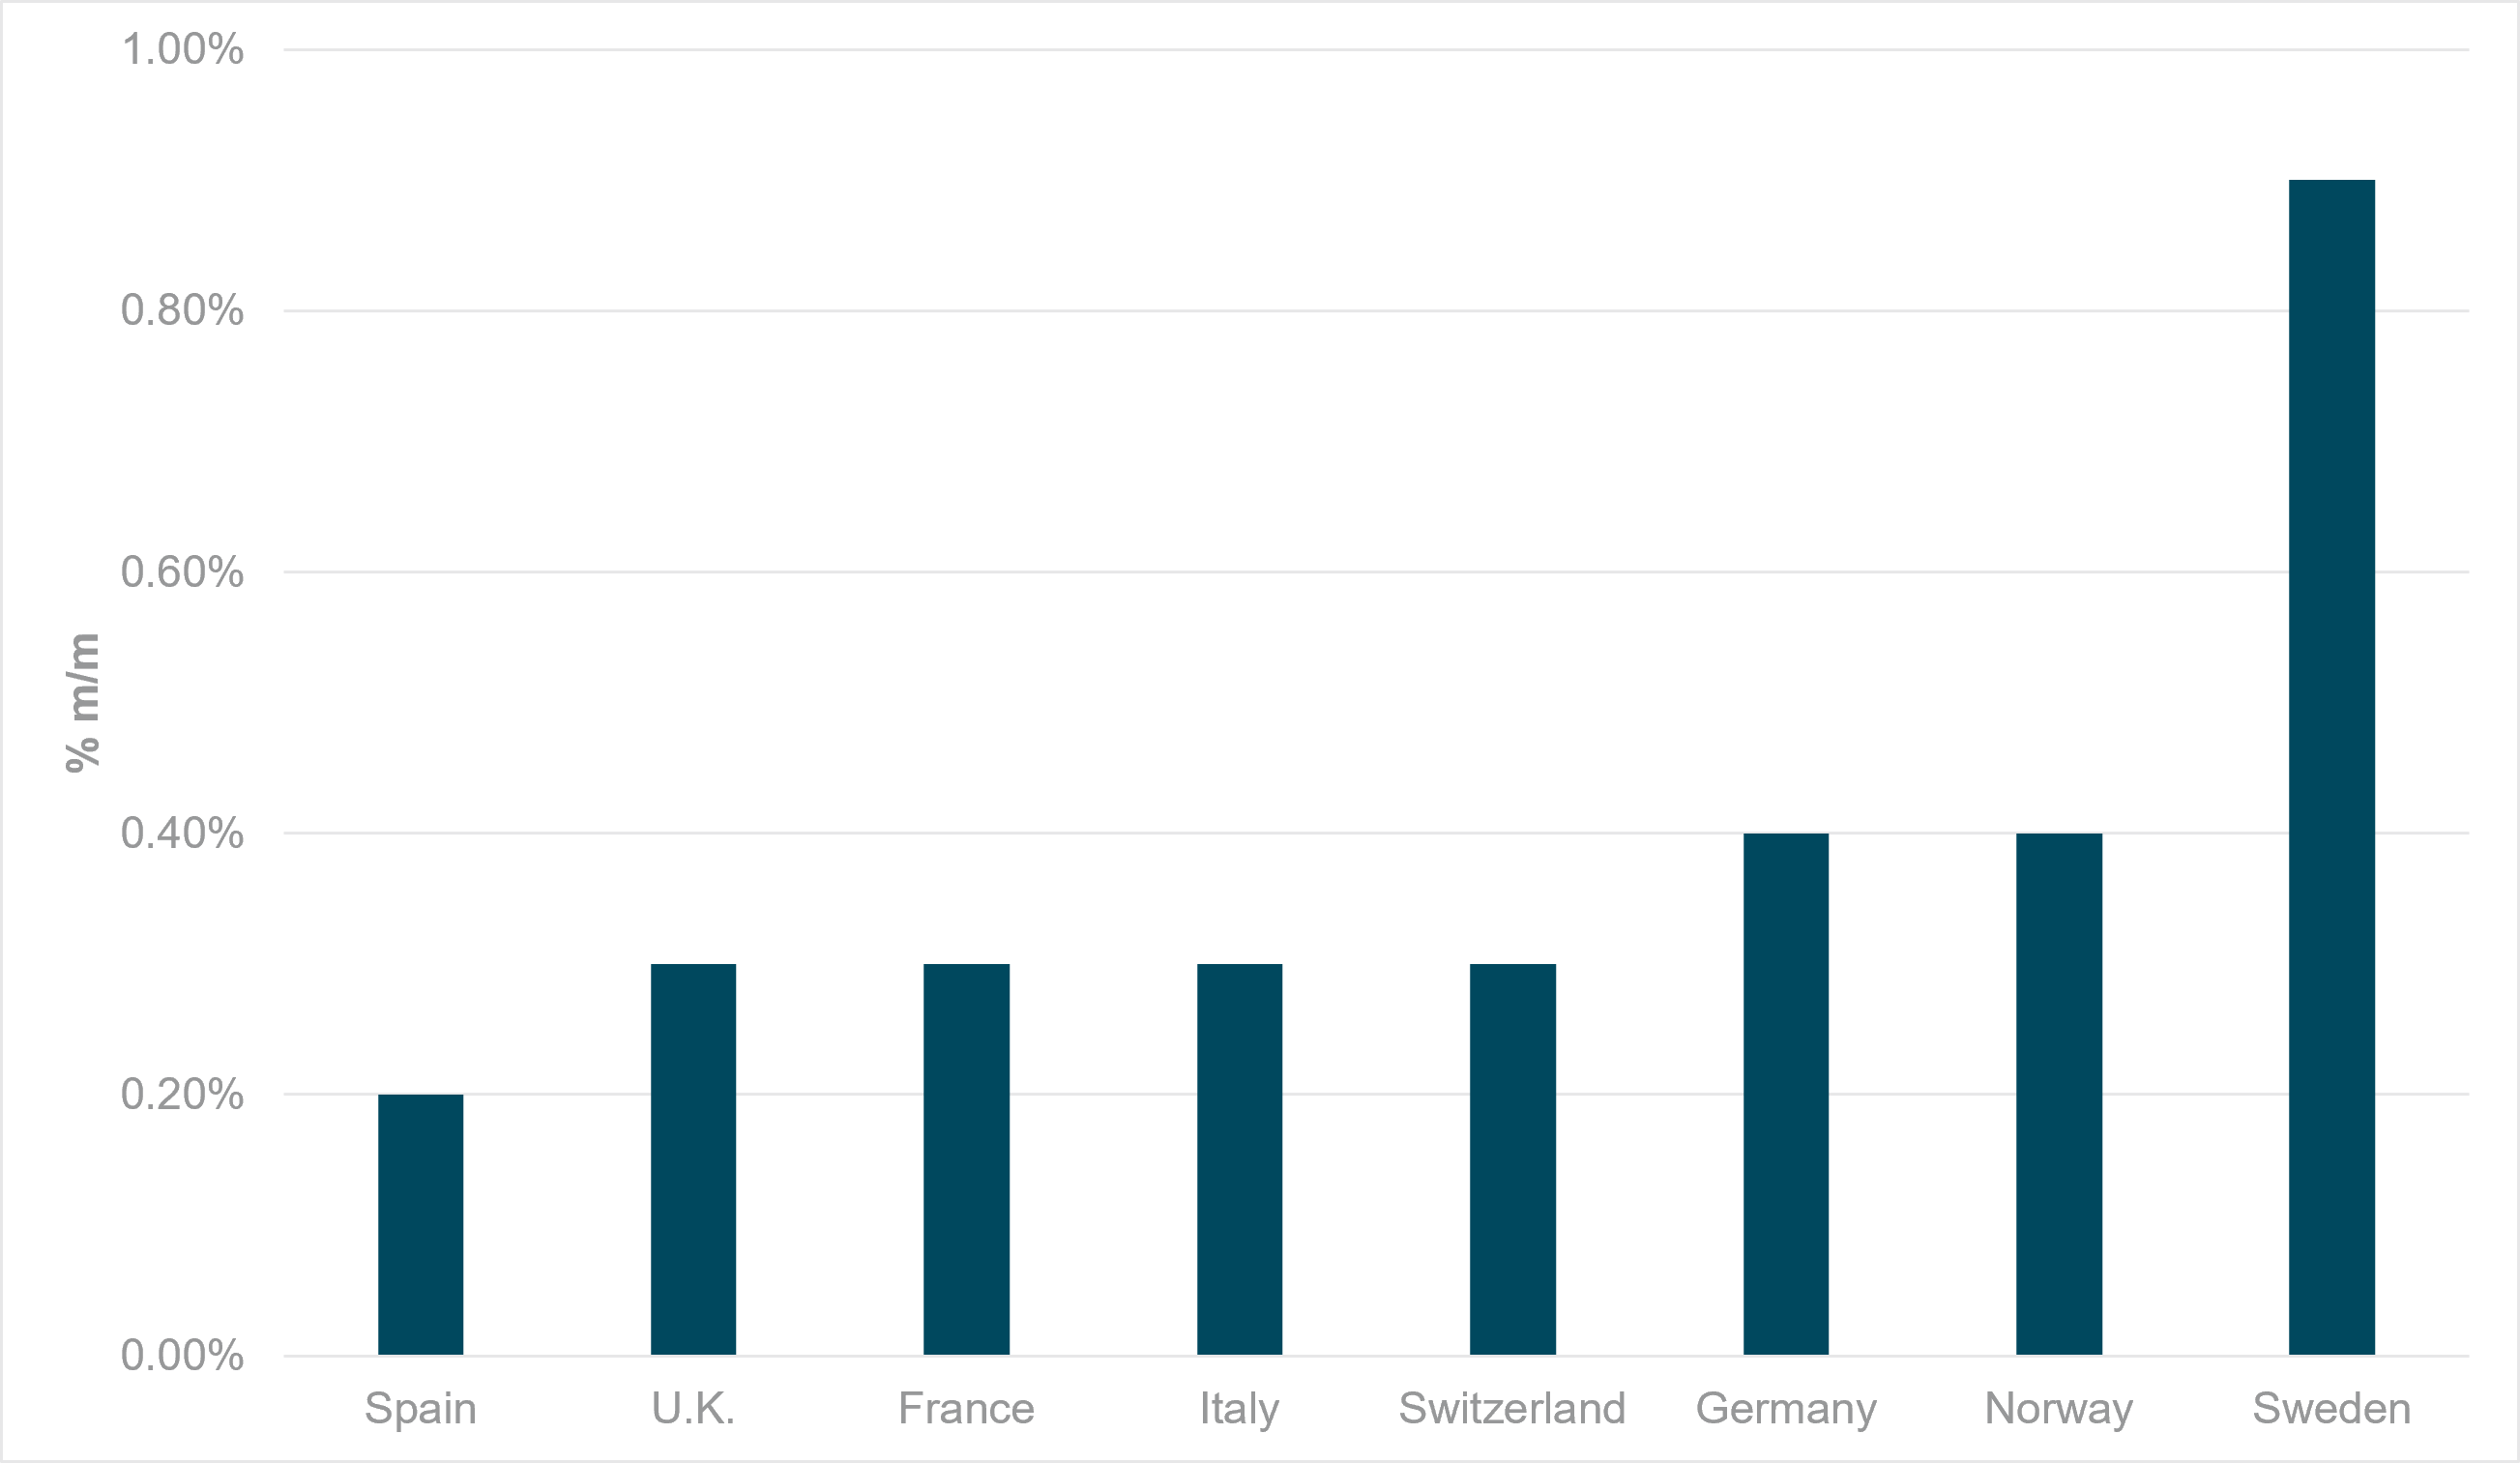
EXHIBIT #2: MAY SEQUENTIAL CORE INFLATION PRINTS ACROSS WESTERN EUROPE
Source: BNY
Our take
We maintain our view that the ECB hike last week was policy error. The fact that several Governing Council members immediately indicated a July hike was possible is even more surprising, especially with growth continuing to struggle. ECB President Christine Lagarde acknowledged that there will be an impact to growth, and if the next round of forecasts point to a larger downside revision (vs. 10bp in June), policy volatility will rise materially.
If the ECB insists on sticking to the inflation targeting regime rigidly, there’s also the question of what type of inflation policymakers should now target. Second-round effects are mostly reflected in core inflation and wages. By the ECB’s own admission, there are insufficient signs of the latter. We now doubt that a strong case can be made for the former anywhere in Europe. Sweden aside, we would argue that core inflation across western Europe is relatively contained. The Riksbank highlighted that services inflation increased to reflect higher input costs. Even with such a strong sequential move, the best the Riksbank could manage was to add 25bp to expected repo rate levels across their forecast horizon, rather than the 50bp in two meetings that the ECB is mulling.
Forward Look
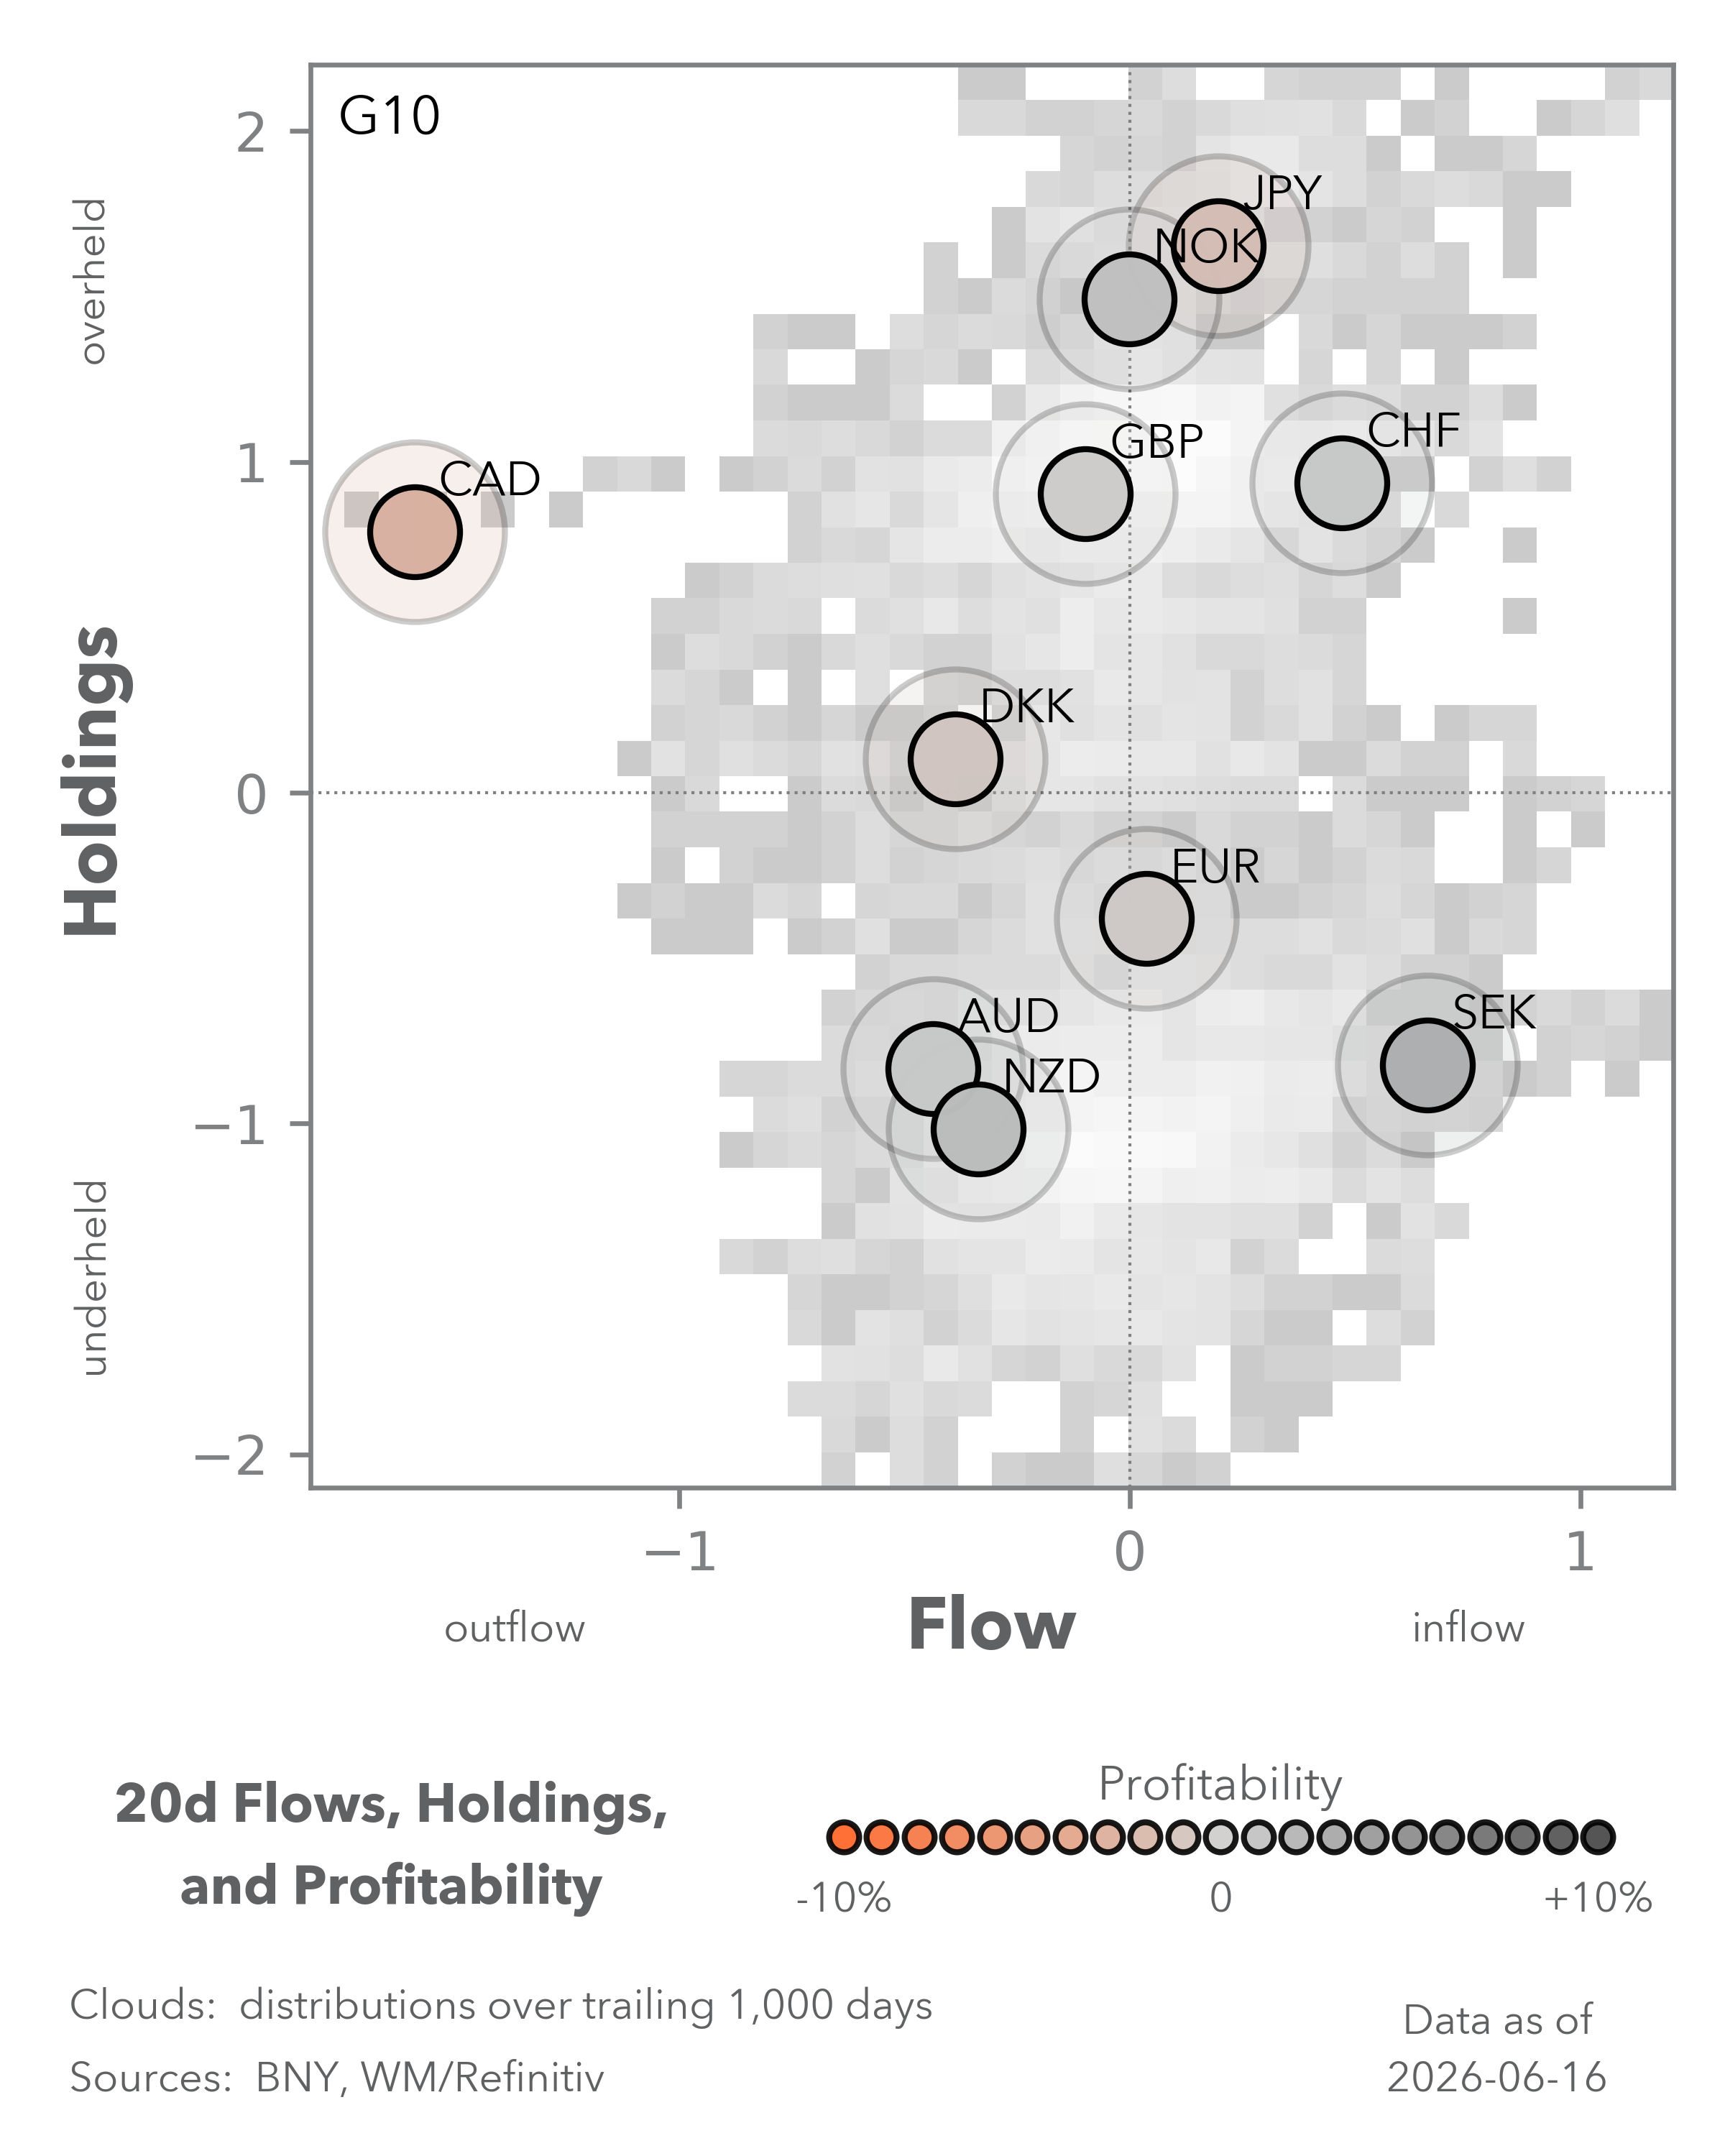
The ECB cannot look at inflation in isolation. If a policy gap opens materially, the relative tightening in financial conditions versus its immediate peers will be significantly detrimental to the economy. As for other key partners, China is clearly looking at more easing given the data, and the Fed is not in a position to hike yet – so there’s very limited relief. The EUR’s failure to achieve any form of traction despite the ECB’s stance reflects such risks. Rate cuts are already priced in for 2027, and we expect them to be brought forward, further hurting the EUR.
EXHIBIT #3: ROLLING 12-MONTH EXPORTS (USD BN), INDEXED TO DECEMBER 2019 = 100
Source: BNY, Bloomberg LP
Our take
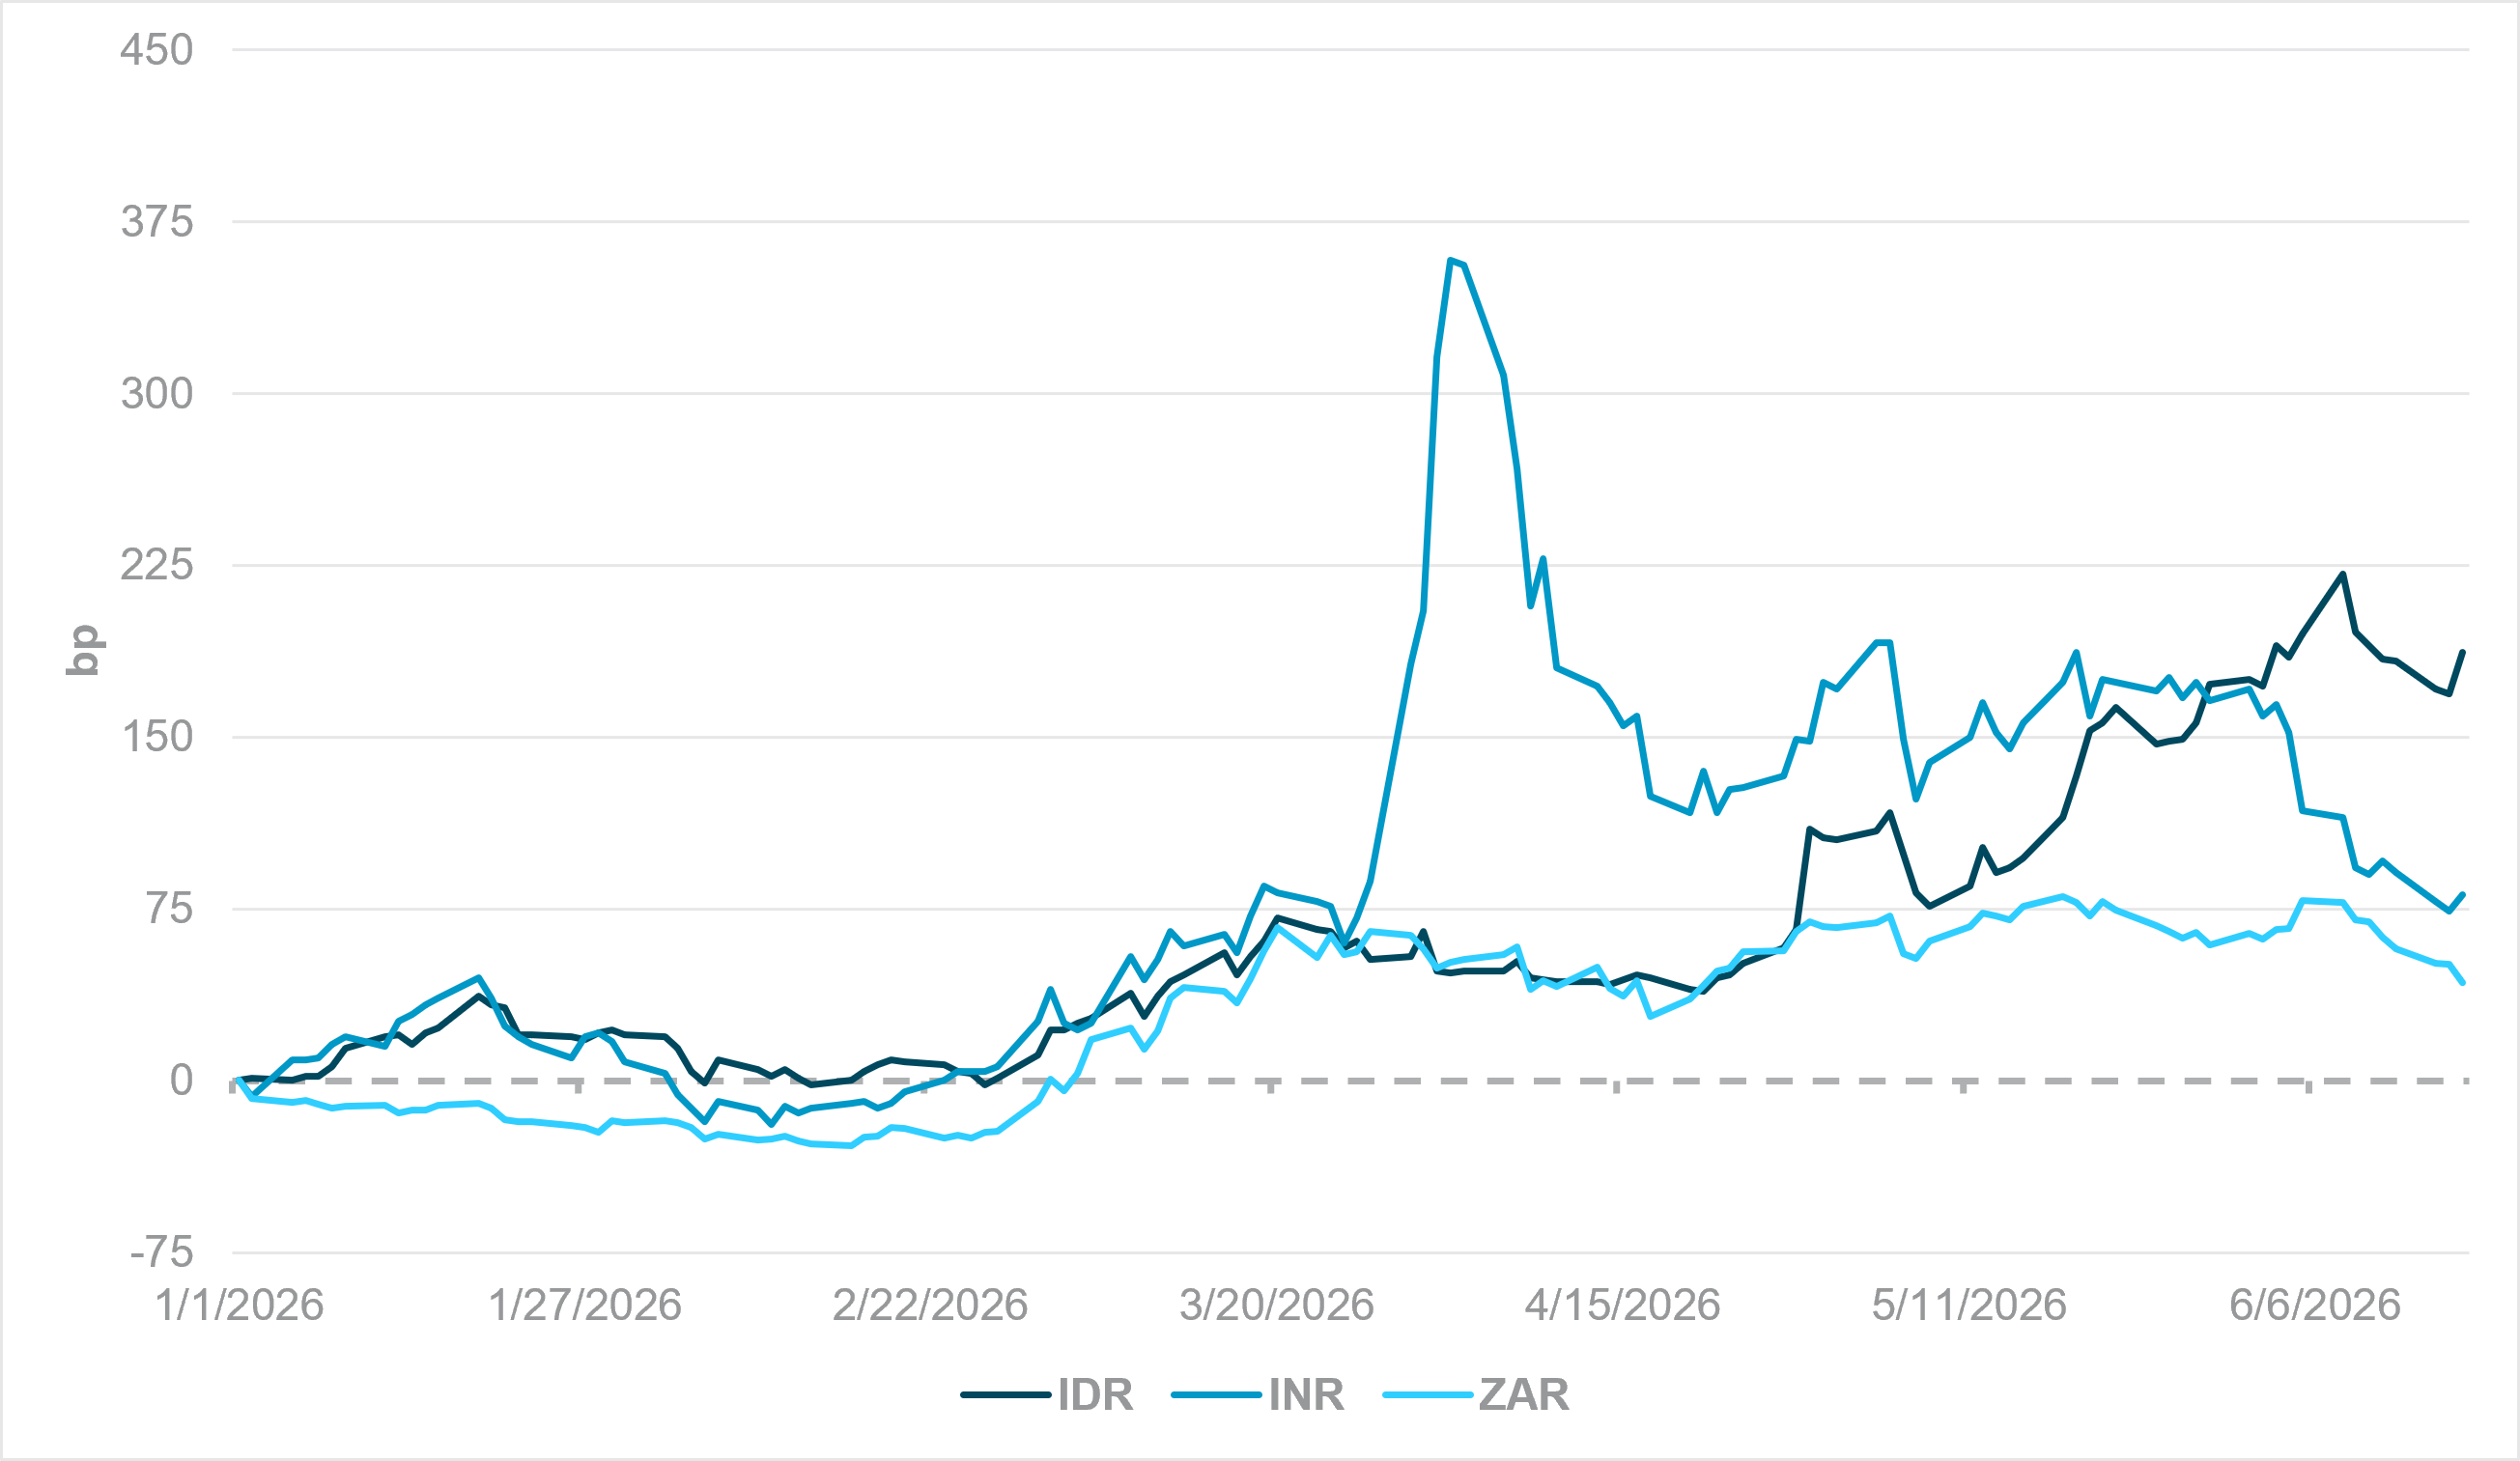
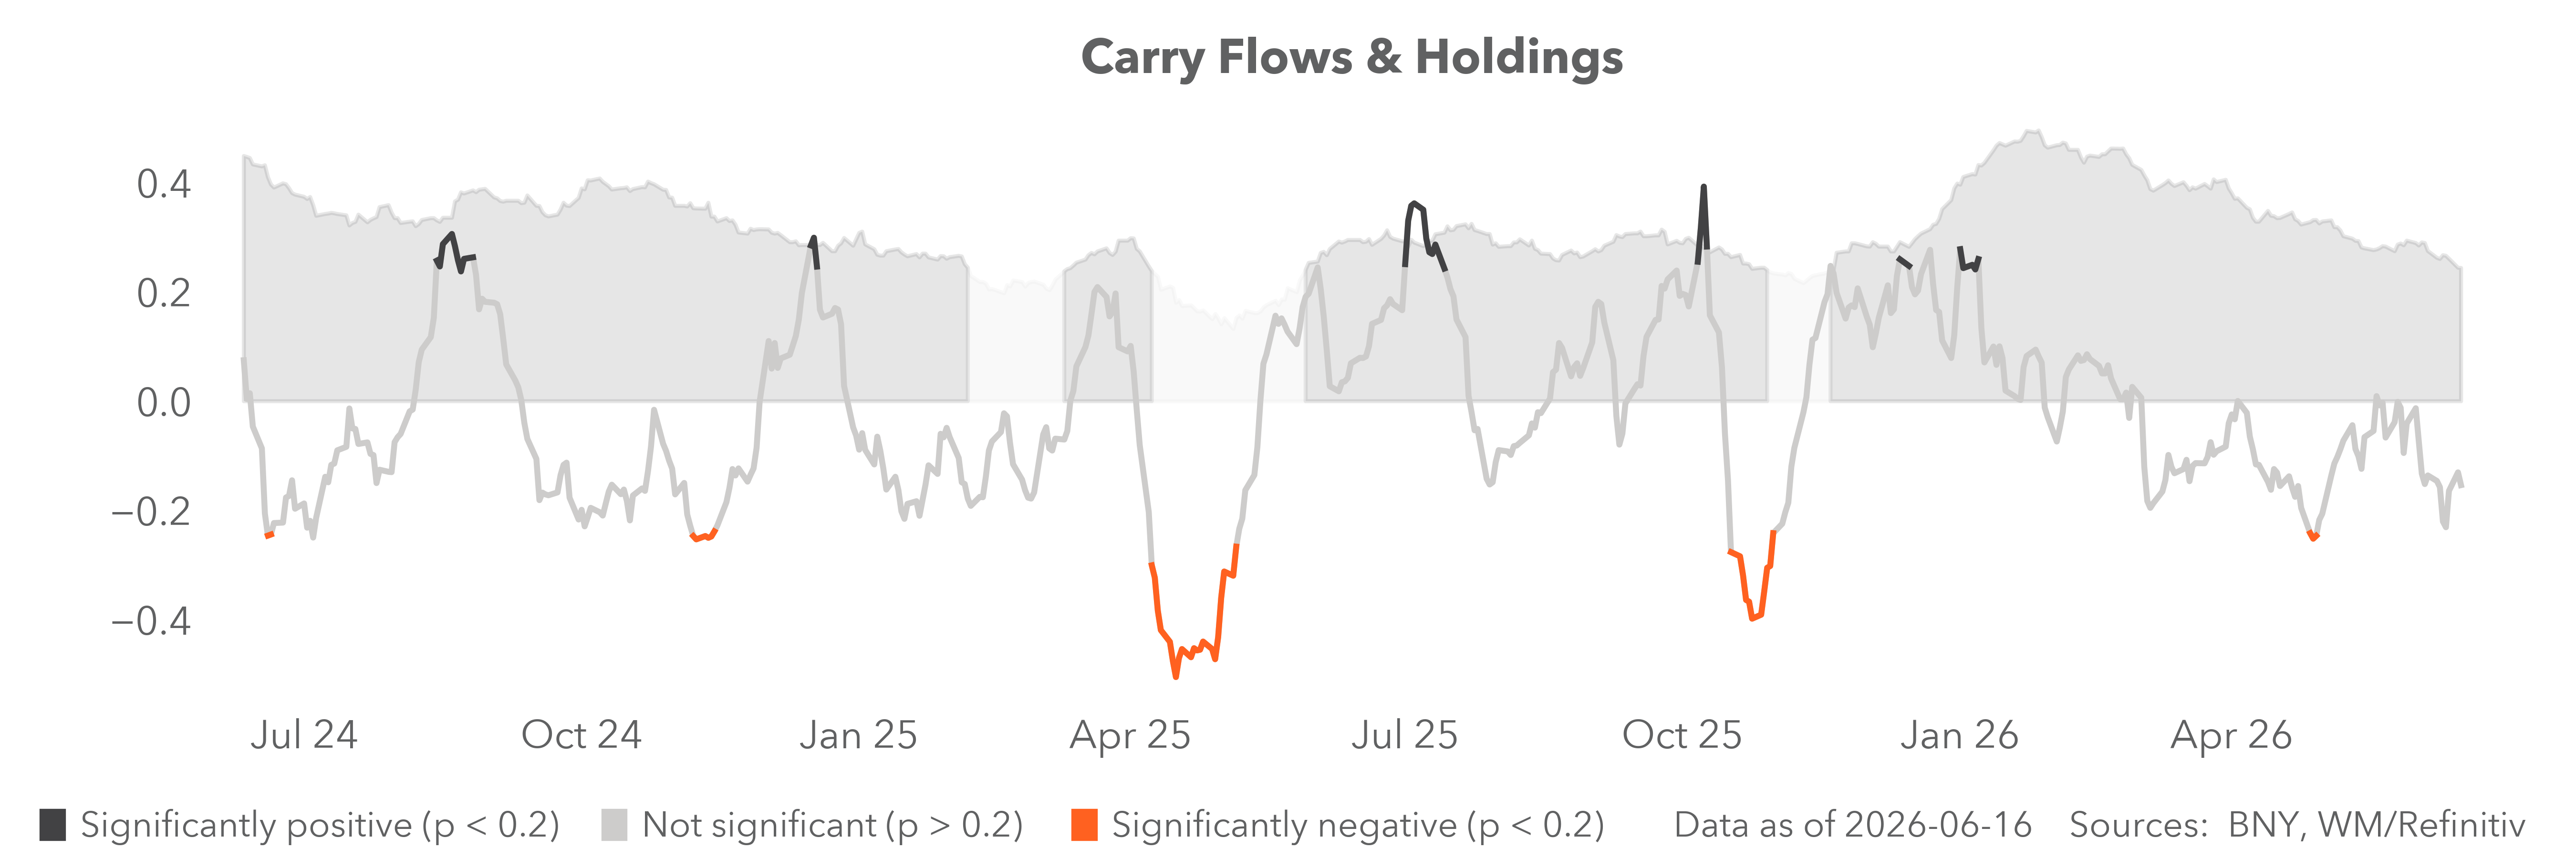
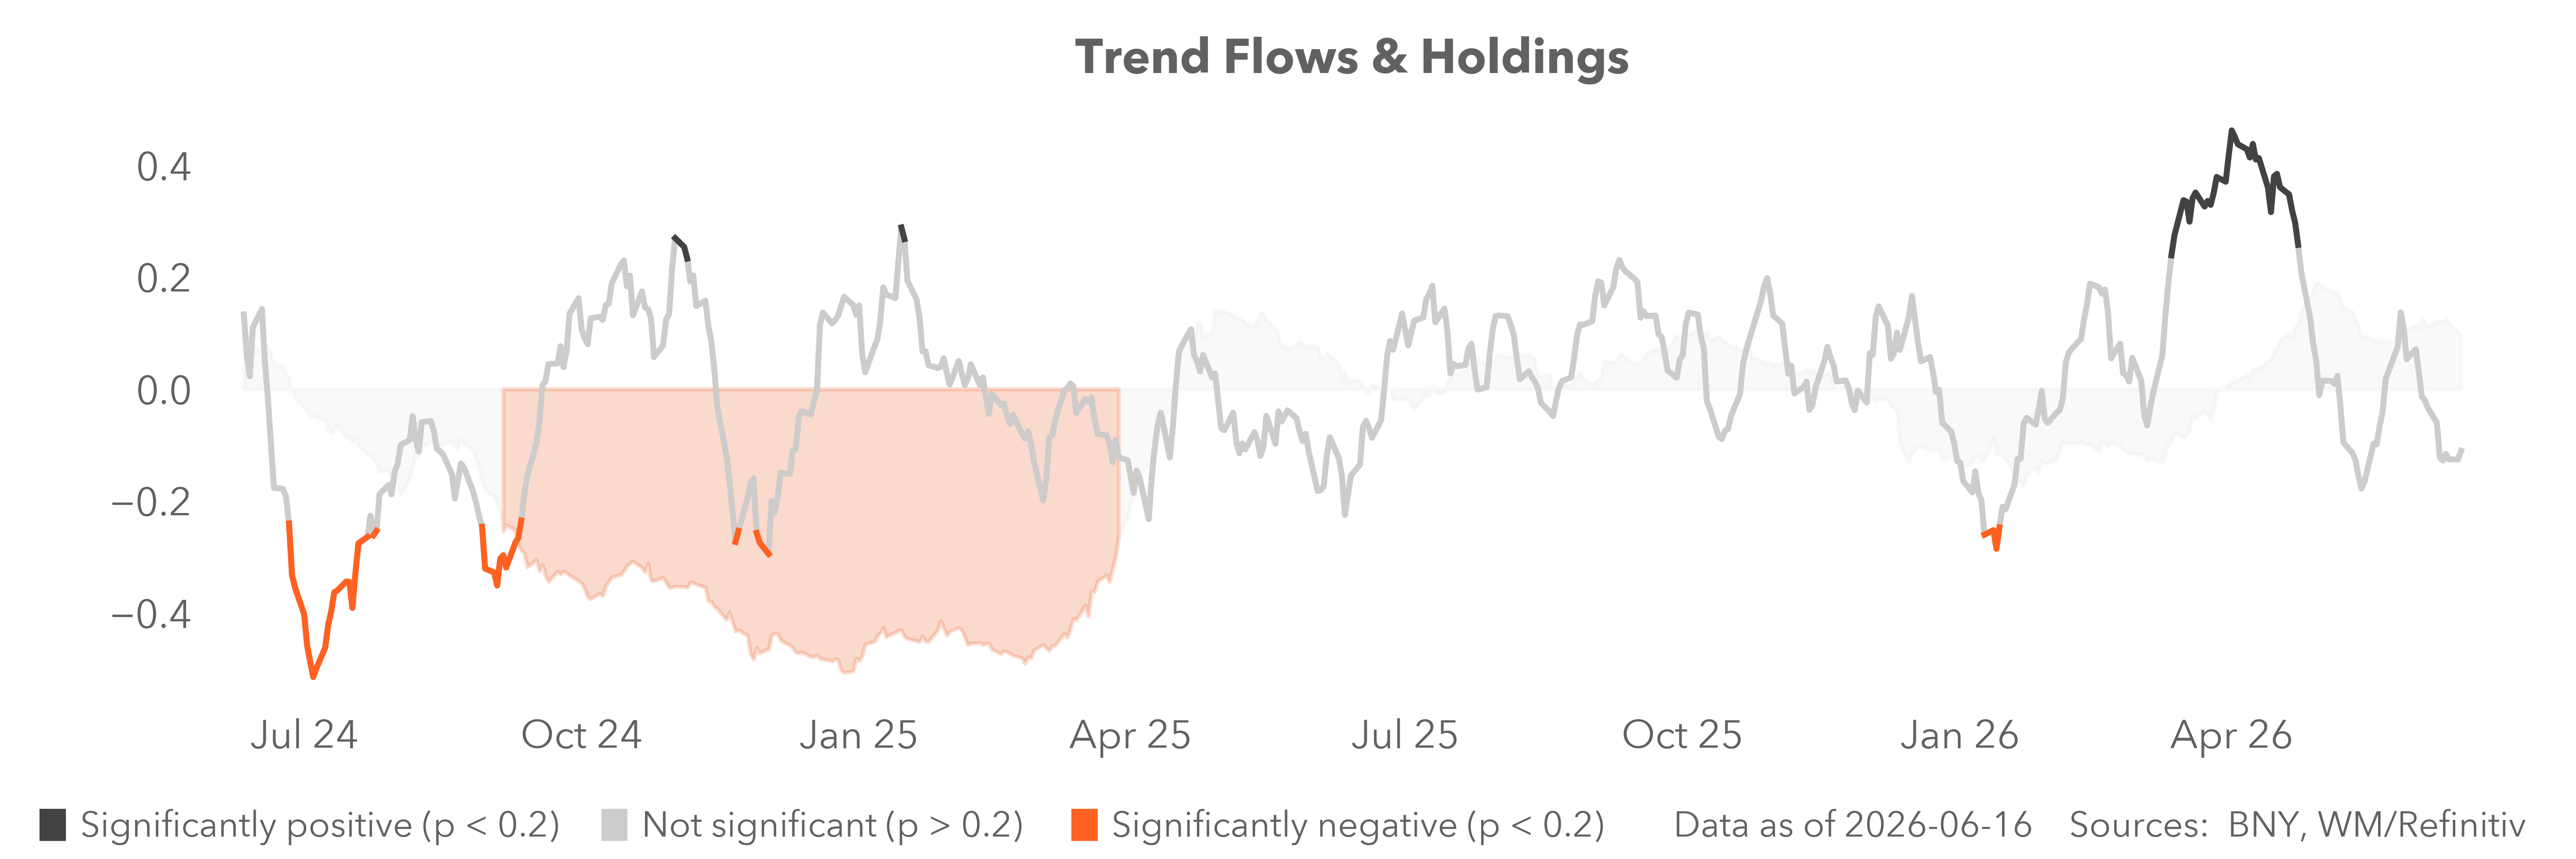
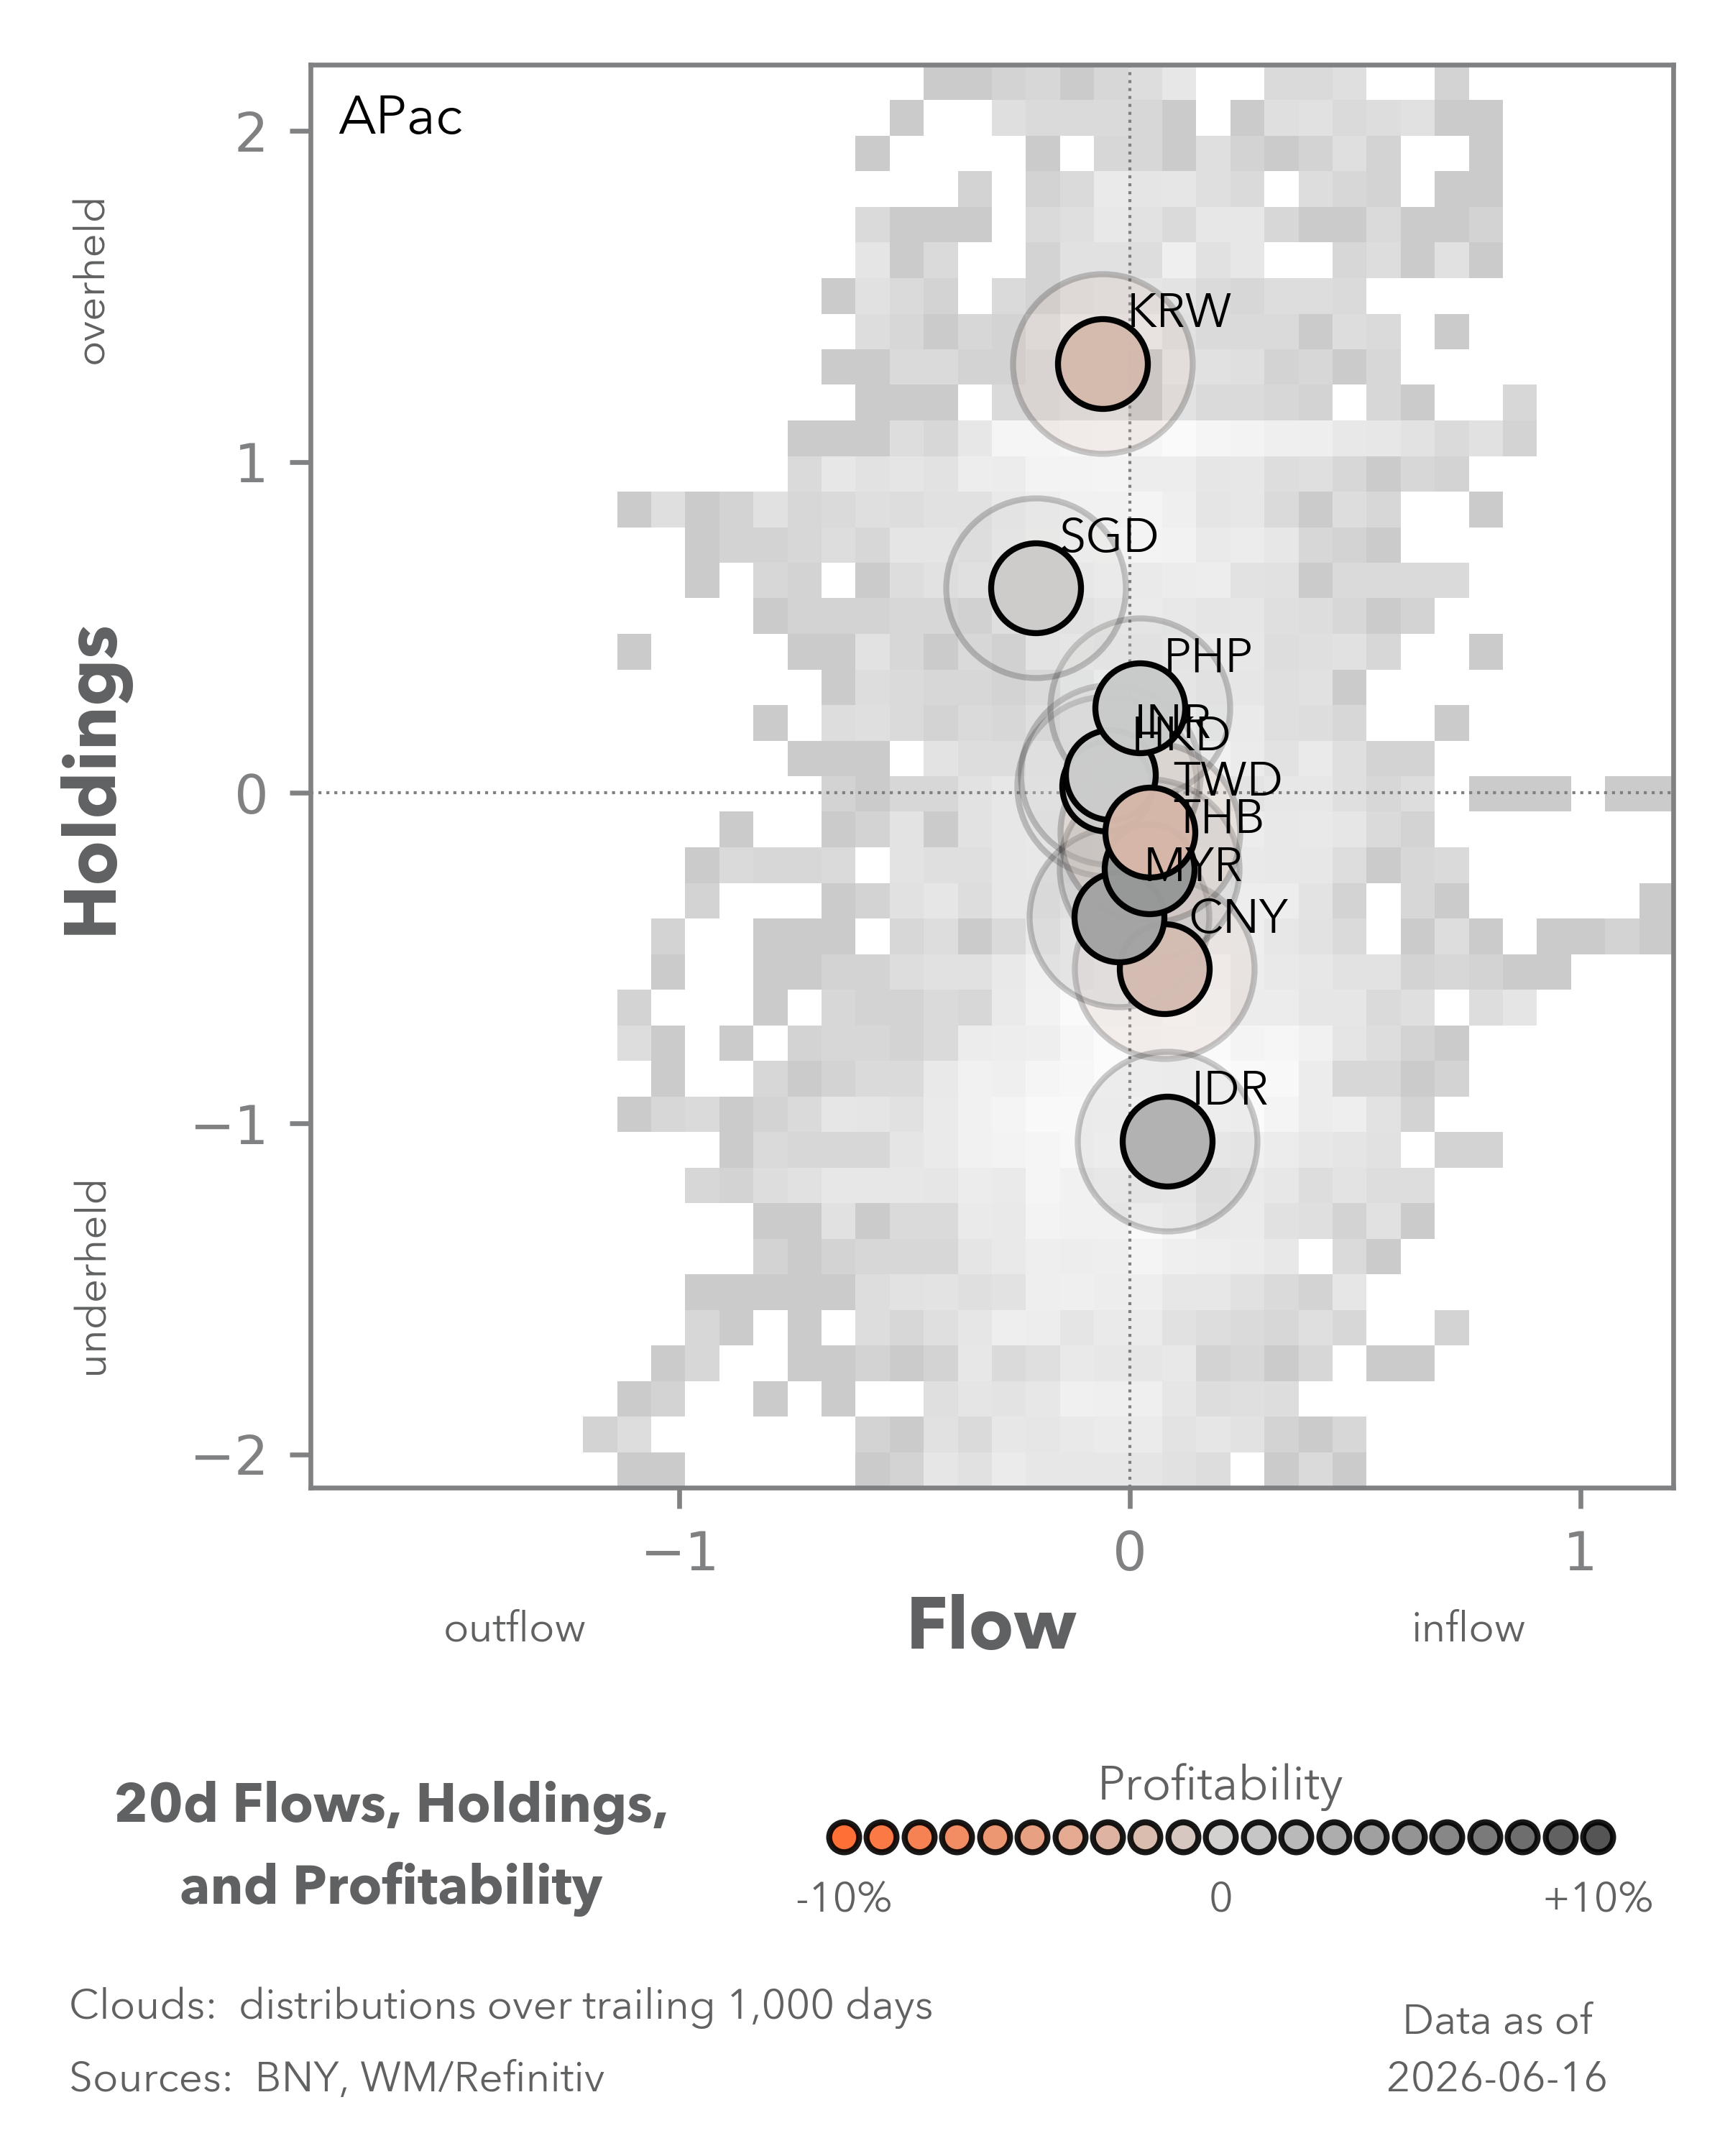
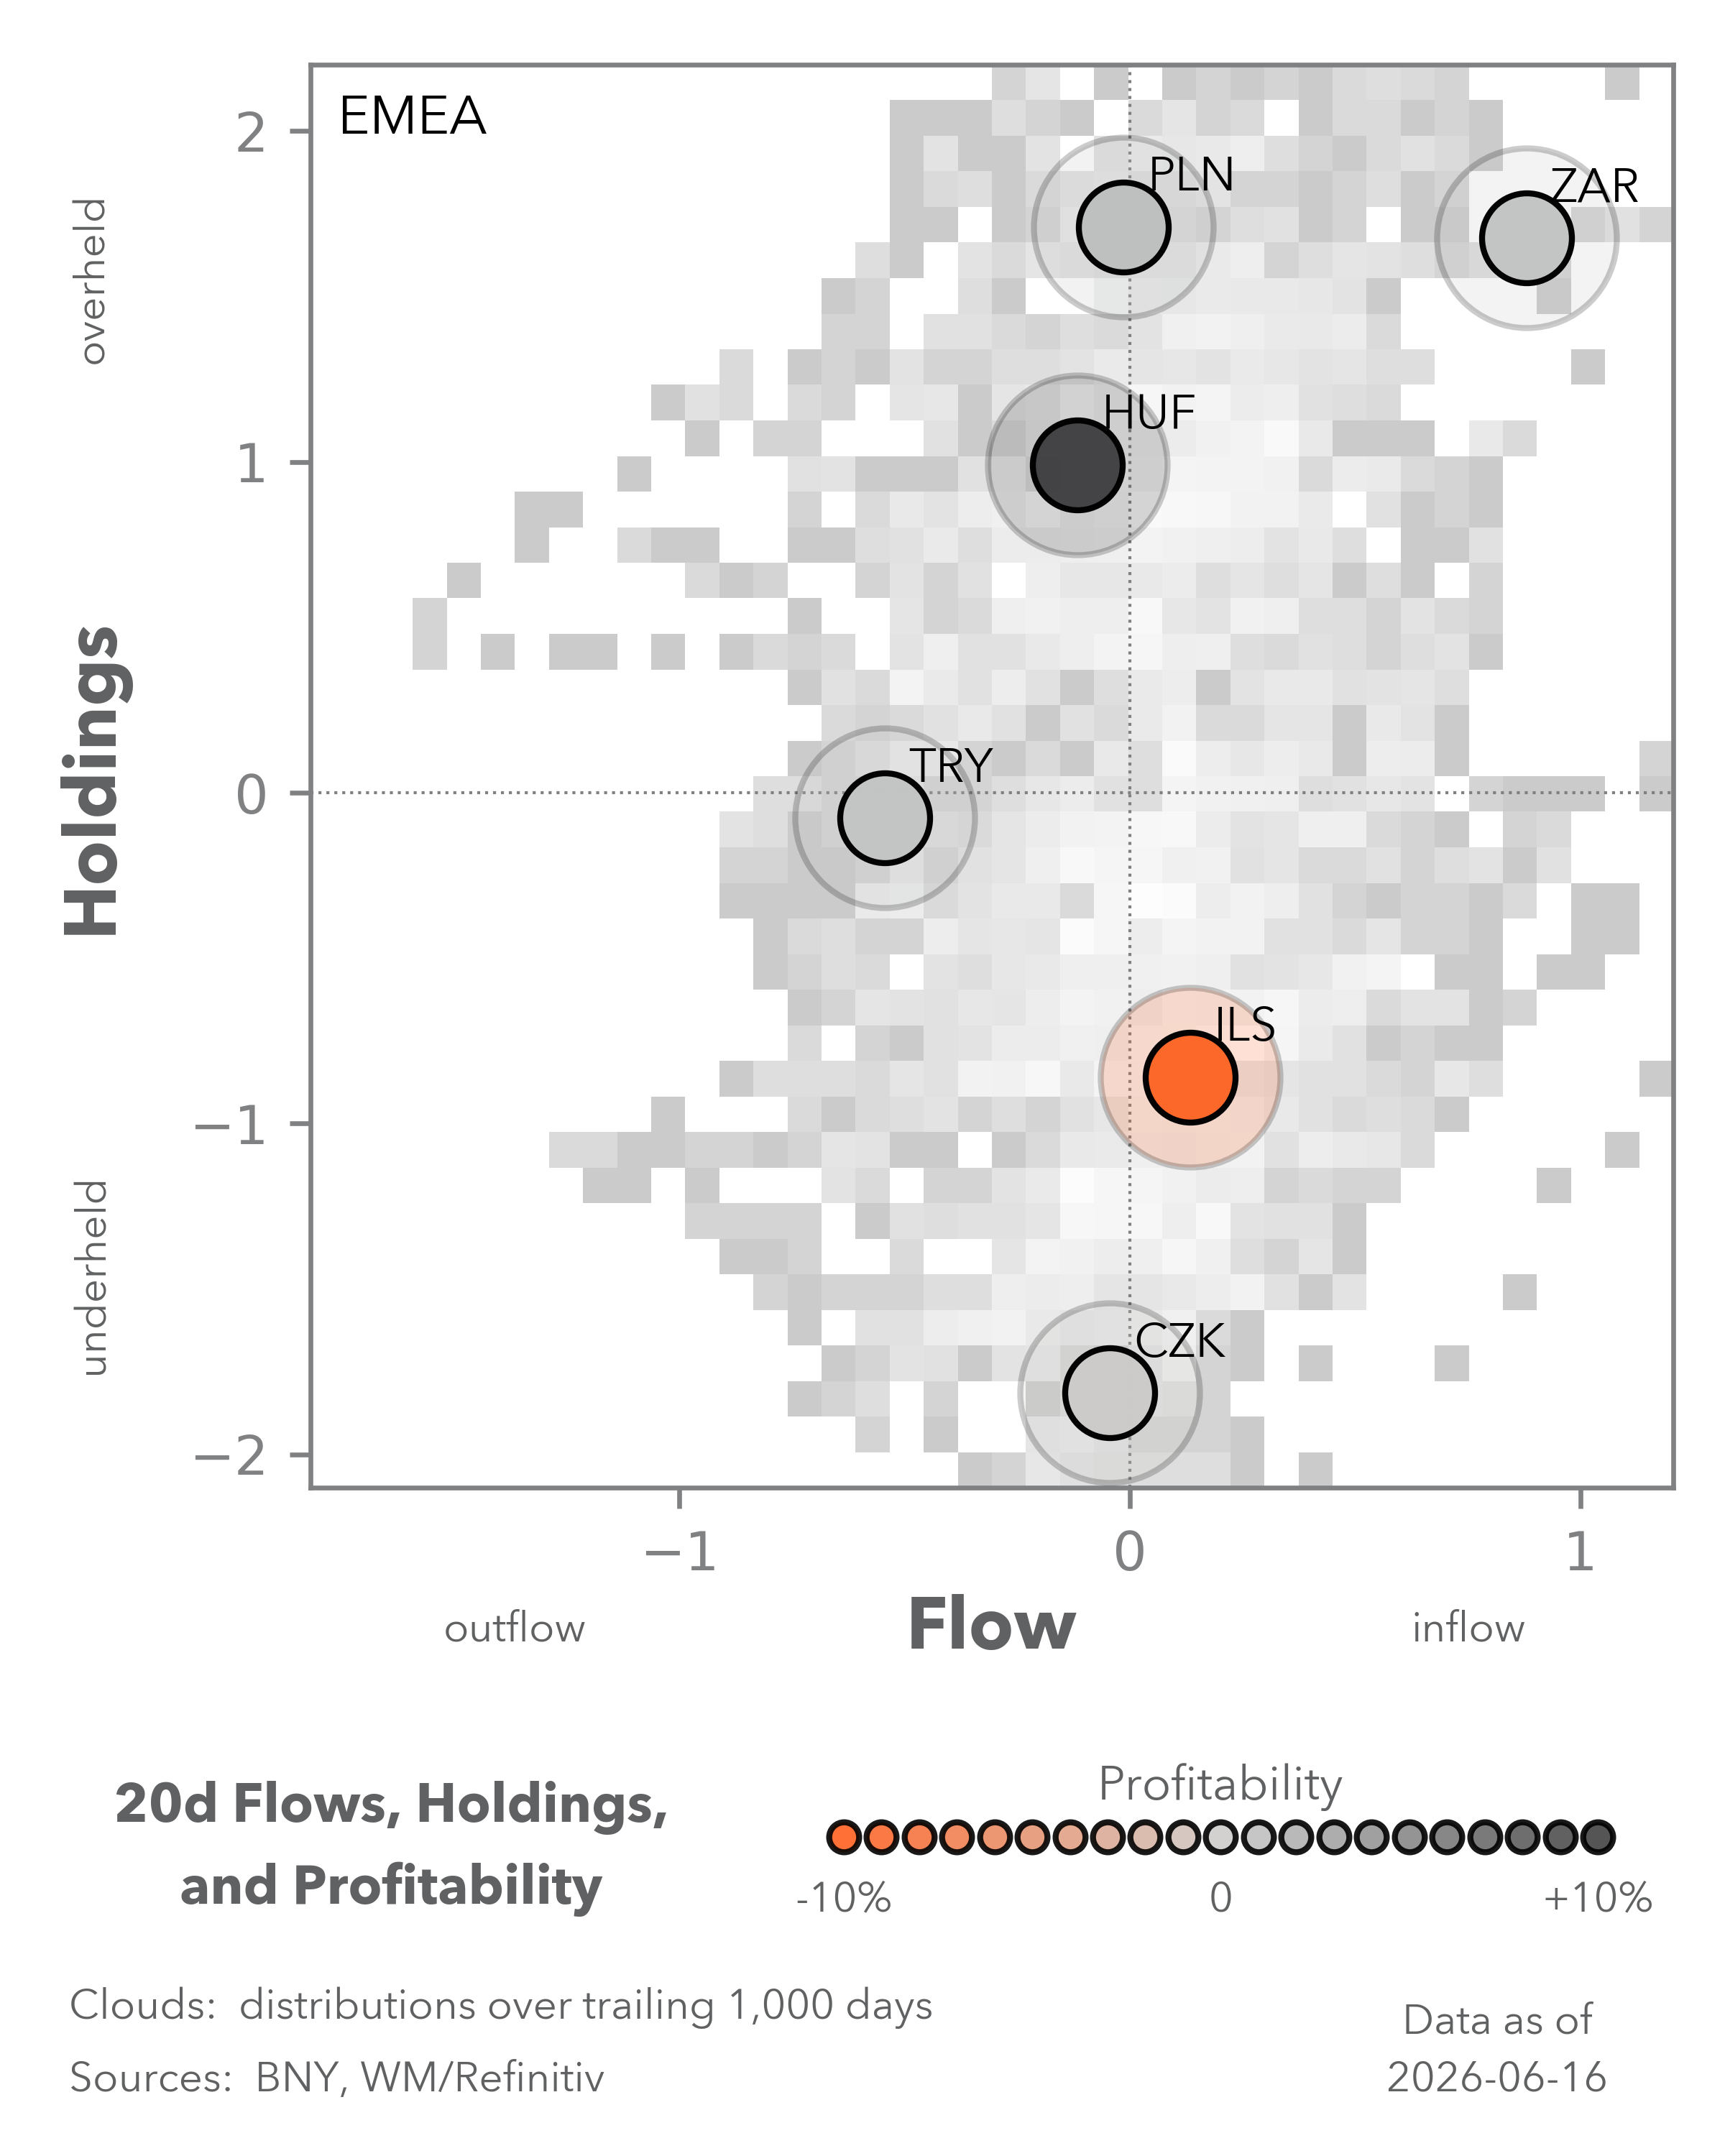
The FOMC decision yesterday was challenging for carry trades but we don’t expect a new round of significant liquidation for now, simply because our data indicate that positioning has softened materially over the last quarter. If anything, quarter-end rebalancing could support some recovery, especially for currencies that faced serious upward inflation pressure from balance-of-payments deterioration. Indonesia, India and South Africa have seen significant liquidation flow, and we don’t expect any central bank in their position to move away from strong vigilance. However, in the sense that markets can “do the tightening” for central banks (which is Bank of England Governor Andrew Bailey’s rationale for not moving more aggressively), some relief is on the way if the ceasefire proves durable. From its peak, forward implied yields have fallen materially for India, while they appear to have peaked in ZAR and IDR. Less stress on the currency and lower interbank rates will help loosen financial conditions (Exhibit 3).
Forward look
For affected central banks, changing policy stances so early into a relief rally risks pushing financial conditions excessively low in a dollar ascendancy phase and re-introduce inflation or exchange rate risk. Finding the right balance is essential, which means doubling down on policy credibility in the near term and relying on balance of payments to do the adjusting. There is also the risk of continuing fiscal loosening as absolute cost levels remain high, which also requires central banks to offset. After all, the best phases of FX carry trades were anchored by hawkish central banks pushing back against fiscal largesse. As the dollar was weakening, EM could sometimes look past excesses in the latter, but the current environment is completely different due to the risk of higher U.S. rates. Until supply is fully normalized, central banks shouldn’t read falling implied yields as a signal to ease. The hawkish lean is what protects currency recoveries.