Euro pass-through a regional risk factor
FX: G10 & EM provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.

Geoff Yu
Time to Read: 4 minutes
Bottom line: Import price pass-through is becoming a more important policy constraint across CEE and the Nordics. Poland and Sweden face the clearest near-term hawkish risk as currency weakness compounds imported inflation, while Norway’s stronger terms of trade and NOK performance provide a larger buffer. Rate-cut expectations, therefore, look increasingly vulnerable, particularly in Poland.
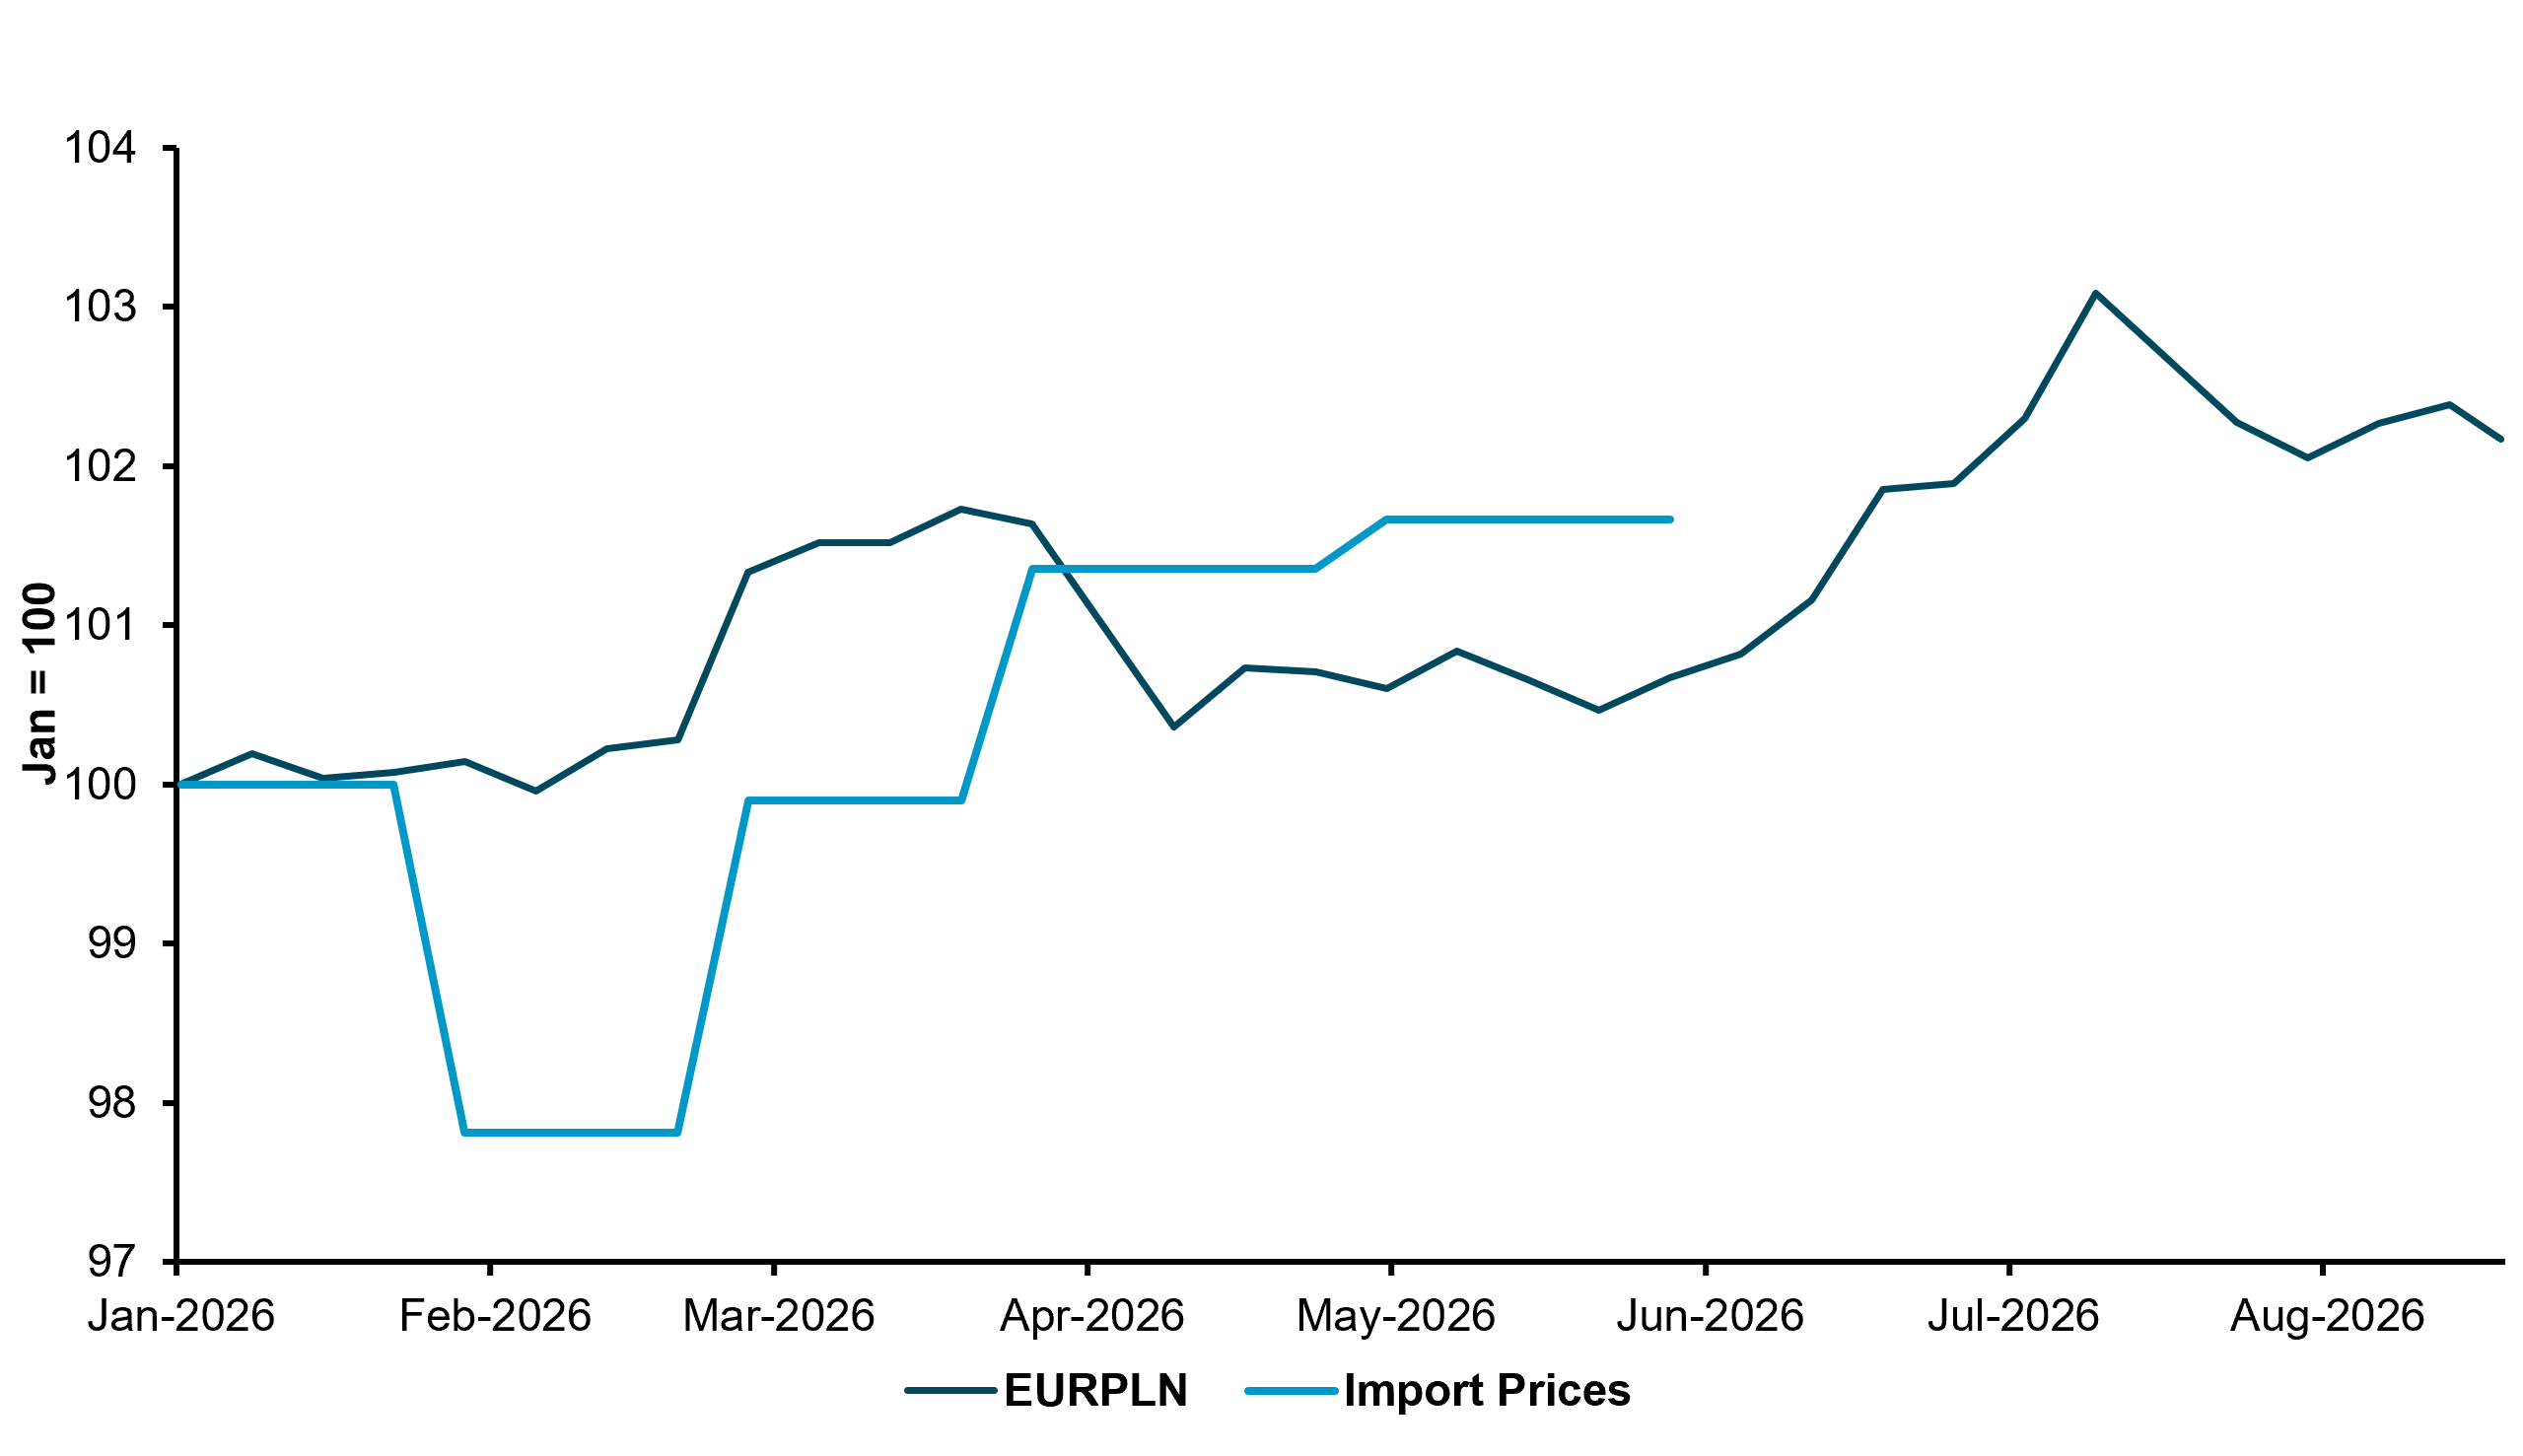
EXHIBIT #1: EURPLN VS. POLAND IMPORT PRICE INDEX
Source: BNY, Bloomberg
Our take
We see the recent bounce in the EUR as largely driven by changes in U.S. real yields. Pass-through relief will be helpful for the ECB, which leads us to question the need for ongoing hawkishness by some Governing Council members, such as Isabel Schnabel, who on Wednesday clearly pushed for another hike. As cyclical conditions improve for the Eurozone, there will be tailwinds for growth and reflation for key local trading partners, such as the Nordics and Central and Eastern Europe.
The benign outlook may lead to unintended consequences. A stronger euro and reflation are normally healthy, but in the near term, risks exacerbate some of the inflation risk arising from supply shocks. Due to supply chain linkages, pass-through remains very strong across Europe, and recent moves in the euro lead to some additional hawkish risk in policy pricing. For example, Poland has not enjoyed the “re-rating shock” in Hungary, which generated policy-neutral inflows. The latest data show that between March and May, import prices have increased materially even without significant upward moves in EURPLN (Exhibit #1). The risks of a further gain through Q3 are stronger, as EURPLN has made significant gains.
Forward Look
The current policy setup faces challenges. The Monetary Policy Council envisages no change in interest rates for the rest of the year, but forward pricing suggests rates need to move back above 4%. Much will hinge on the ECB. It is manageable for the NBP to allow for June’s precautionary move, but the risk of a more sustained cycle will require a catch-up. Meanwhile, fiscal impulse remains strong, which can amplify domestic demand, a dynamic that is not helpful in a rising import price environment. At the very least, cuts need to be taken off the agenda entirely.
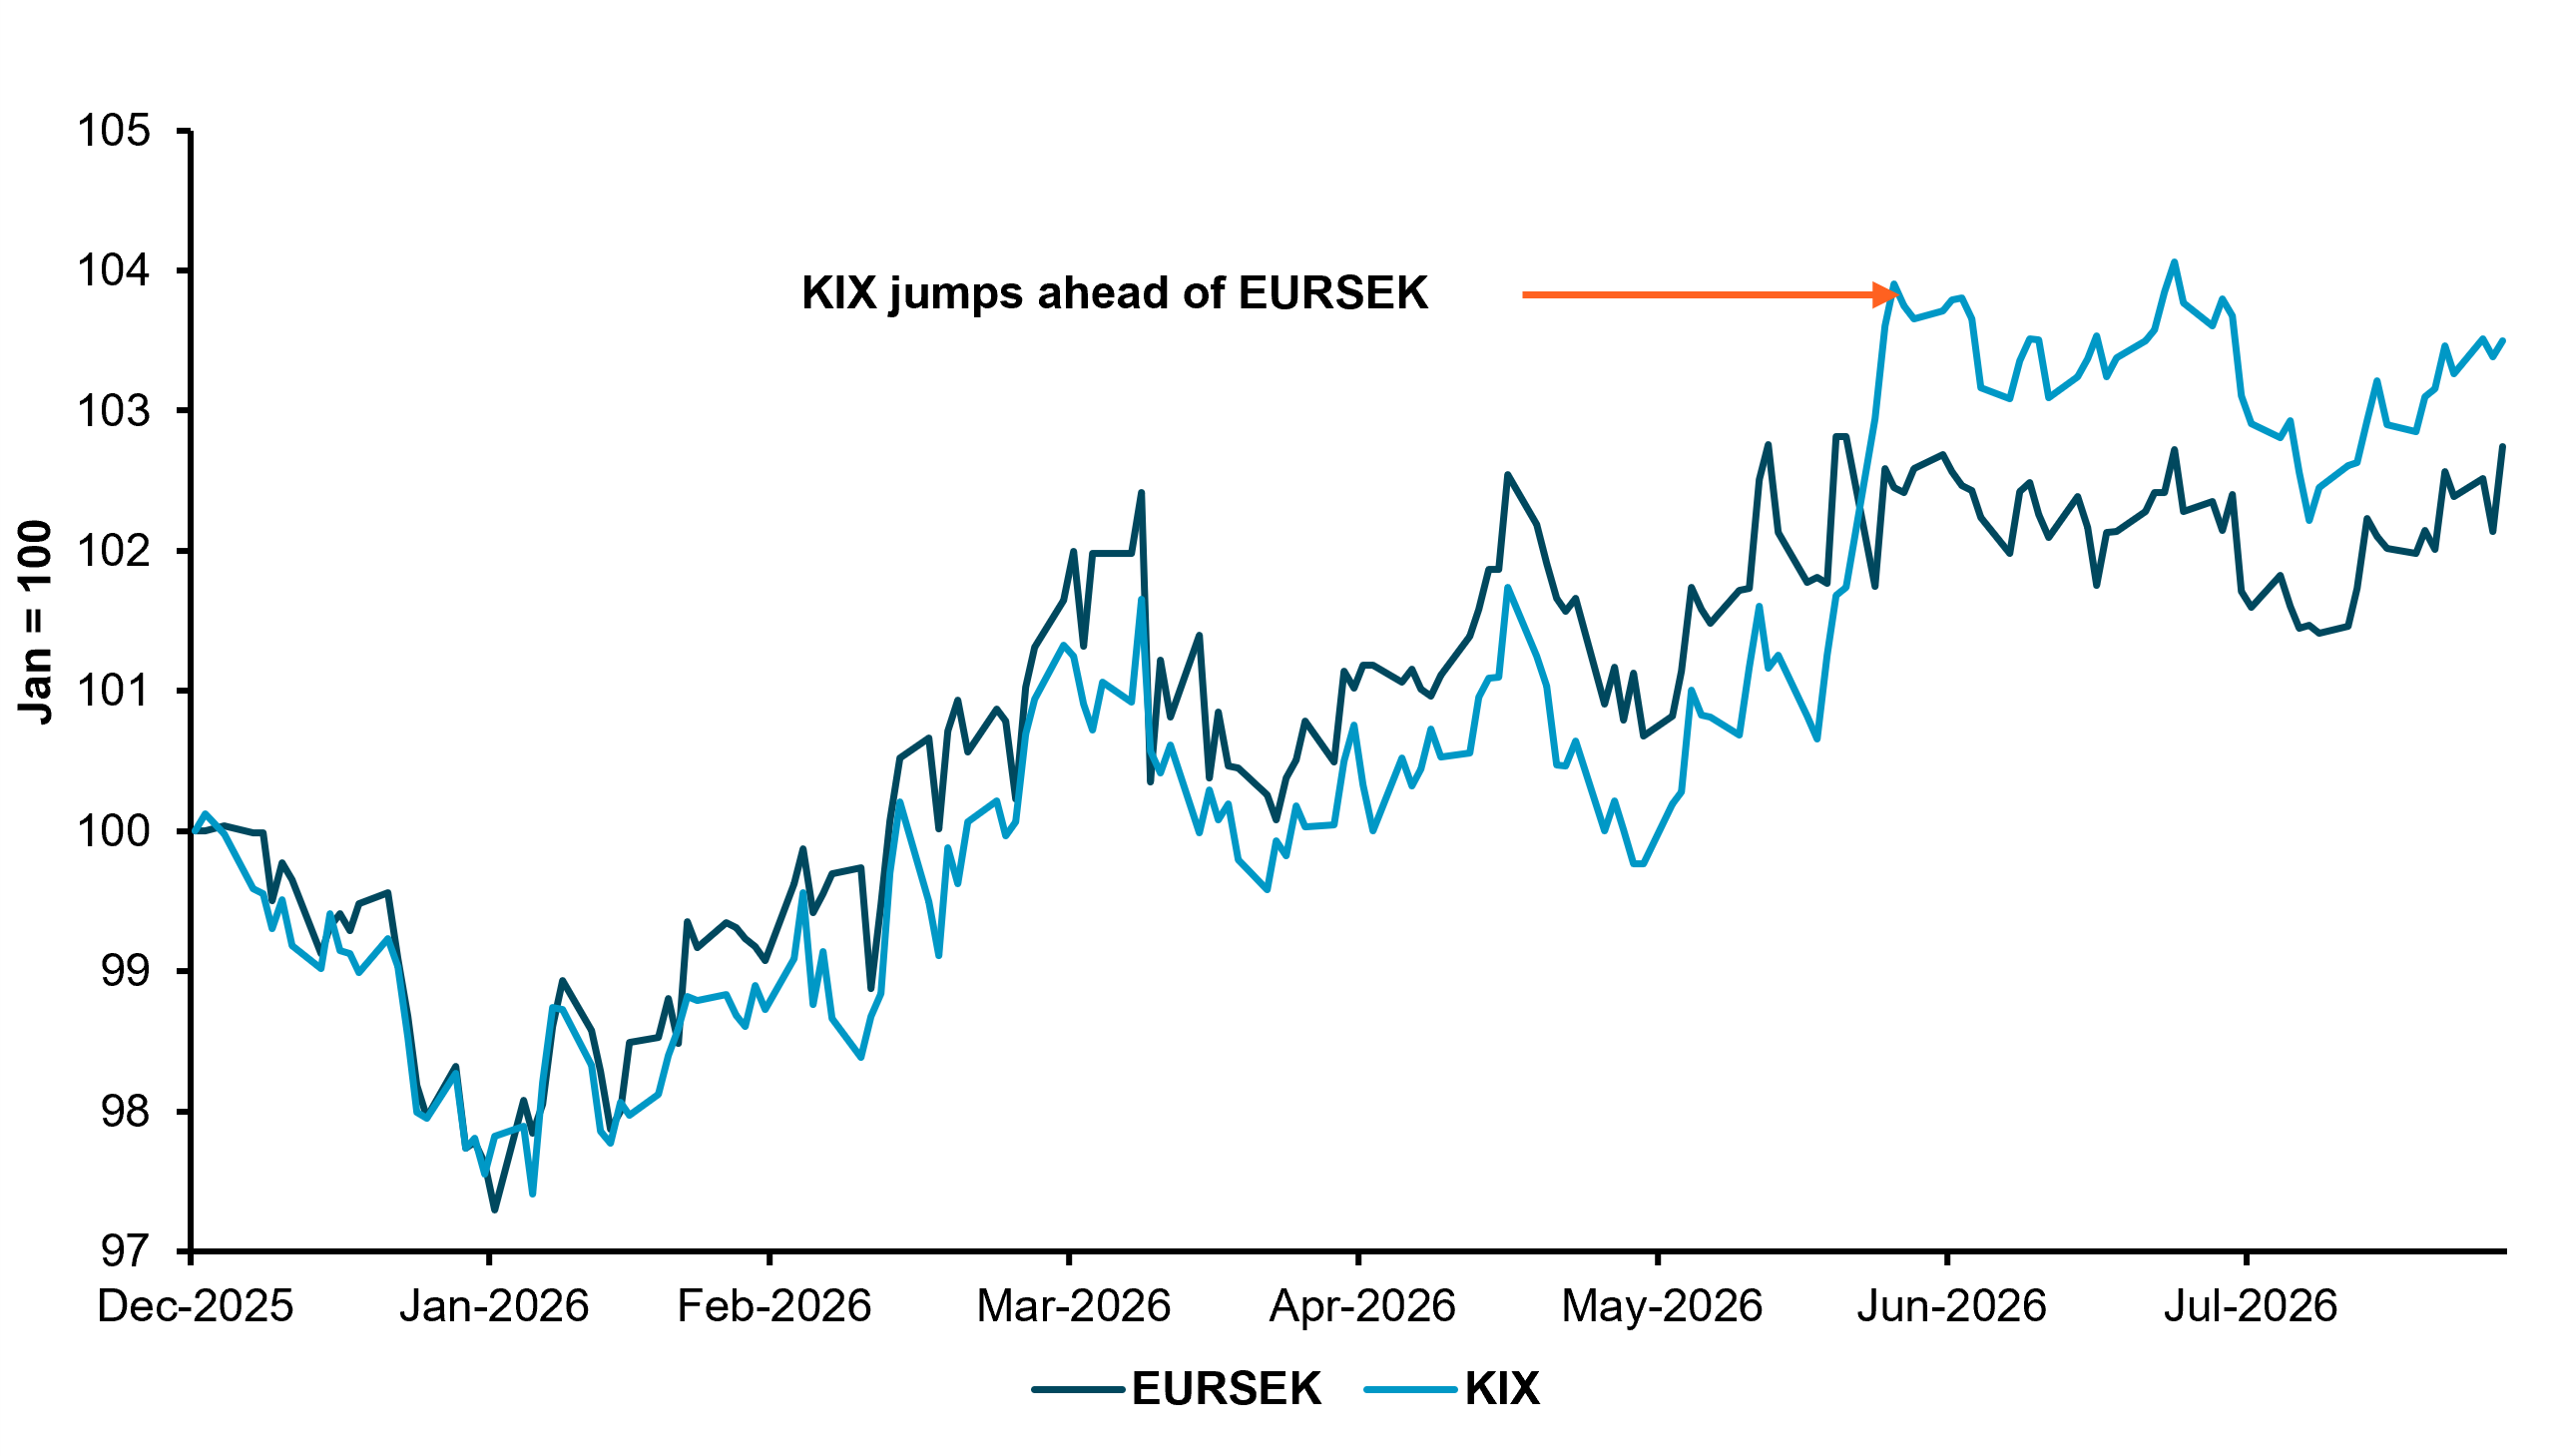
EXHIBIT #2: KIX IMPORT PRICE INDEX VS. EURSEK, YEAR-TO-DATE
Source: BNY, Riksbank
Our take
We remain perplexed by the market’s reaction to the August Riksbank decision. Price action suggests the policy board's decision was dovish, but Governor Erik Thedéen made it clear that the next step remains a hike. The notion that the decision was not “clear cut” does indeed cut both ways, and we assign an equal risk that current tightening in the repo rate forecast could be moved forward, as “clear upward momentum” exists in inflation.
There is a risk that headline inflation in Sweden will catch up swiftly, compounding the risks from core inflation. Throughout the conflict, regulated prices have helped limit transmission from external inputs, leaving Sweden with some of the lowest headline inflation rates in Europe. However, import prices are clearly starting to catch up, and some pass-through is inevitable. EURSEK price action has not helped, but it is particularly worrying that the KIX import price index – which the Riksbank tracks – has already jumped well ahead of the exchange rate. In the past, alternating dollar and euro strength helped even out price action, but the current jump suggests SEK is being treated as a funding currency, which requires a strong offset.
Forward Look
The Riksbank has been forceful on SEK valuations in the past. It is one of the few central banks in the G10 that openly seeks a stronger exchange rate to help achieve its inflation objectives. With the KIX repeatedly missing projections and adding to inflation risk, we expect more forceful language up ahead at a minimum, which in time can lead to policy surprises. Presently, a full hike is not expected until next year; risk reward favors moving the timeline forward.
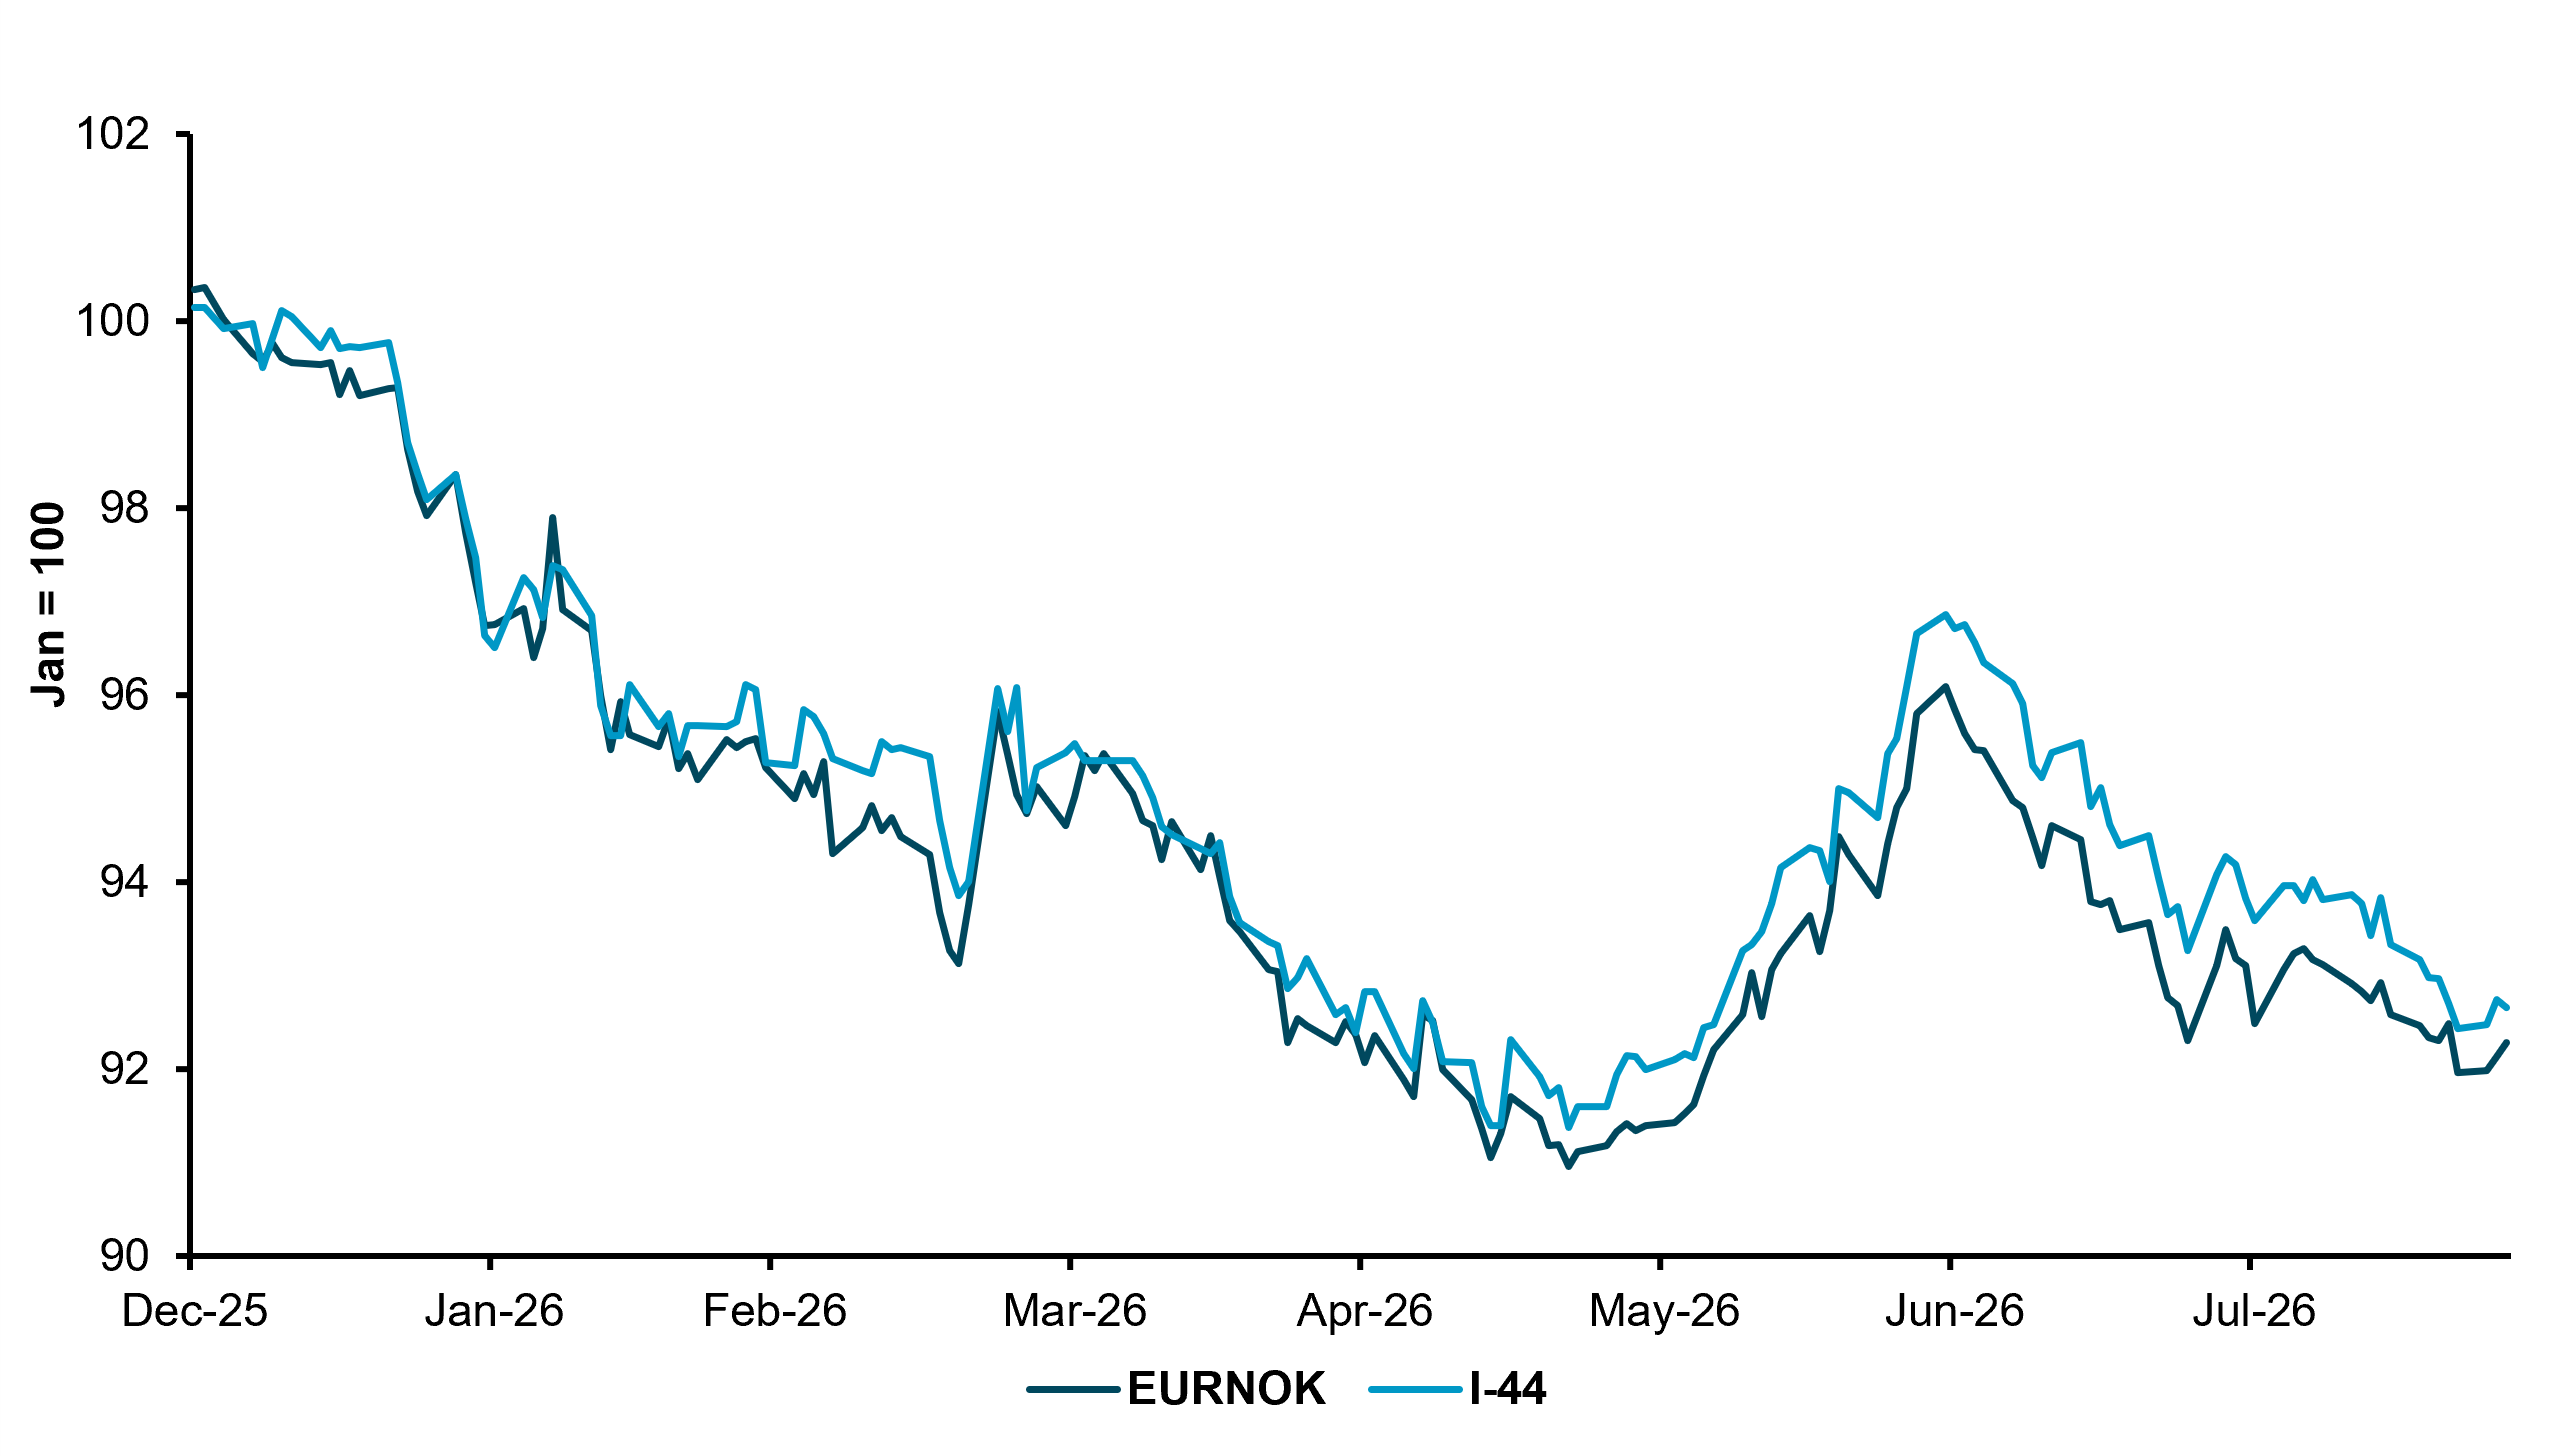
EXHIBIT #3: : I-44 IMPORT PRICE INDEX VS. EURNOK
Source: BNY, Norges Bank
Our take
The surge in oil prices this year generated a significant terms-of-trade improvement for Norway. The gains are not as strong as the 2022 surge, which means there isn’t a tailwind from central bank sales to generate further NOK weakness. Like other EUR crosses, EURNOK also strengthened materially during Q2, which significantly pushed up the I-44 import price index. There are already signs that Norwegian import prices are following Sweden’s path, where the basket is diverging more from EURNOK itself, raising pass-through risk.
Despite the risks, the strength of NOK performance year-to-date is a robust buffer against inflation figures, allowing Norges Bank to remain fully focused on domestic factors. The energy-dominant nature of current supply shocks means the currency’s reaction function to external factors differs markedly from peers'. Nonetheless, vigilance is necessary, as higher import prices also risk pushing up inflation expectations and generating second-round effects that Norges Bank must respond to.
Forward look
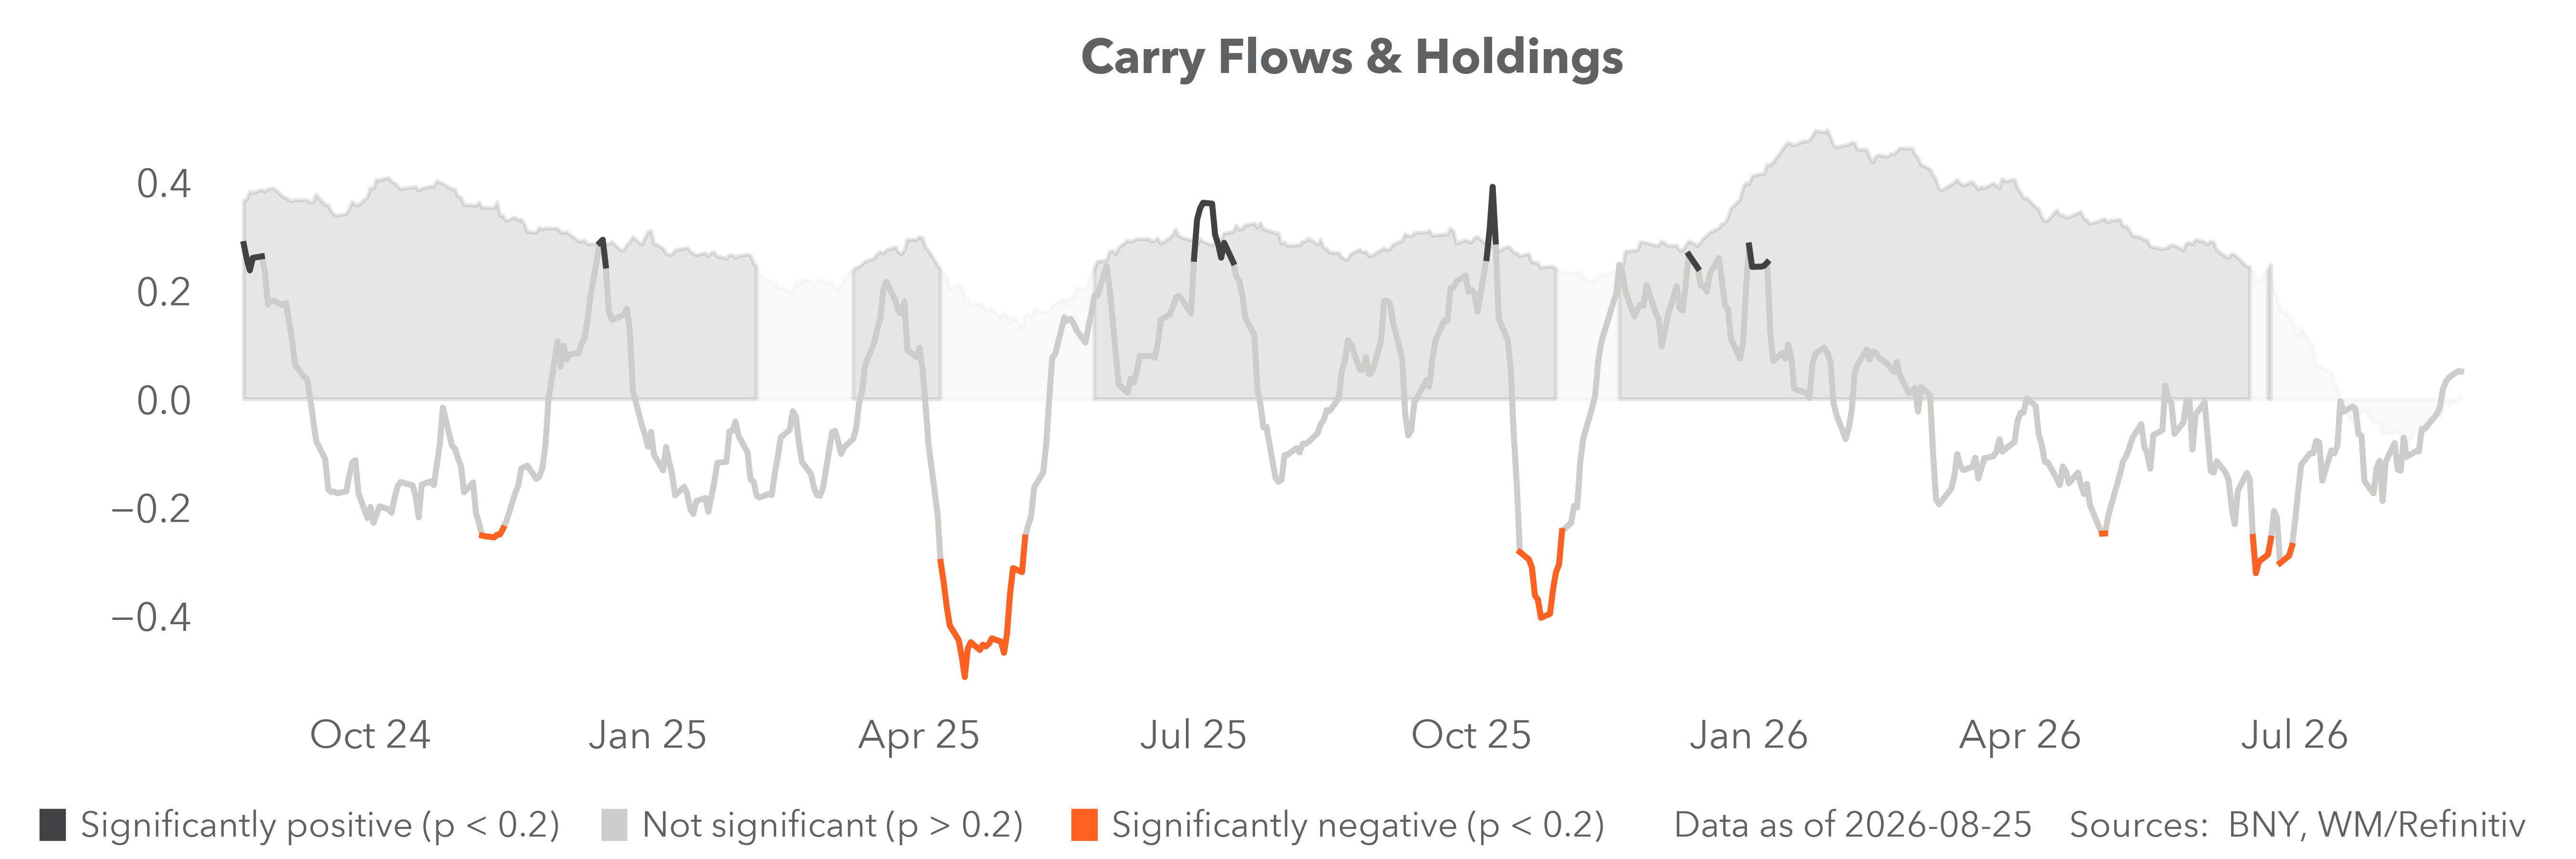
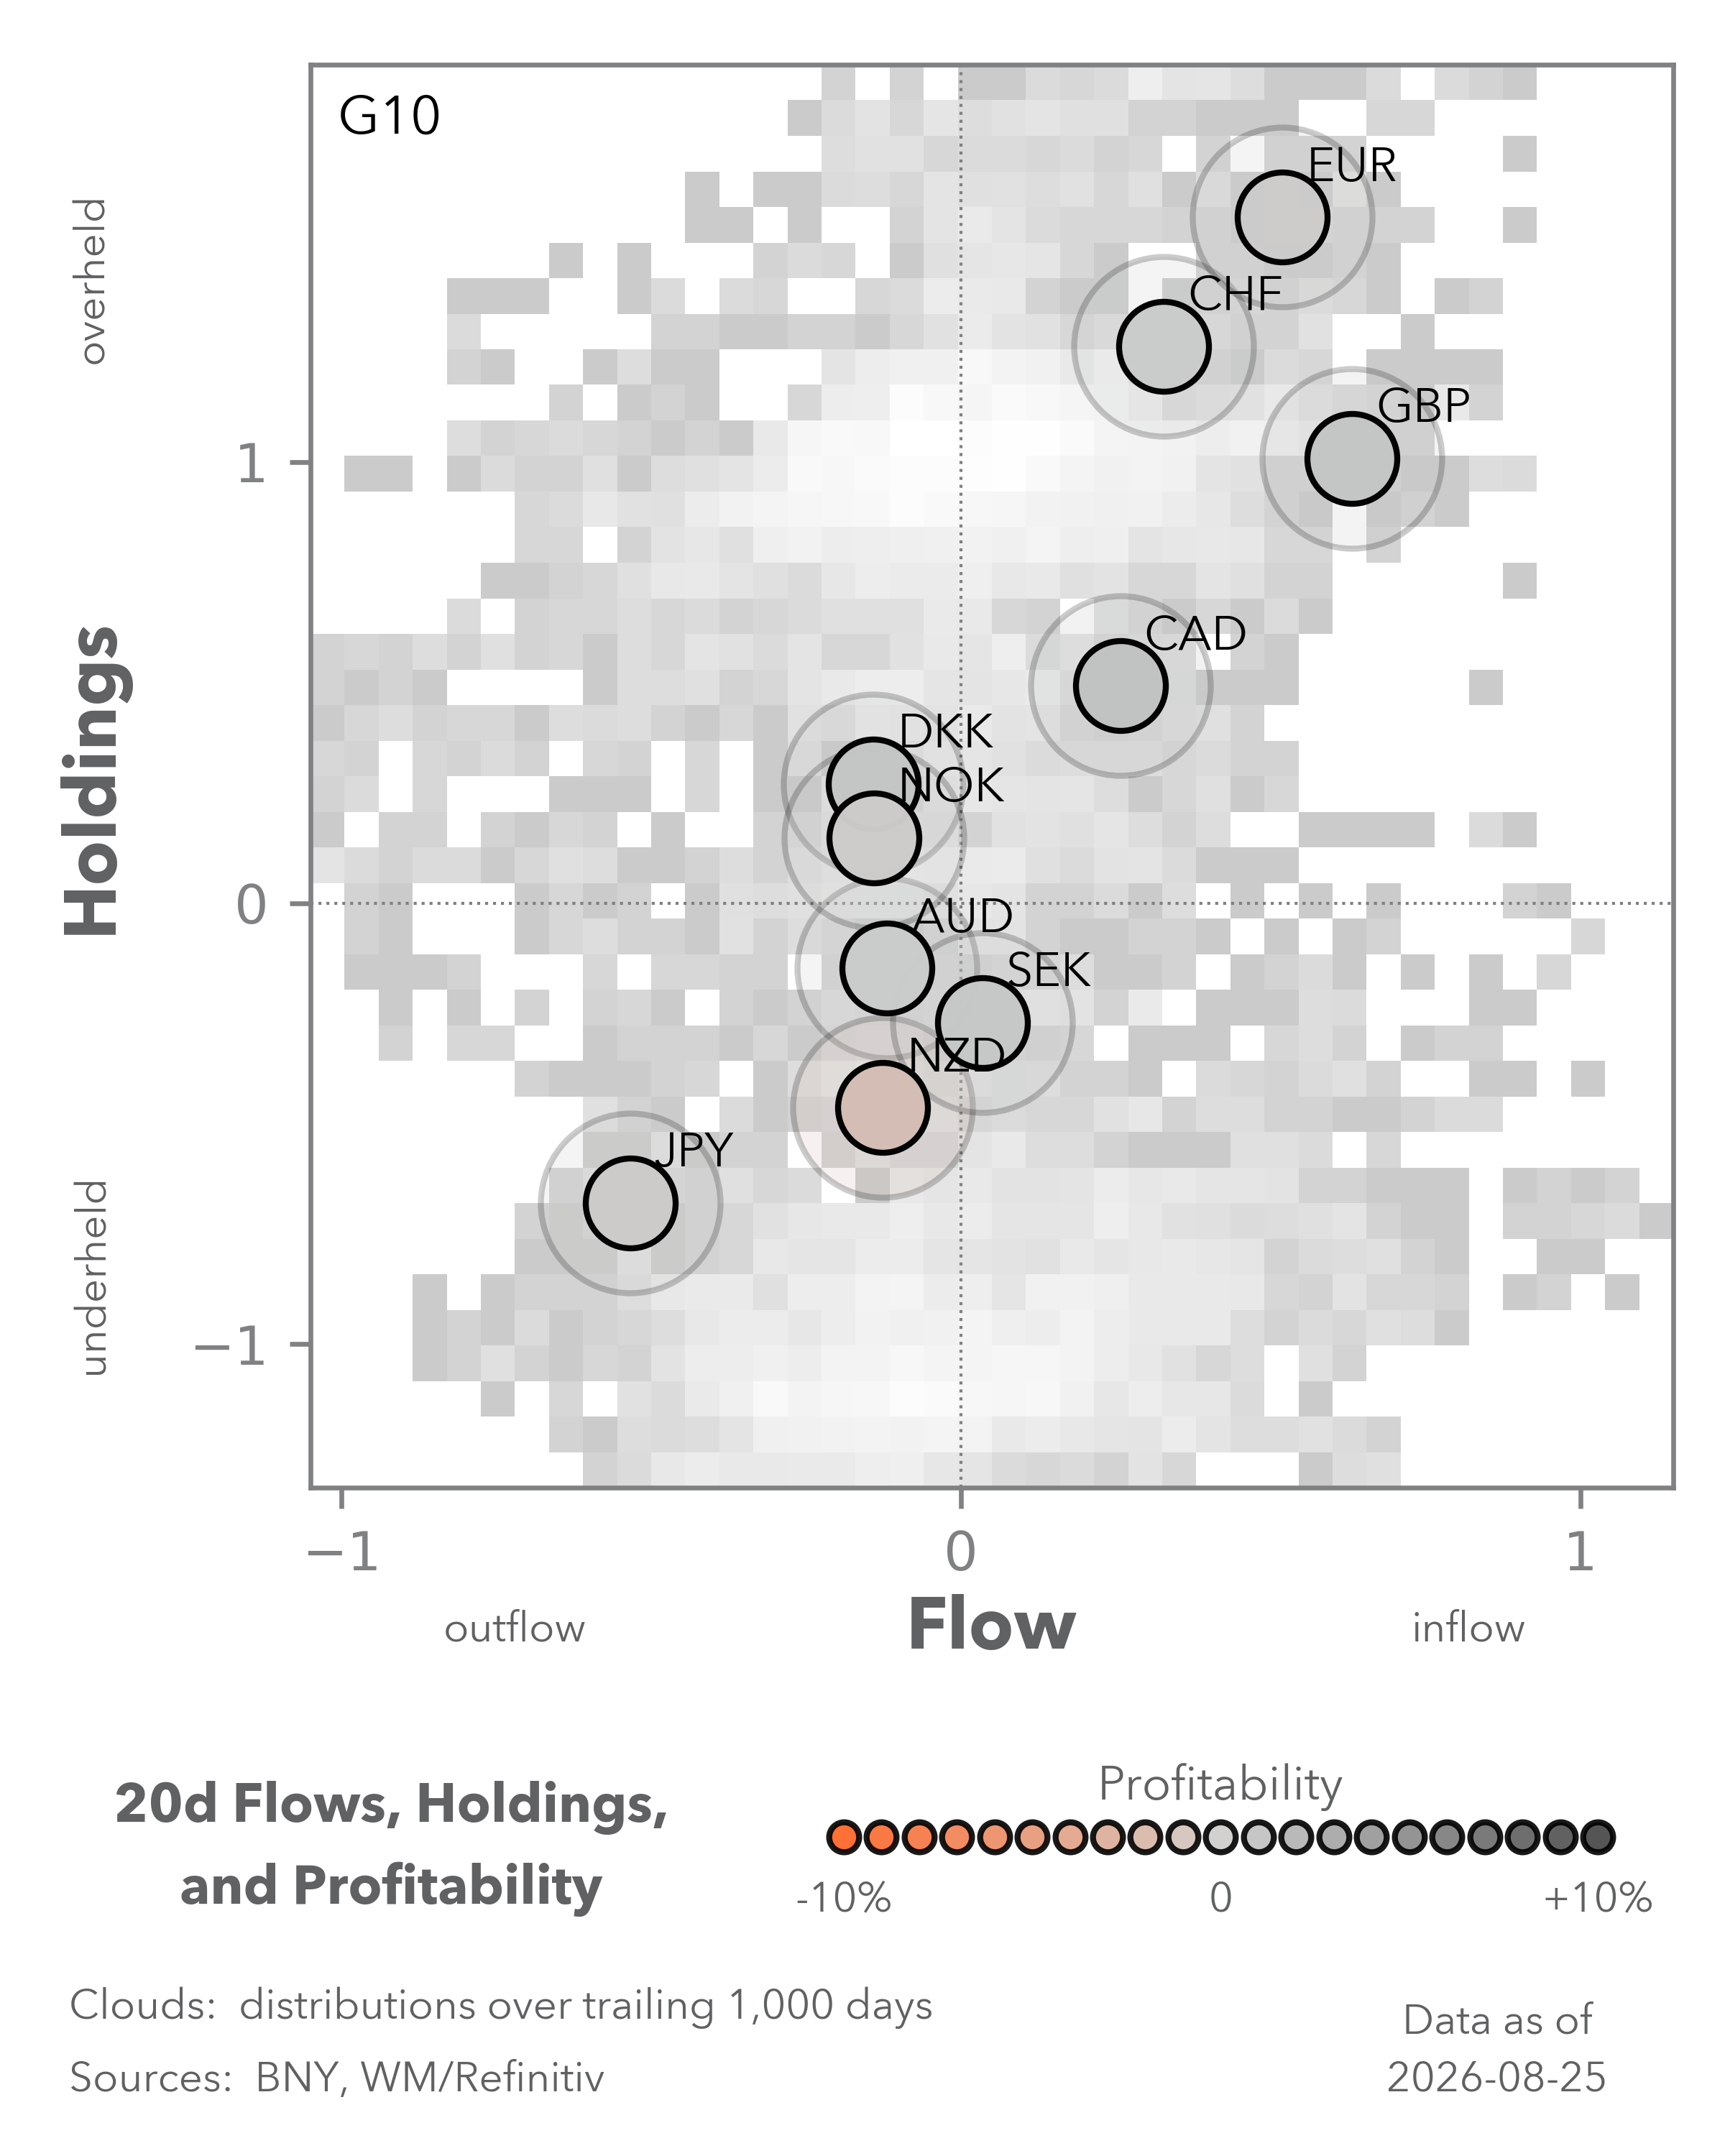
Risk reward is poor to be short EURNOK. Compared to the likes of PLN and SEK, the valuation case for NOK is far weaker. We also highlight that our data point to very high-level holdings of NOK relative to G10 peers, which is a perennial headwind against further performance. Unlike PLN and SEK, NOK will likely respond far more strongly to domestic triggers, especially wages. Transmission from import costs to labor takes longer, but history shows Norges Bank will react proactively to any such risks.
Position for greater NBP and Riksbank vigilance. Take Polish cuts off the table, favor earlier Riksbank tightening, and treat further upside in EURPLN and EURSEK as increasingly self-limiting. By contrast, avoid chasing NOK strength: domestic inflation and wages matter more, while stretched holdings weaken the case for short EURNOK.