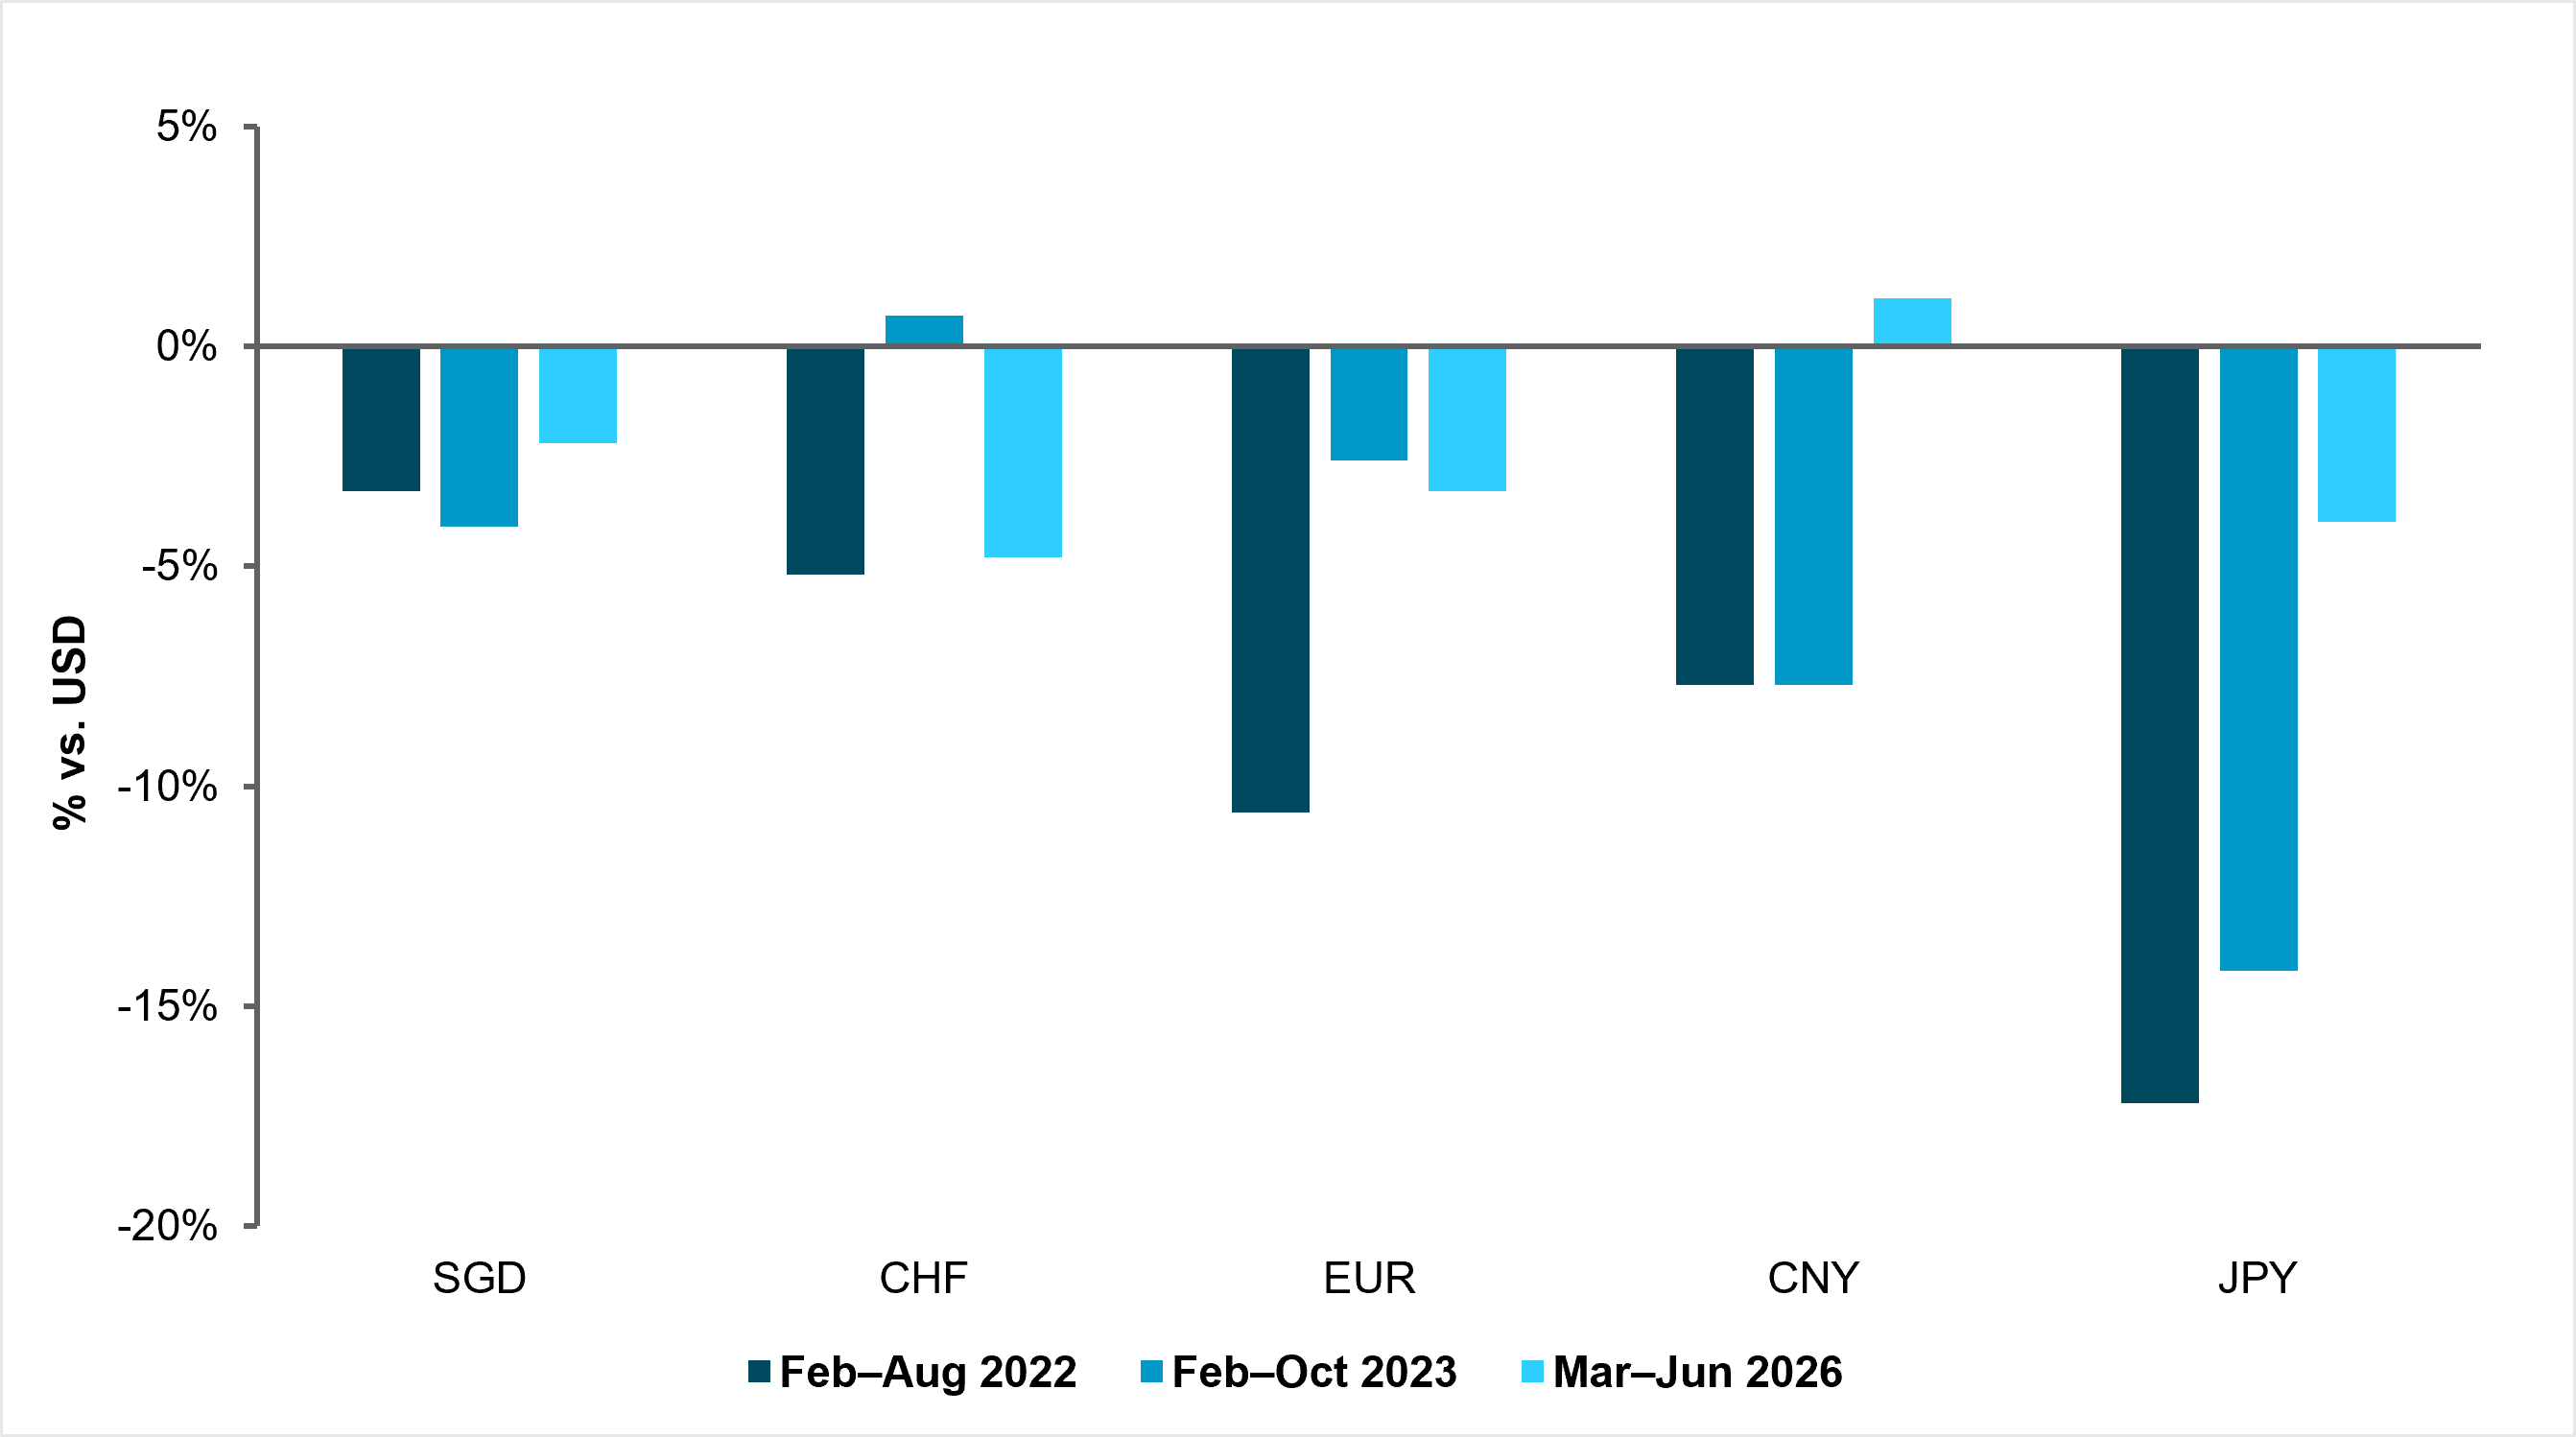Dollar resilience in correlated selloffs
FX: G10 & EM provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
Geoff Yu
Time to Read: 5 minutes
Bottom line: The dollar remains the most reliable defensive currency during correlated bond and equity selloffs, even if it doesn’t always deliver outright outperformance. Traditional “quality” alternatives such as CHF, SGD, and EUR can limit downside, but their protection is inconsistent. Reserve status and relatively high U.S. real yields continue to support the dollar, though any further erosion in Fed credibility or real-rate support would weaken that framework.
EXHIBIT #1: THE DOLLAR HOLDS ITS GROUND WHEN MARKETS FALL TOGETHER
Source: BNY, Bloomberg
Our take
With bond and equity markets increasingly vulnerable to moving lower together, the obvious question is whether FX still offers a reliable source of protection. We therefore examine currency performance against the USD across three recent episodes of simultaneous bond and equity stress: February to August 2022, February to October 2023 and March to June 2026. Returns are measured end-of-month to end-of-month – from January to August 2022, January to October 2023, and February to June 2026. The Fed was in a tightening cycle in the first two episodes, but global peers tend not to diverge strongly during the process.
Across these three episodes, there is little evidence that any major non-dollar currency provides a reliable hedge. Even currencies normally viewed as “quality” or defensive tend to weaken against the USD when both asset classes are under pressure. The main lesson is therefore not which currency wins, but how hard it is to escape dollar strength during broad cross-asset stress.
SGD is the most consistent relative outperformer, losing less than most peers in two of the three episodes and avoiding the double-digit declines seen elsewhere. But it still fell against the dollar in every period. CHF performs better only intermittently: It was the sole gainer in the 2023 episode but subsequently fell 4.8% in the 2026 selloff. CNY tells a similar story from the opposite direction, gaining in 2026 but falling 7.7% in both earlier periods.
EUR has become more resilient since its severe 2022 decline, while JPY is the clearest disappointment, ranking as the worst performer in all three windows – highlighting Japan’s high sensitivity to supply disruptions.
Forward Look
Despite the growing list of dollar-negative catalysts – from the July FOMC to renewed concerns around U.S. fiscal policy and real-rate support – history argues against being aggressively short the greenback as a portfolio hedge. In periods when bonds and equities sell off together, particularly around supply-driven inflation shocks, the USD has remained the most reliable source of protection, while traditional “quality” currencies have offered only inconsistent relative resilience. That doesn’t rule out further dollar weakness in a benign risk environment, but it suggests the asymmetry matters: portfolios positioned for a correlated cross-asset selloff should be cautious about carrying large structural USD shorts. In that scenario, retaining some dollar exposure may still be the cleaner defensive position.
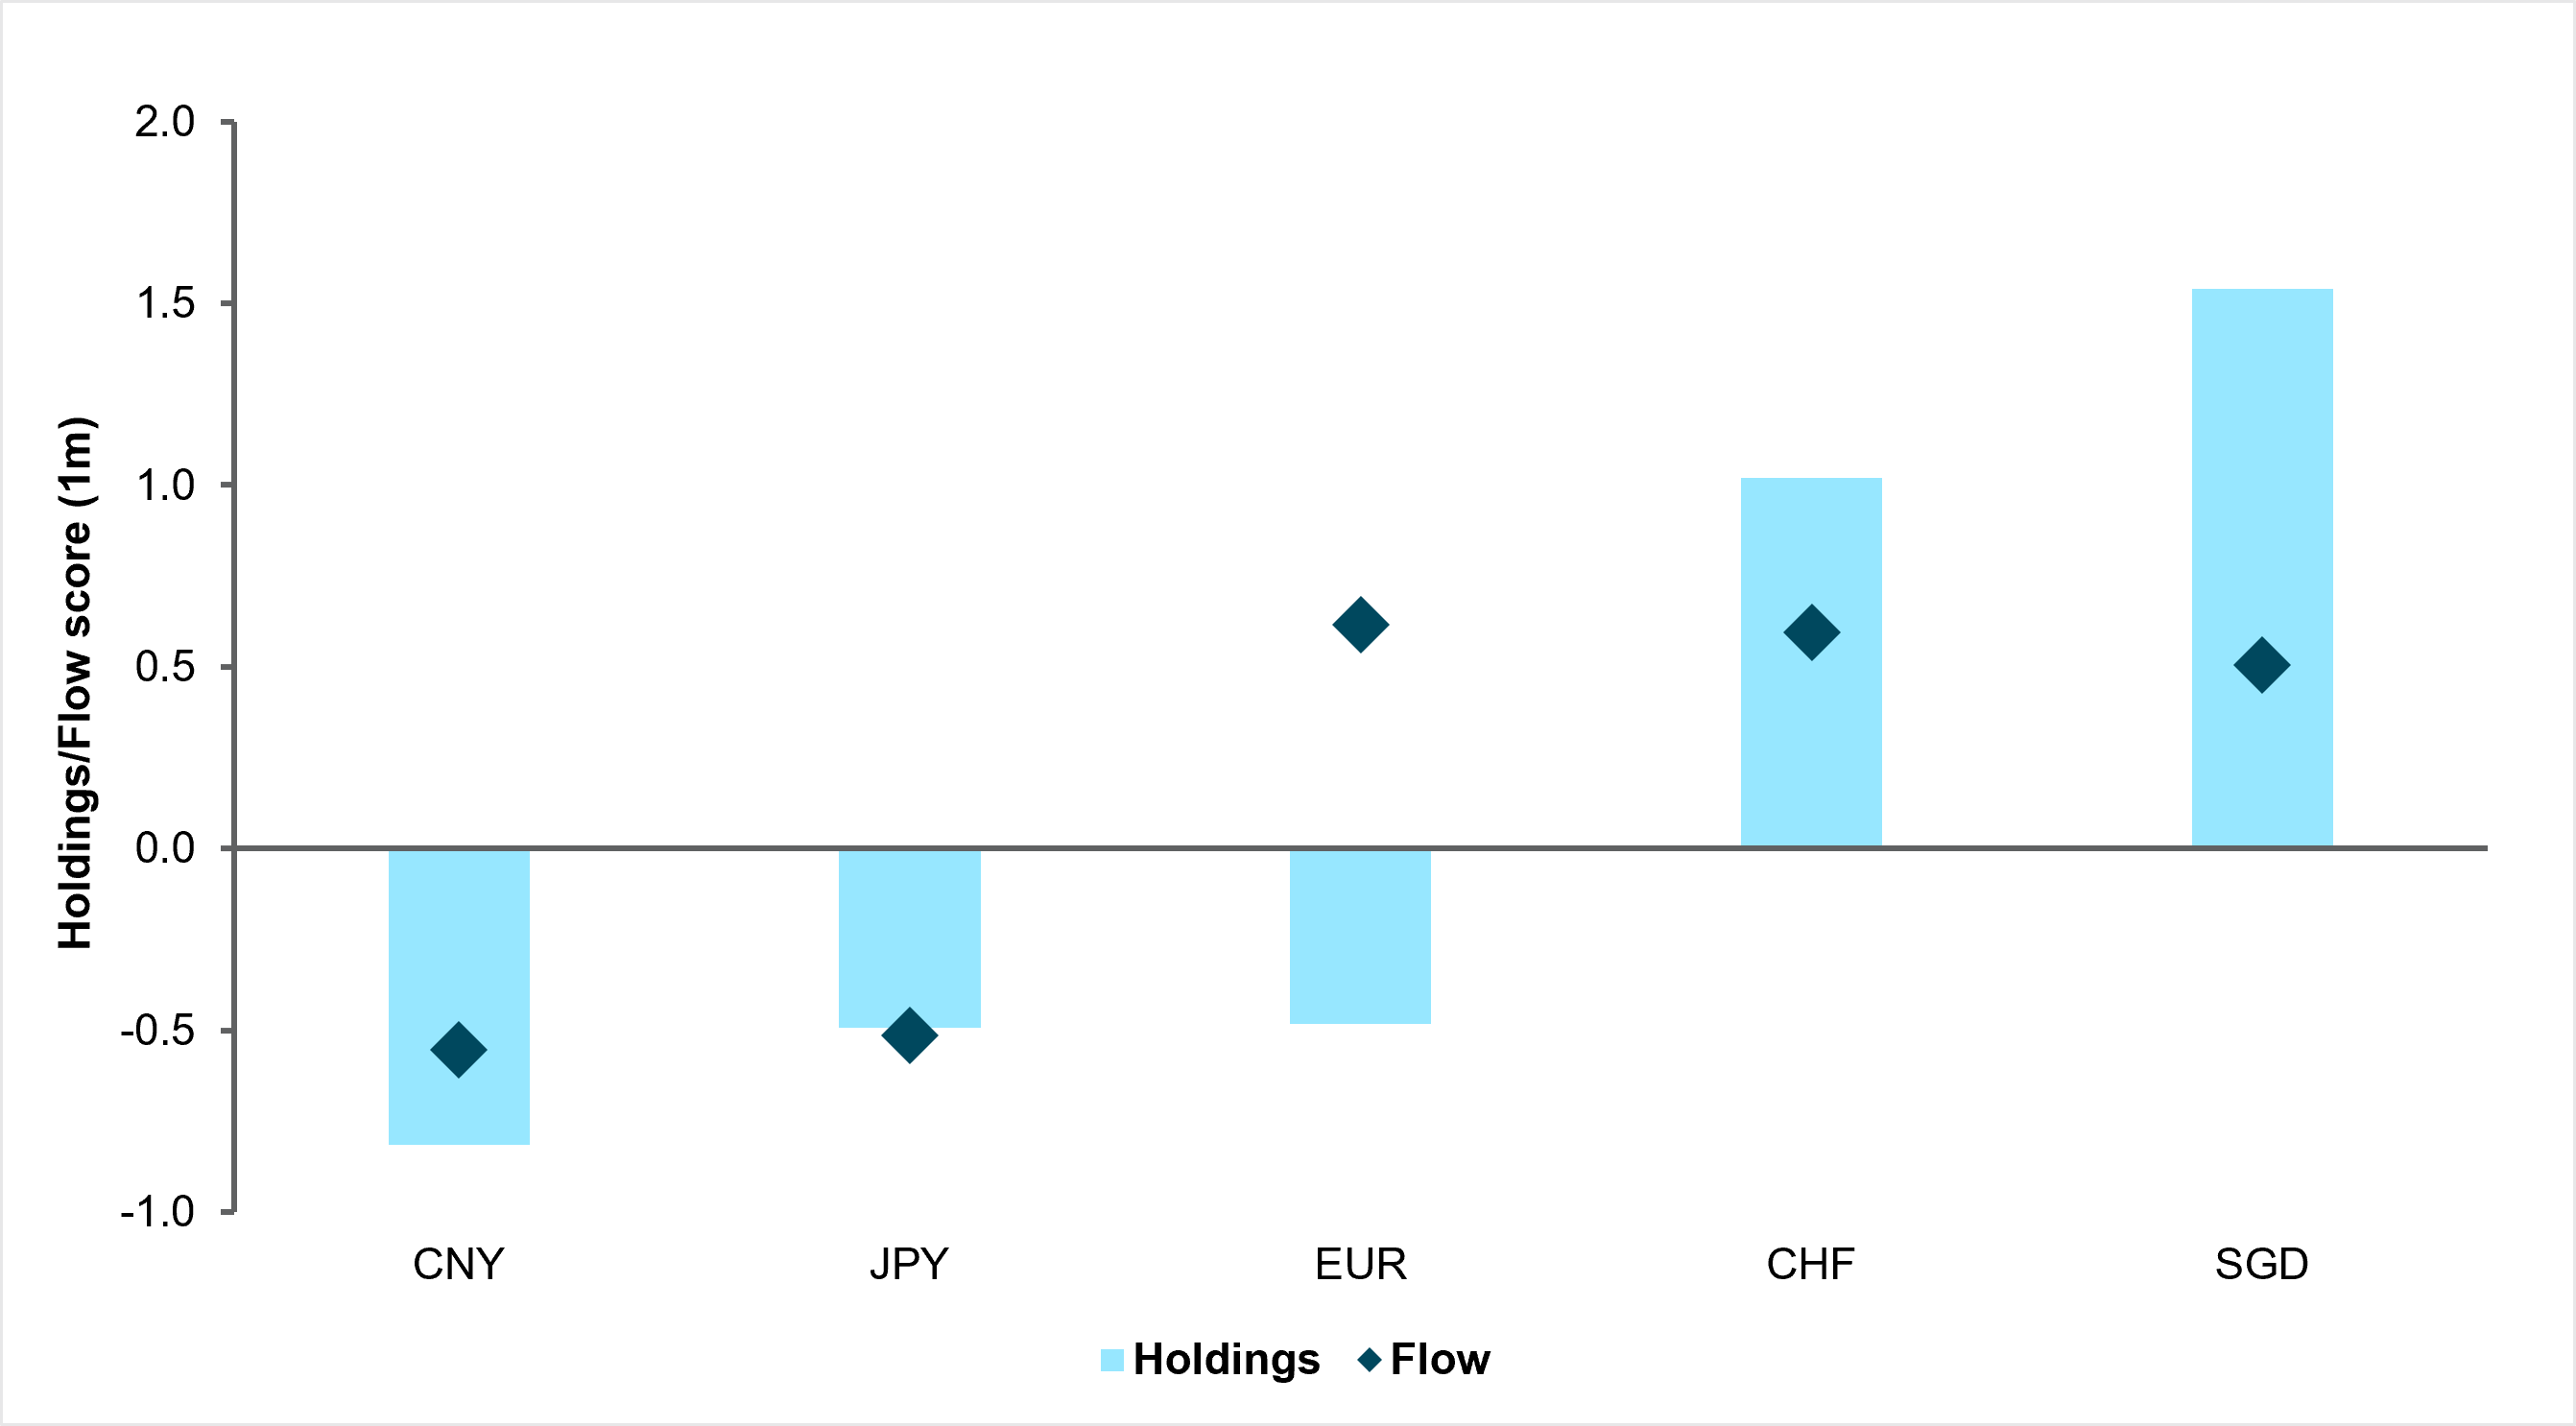
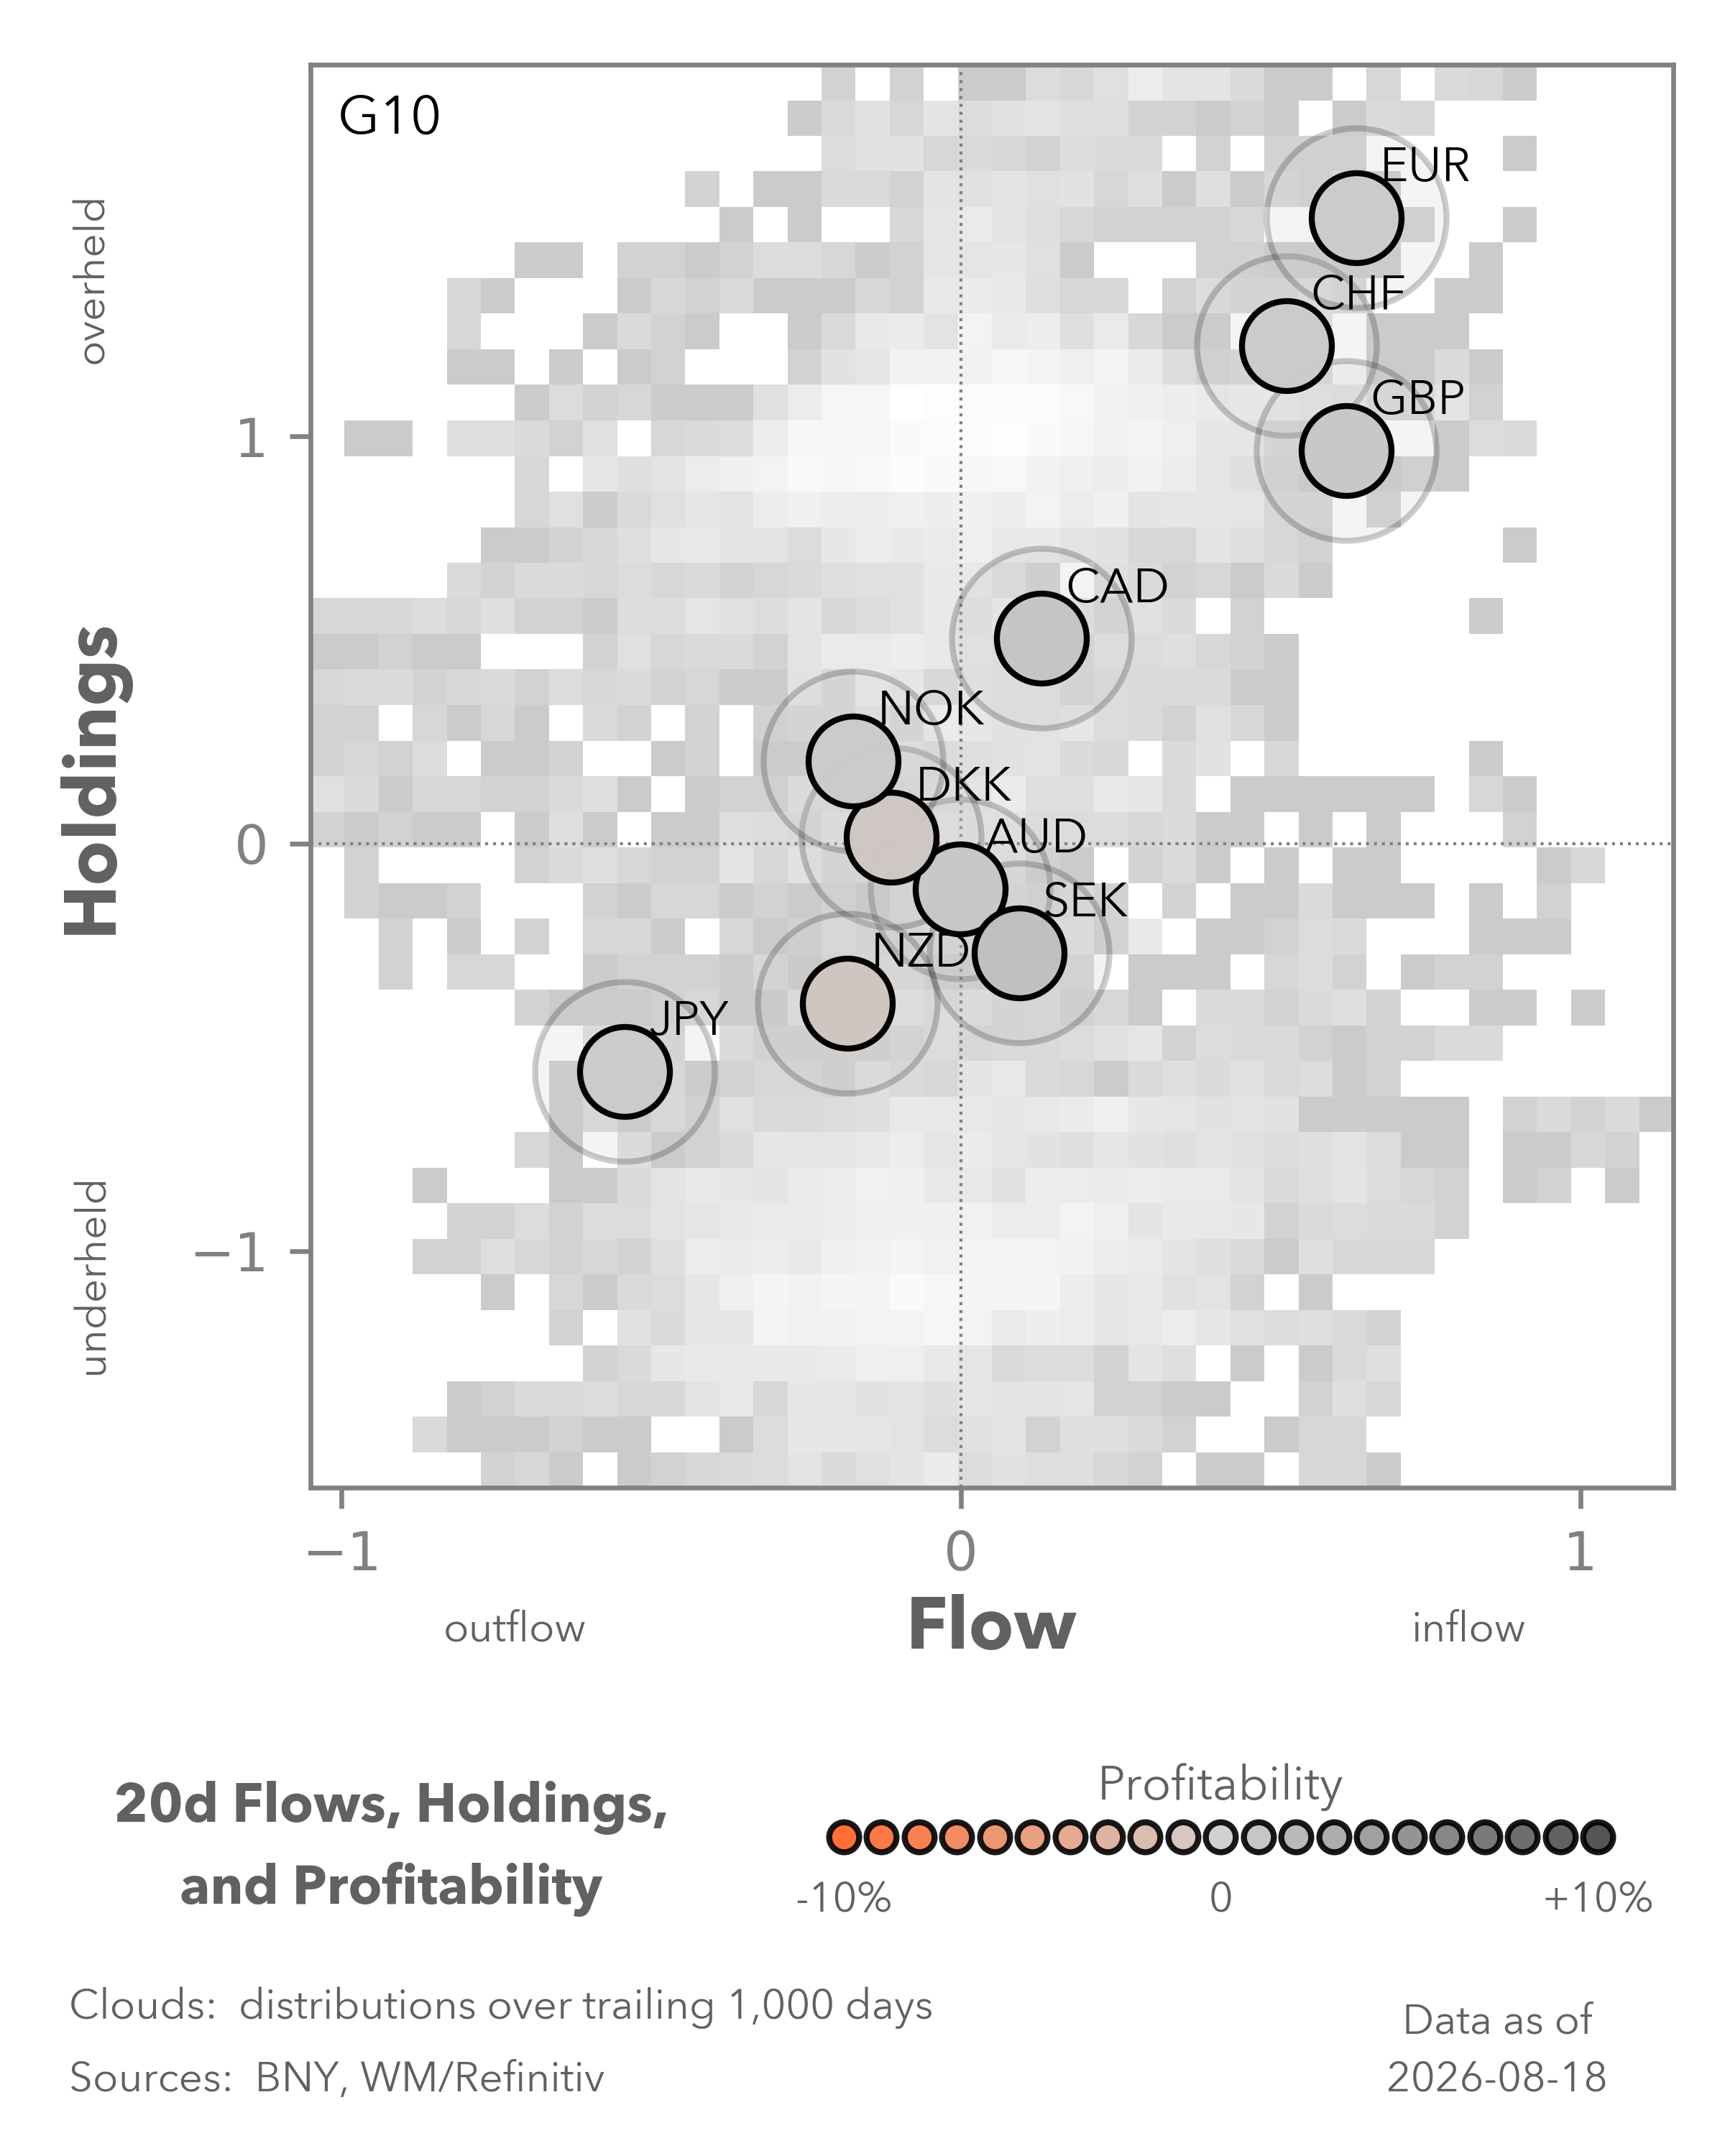
EXHIBIT #2: IFLOW HOLDINGS FOR “QUALITY” NAMES AND FLOW OVER THE PAST MONTH
Source: BNY
Our take
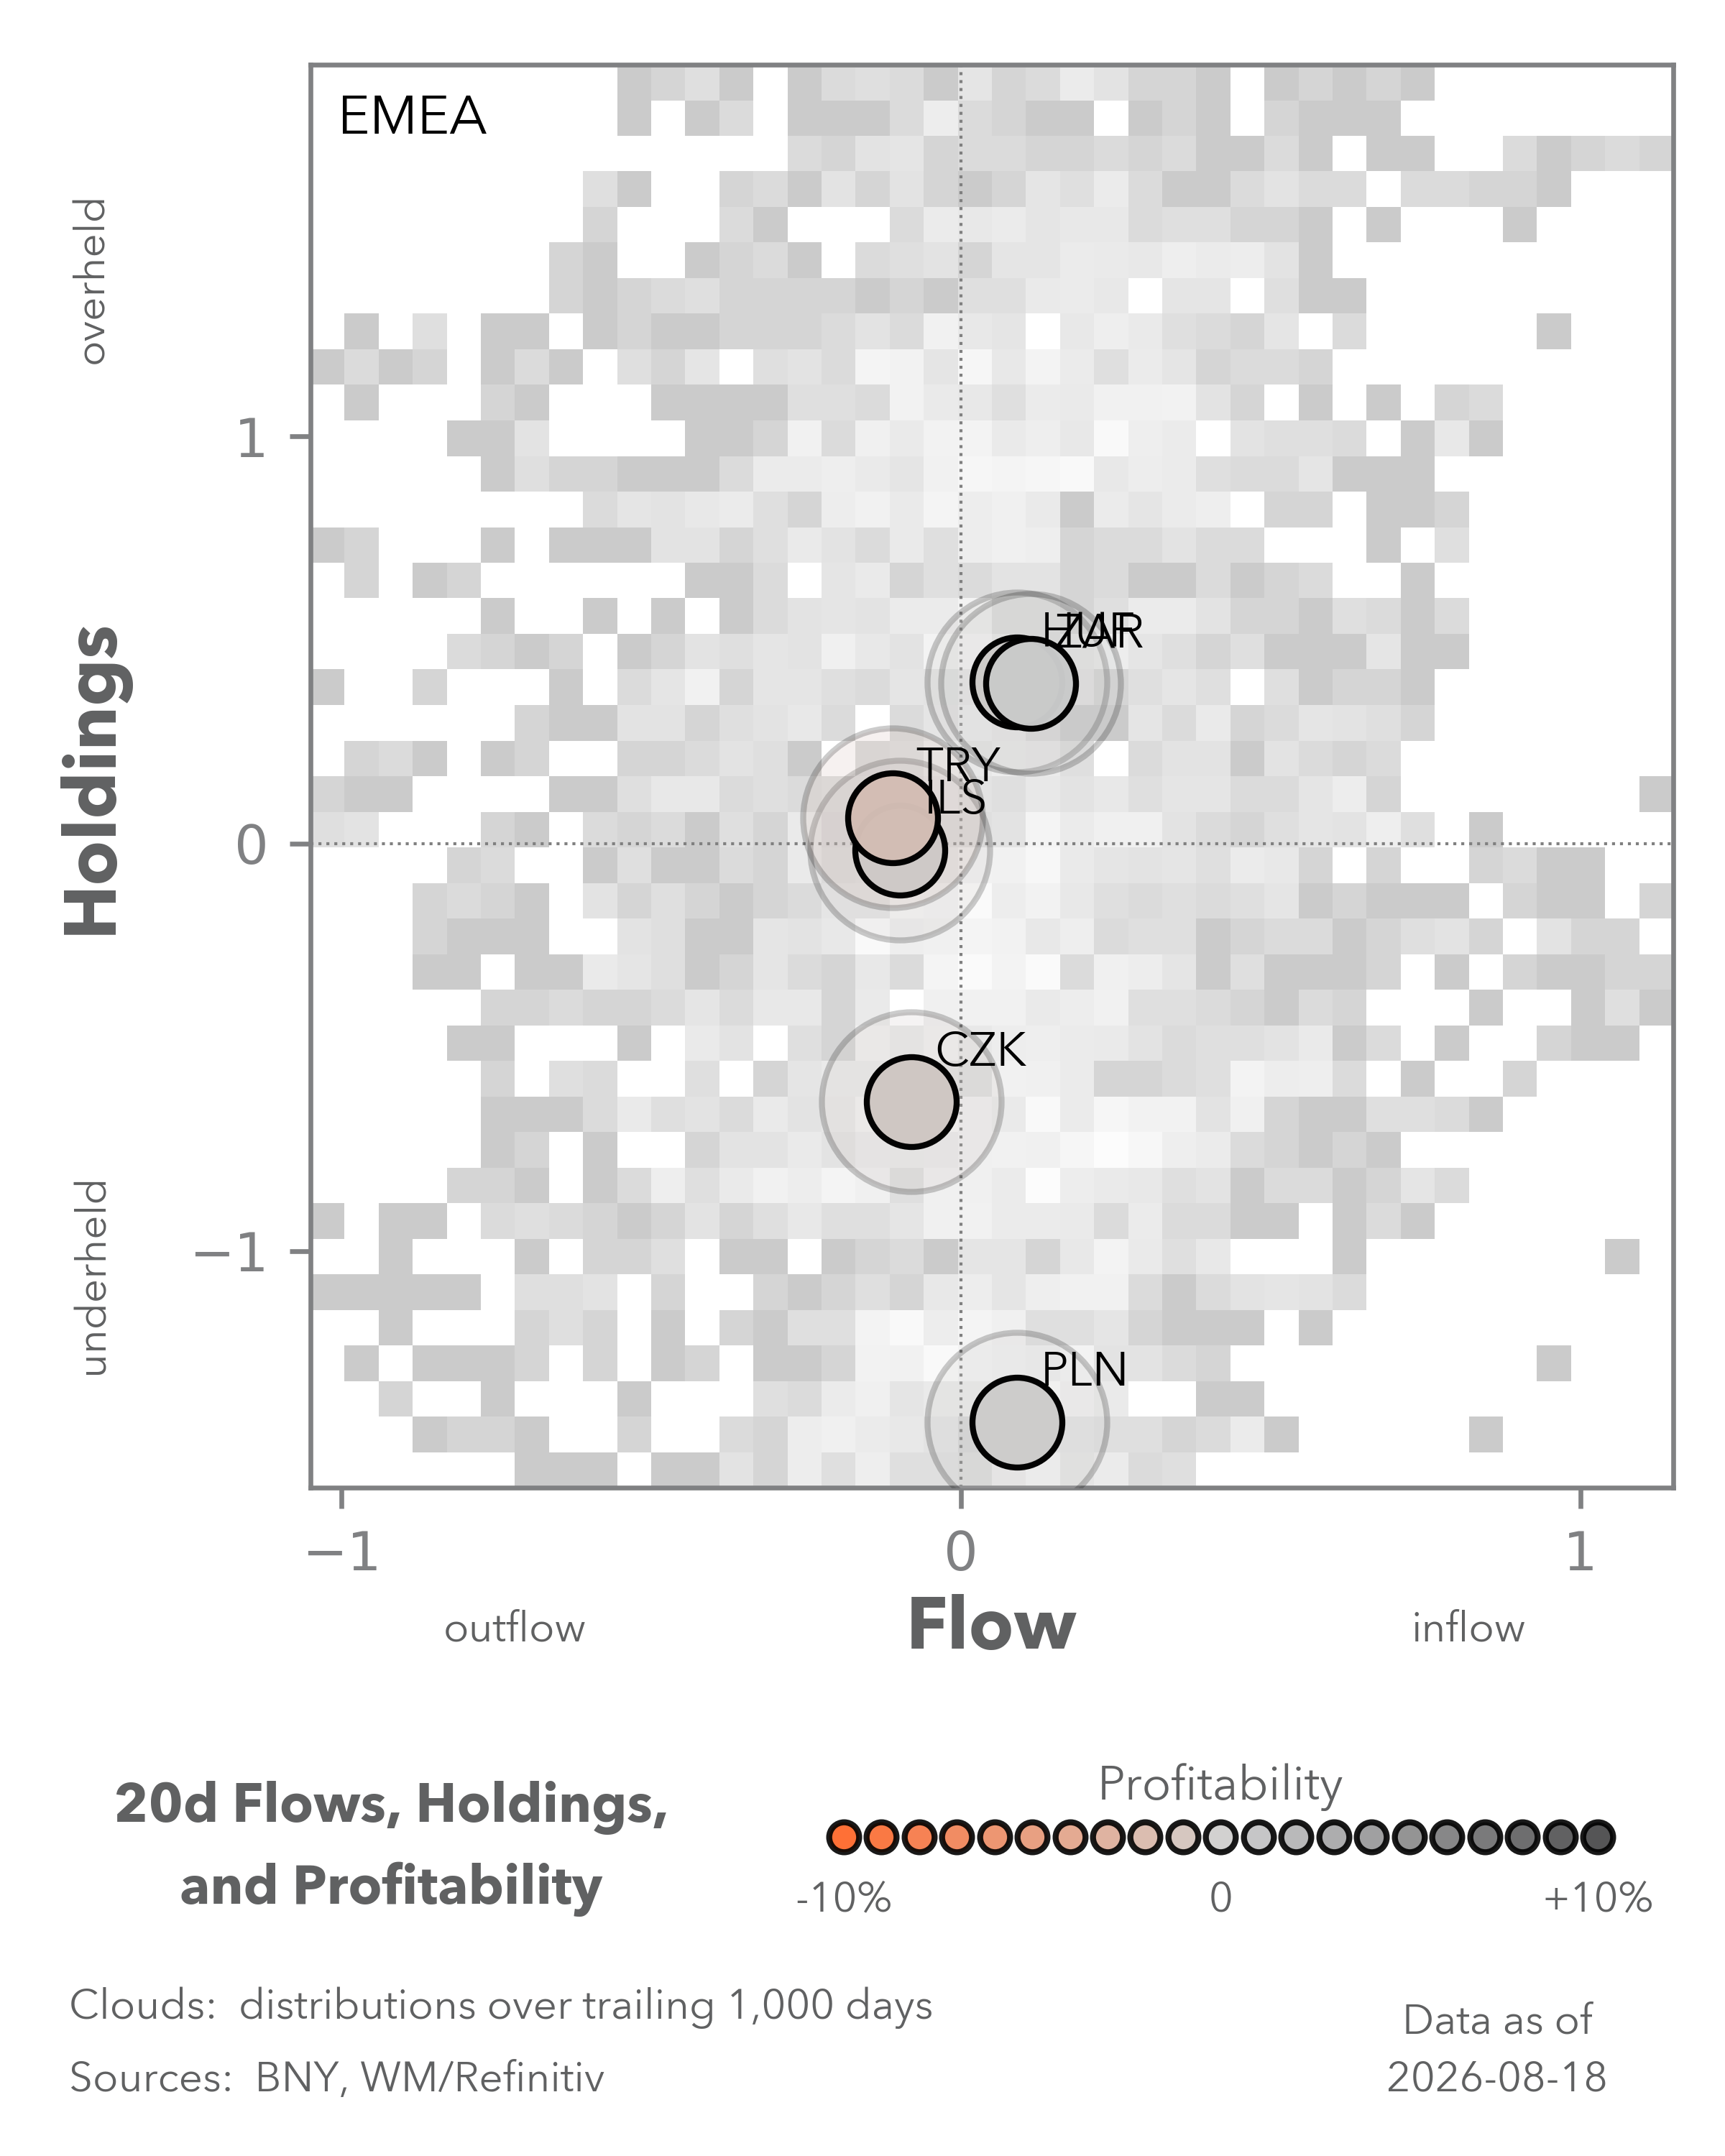
We’ve already highlighted how the July FOMC marked the high point in dollar exposures. The market remains relatively lightly hedged in its U.S. exposures, but if assets continue to decline, total U.S. positioning will fall accordingly. In the current environment, it’s understandable that investors will still want to add to their U.S. asset hedges, short of liquidating outright. As discussed above, the question is not which currencies outperform, but which underperform the least. Our data suggest that clients are already well-positioned for such a scenario. CHF and SGD are currently the best-held currencies in the “quality group,” and both have also been net bought over the past month. The EUR remains underheld on a cross-border basis, but flows have recovered well of late. Liquidity constraints mean that EURUSD remains the best way to hedge against dollar weakness, even though we don’t consider current valuations or even holding levels as particularly attractive.
Forward Look
The lack of interest in CNY and JPY holdings and flow underscores how markets don’t see strong balance of payments as the arbiter of quality status. CNY exposures bring non-market-related issues, while the JPY is currently at the forefront of policy credibility matters. Furthermore, both economies are highly exposed to external supply shocks, which have a knock-on impact on FX settlement levels, especially in commodities where the dollar remains the dominant unit of account. This is why China is seeking to introduce the renminbi in its own trade exposures over time. In contrast, Japan has locked itself into dollar invoicing for decades – a framework that is clearly no longer fit for purpose.
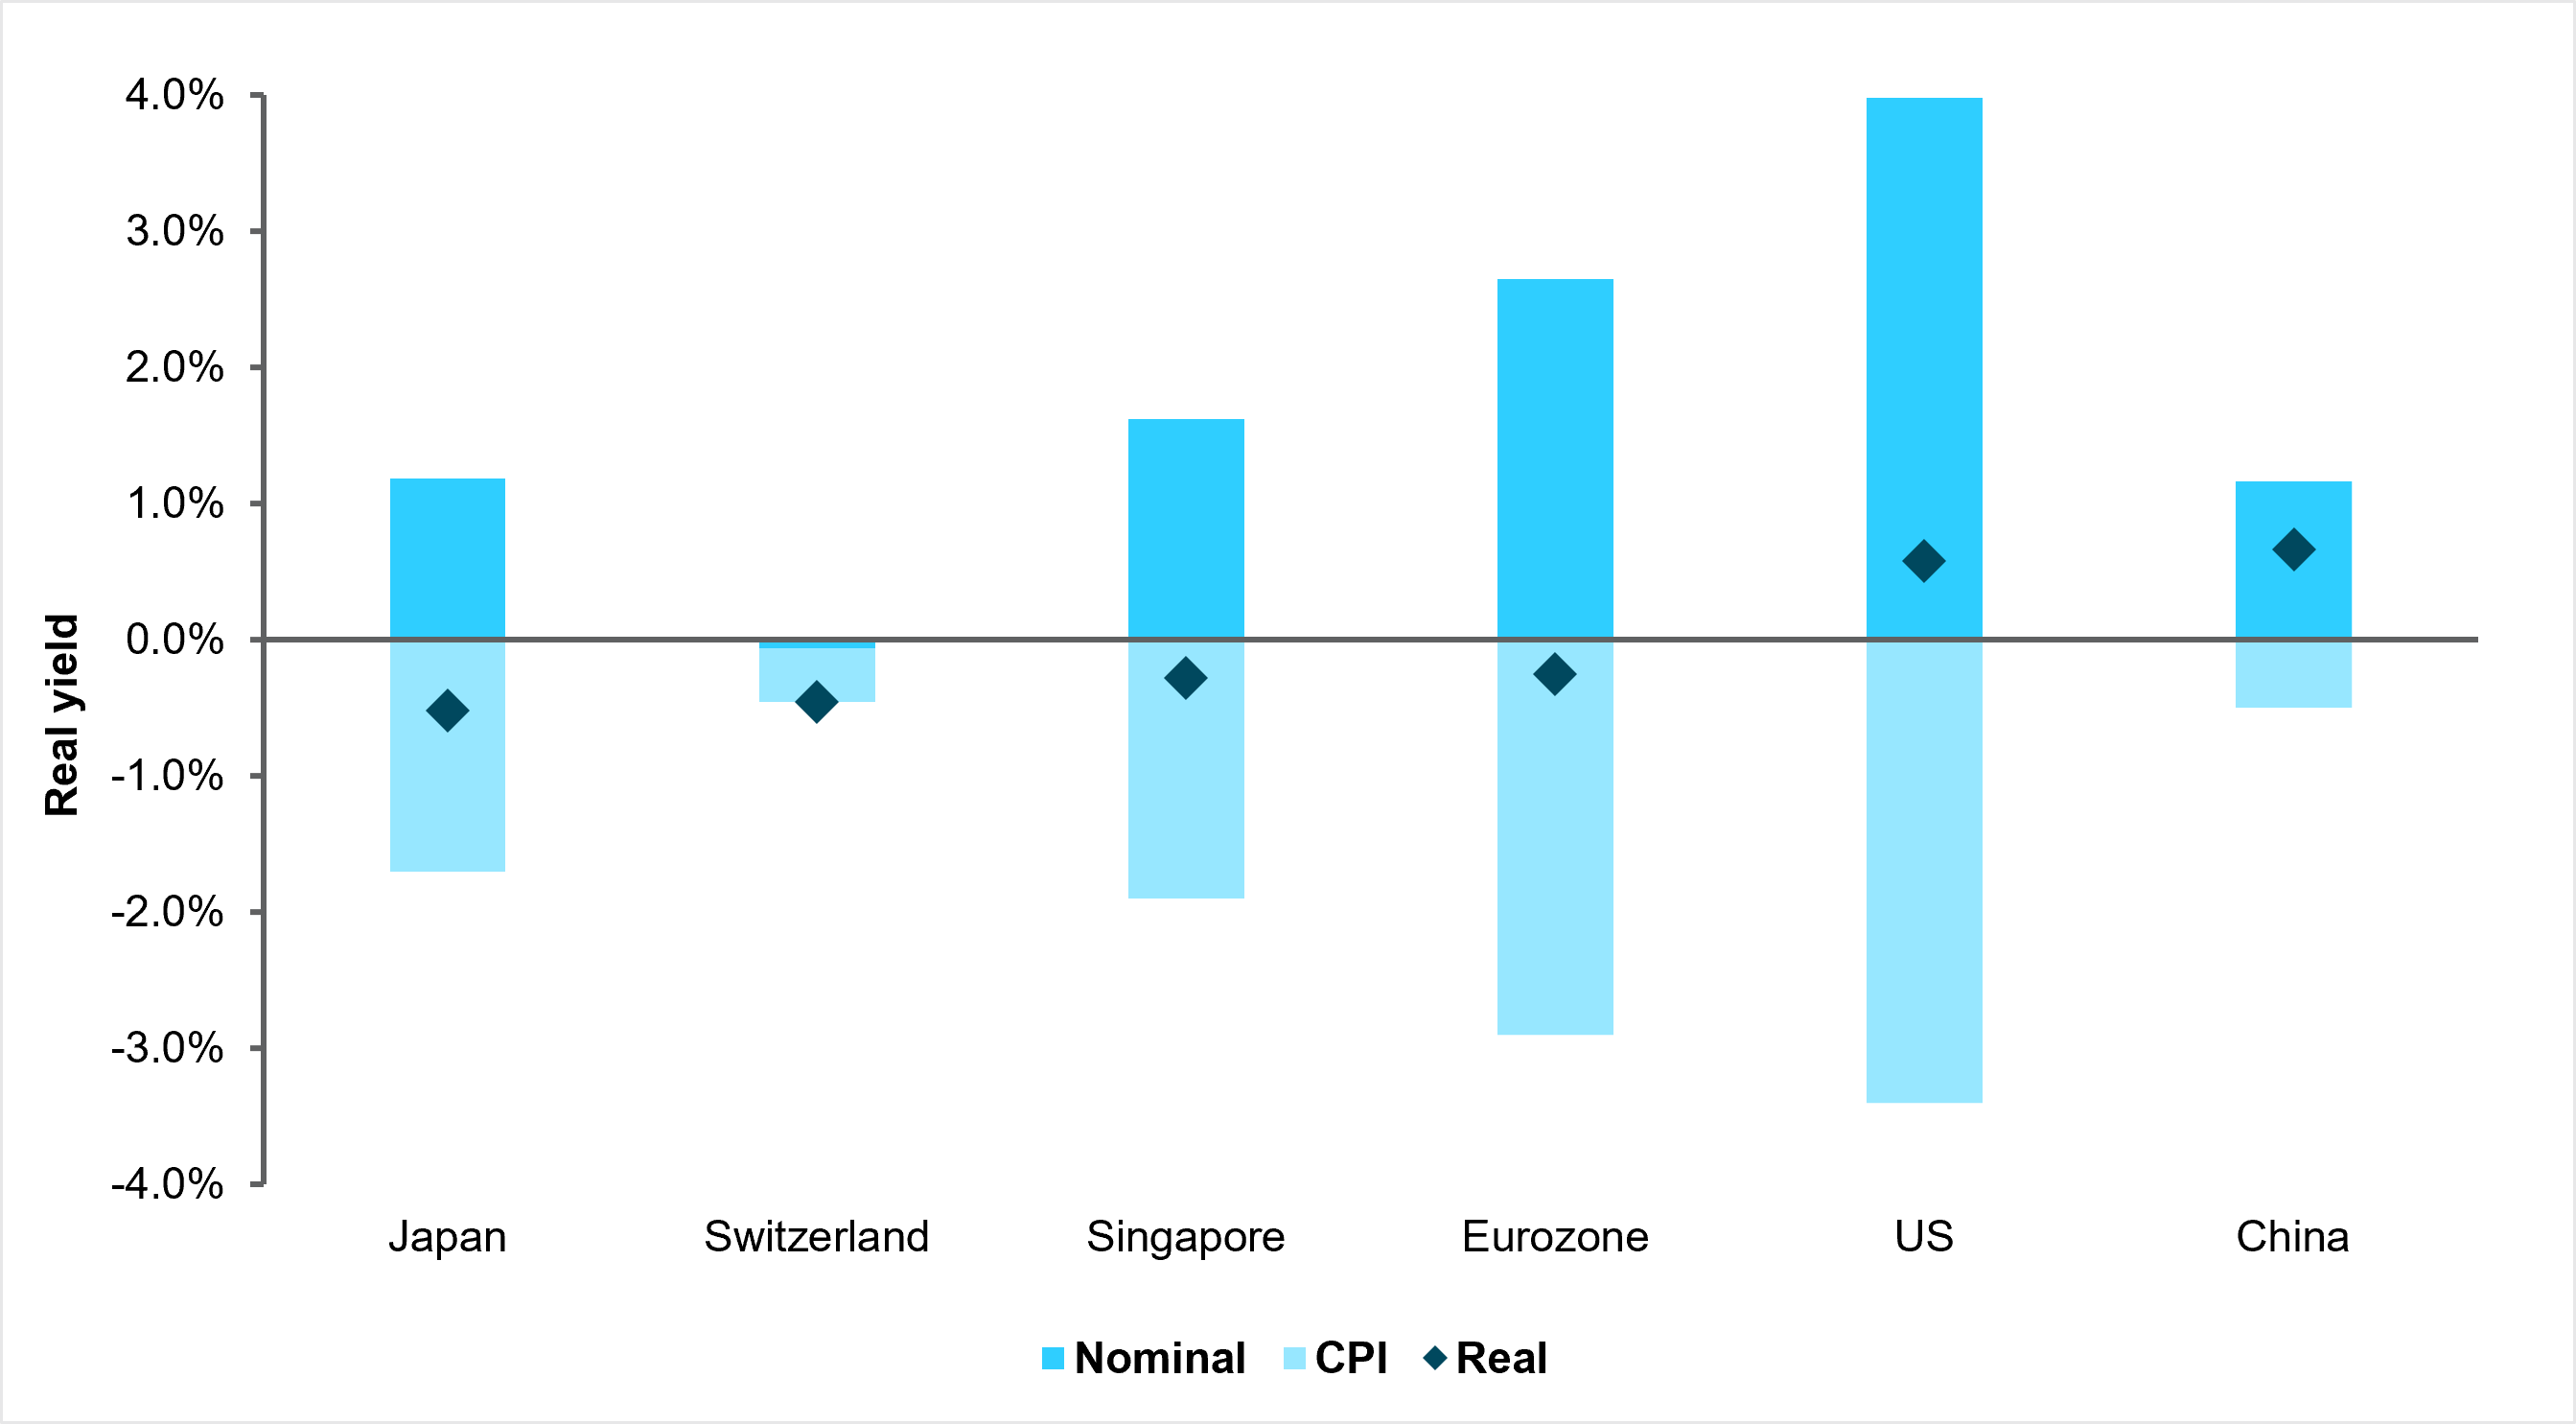
EXHIBIT #3: CURRENT SHORT-TERM REAL YIELD BASED ON 12M T-BILL AND HEADLINE INFLATION RATES
Source: BNY, Bloomberg
Our take
Reserve status aside, the dollar continues to enjoy a significant yield advantage. Using the latest CPI and 12-month T-bill levels for the five surplus economies and the U.S., the dollar has the second-highest short-term real rate at 58bp. China is ahead at 66bp, but psychology matters greatly as nominal yields are low; the high real rate is only being supported by ongoing deflation – hardly a positive “carry” case. Given Beijing’s clear push to exit the current price environment, the risk to Chinese real rates is clearly to the downside, so the dollar will continue to maintain its real-rate advantage. All other economies identified still have negative front-end real rates, and all associated central banks (except the Monetary Authority of Singapore, which runs currency-based monetary policy) are indicating a strong reluctance to hike rates in the current environment. Not only does history serve the dollar well during correlated selloffs, but there’s also a clear yield case, which perhaps wasn’t as strong during previous episodes.
Forward look
If real yields are the dollar’s biggest source of strength, then any loss will represent the biggest risk. This is perhaps what prompted the move in the dollar in July, as markets questioned whether the Fed was still committed to anchoring financial conditions through high real rates. Throughout the conflict this year, moves in U.S. breakevens were relatively contained: The 5y5y forward breakeven moved only 15bp from pre-conflict levels to the first half of May. The ceasefire in June generated full normalization. However, the same breakeven rate moved over 15bp higher in the second half of July alone and remains well above the highs during the peak of the conflict. Any further erosion will prompt a reassessment in which previous frameworks that supported the dollar during correlated selloffs could break down. The dollar’s reaction to yesterday’s buybacks announcement is a warning indicator of such risks.
Avoid large structural USD shorts as a hedge against correlated cross-asset stress. Maintain dollar exposure for protection, while using CHF, SGD and EUR selectively as secondary defensive positions. The key risk to this stance is a sustained decline in U.S. real yields and a further rise in inflation expectations.