Debasement deterioration
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
FX: G10 & EM, published every Thursday, provides a detailed analysis of global foreign exchange movements in major and emerging economies around the world together with macro insights.
Geoff Yu
Time to Read: 4 minutes
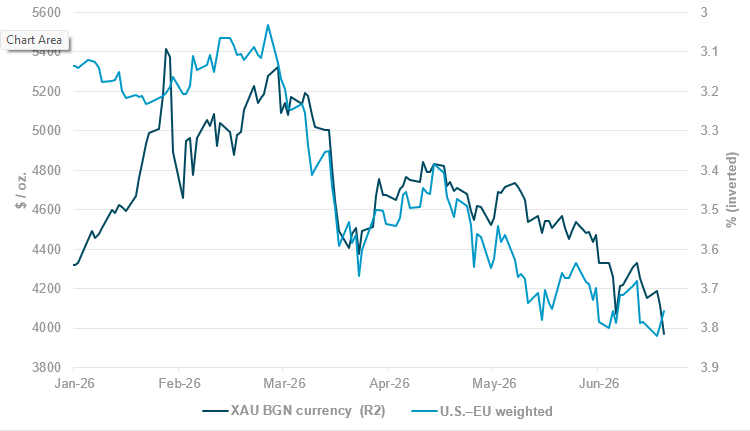
EXHIBIT #1: GOLD PRICES VS. GLOBAL 2Y YIELD INDEX
Source: BNY, Bloomberg (2y yields for U.S. and Germany, 60:40 weighted)
Our take
Gold prices fell through $4000/ounce yesterday, marking a poor run since mid-March. Precious metals fell sharply during the conflict itself even before policy expectations corrected sharply. When the market needs liquidity, gold’s intrinsic properties undermine performance. Turkey and other central banks reportedly utilized swaps to generate liquidity rather than sell into a falling market.
Such transactions were not unlike the Foreign and International Monetary Authorities (FIMA) Repo Facility launched by the Fed during the most extreme months of the pandemic, which “helped address pressures in funding markets.” FIMA helped realize liquidity through central bank Treasury holdings without outright sales, which would have had significant consequences for financial stability at the time. In times of crisis, cash becomes king, and gold should not be used for liquidity purposes at all.
Forward Look
The most recent run is due to repricing in global interest rates. Although tightening expectations have come off the highs during the height of the conflict – the market has moved from four hikes priced for the Bank of England to less than one. Gold prices have continued to decline. Two factors are driving the selloff. First, Fed repricing was late: energy self-sufficiency was ultimately unable to counter global supply risks and Fed Chair Kevin Warsh has responded in kind. Coupled with an assertive European Central Bank, global front-end yields continue to rise strongly.
Second, gold and precious metals were seen as defense against “debasement” in Q1, not just against dovish monetary policy but also profligate government spending. The conflict has, perhaps more surprisingly, driven up global real rates as inflation break-evens have not moved as much as nominal yields. By design or accident, markets are exerting strong fiscal discipline against government spending, also negating one of the key drivers of precious metals demand. A loss of fiscal and monetary credibility is required for renewed performance, but it’s proving difficult to identify immediate catalysts.
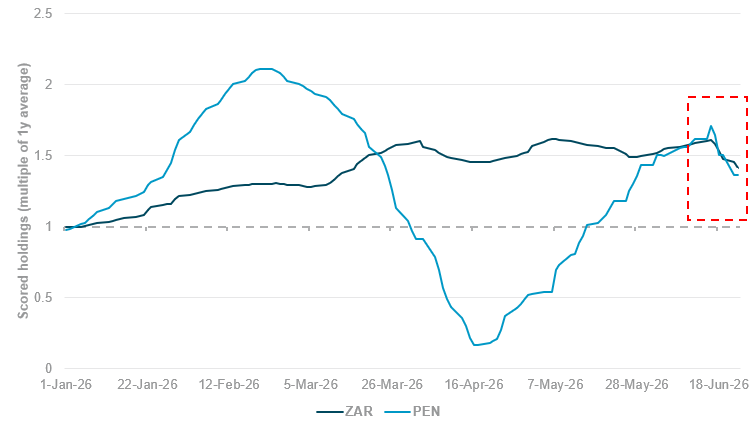
EXHIBIT #2: SCORED HOLDINGS, PEN AND ZAR
Source: BNY
Our take
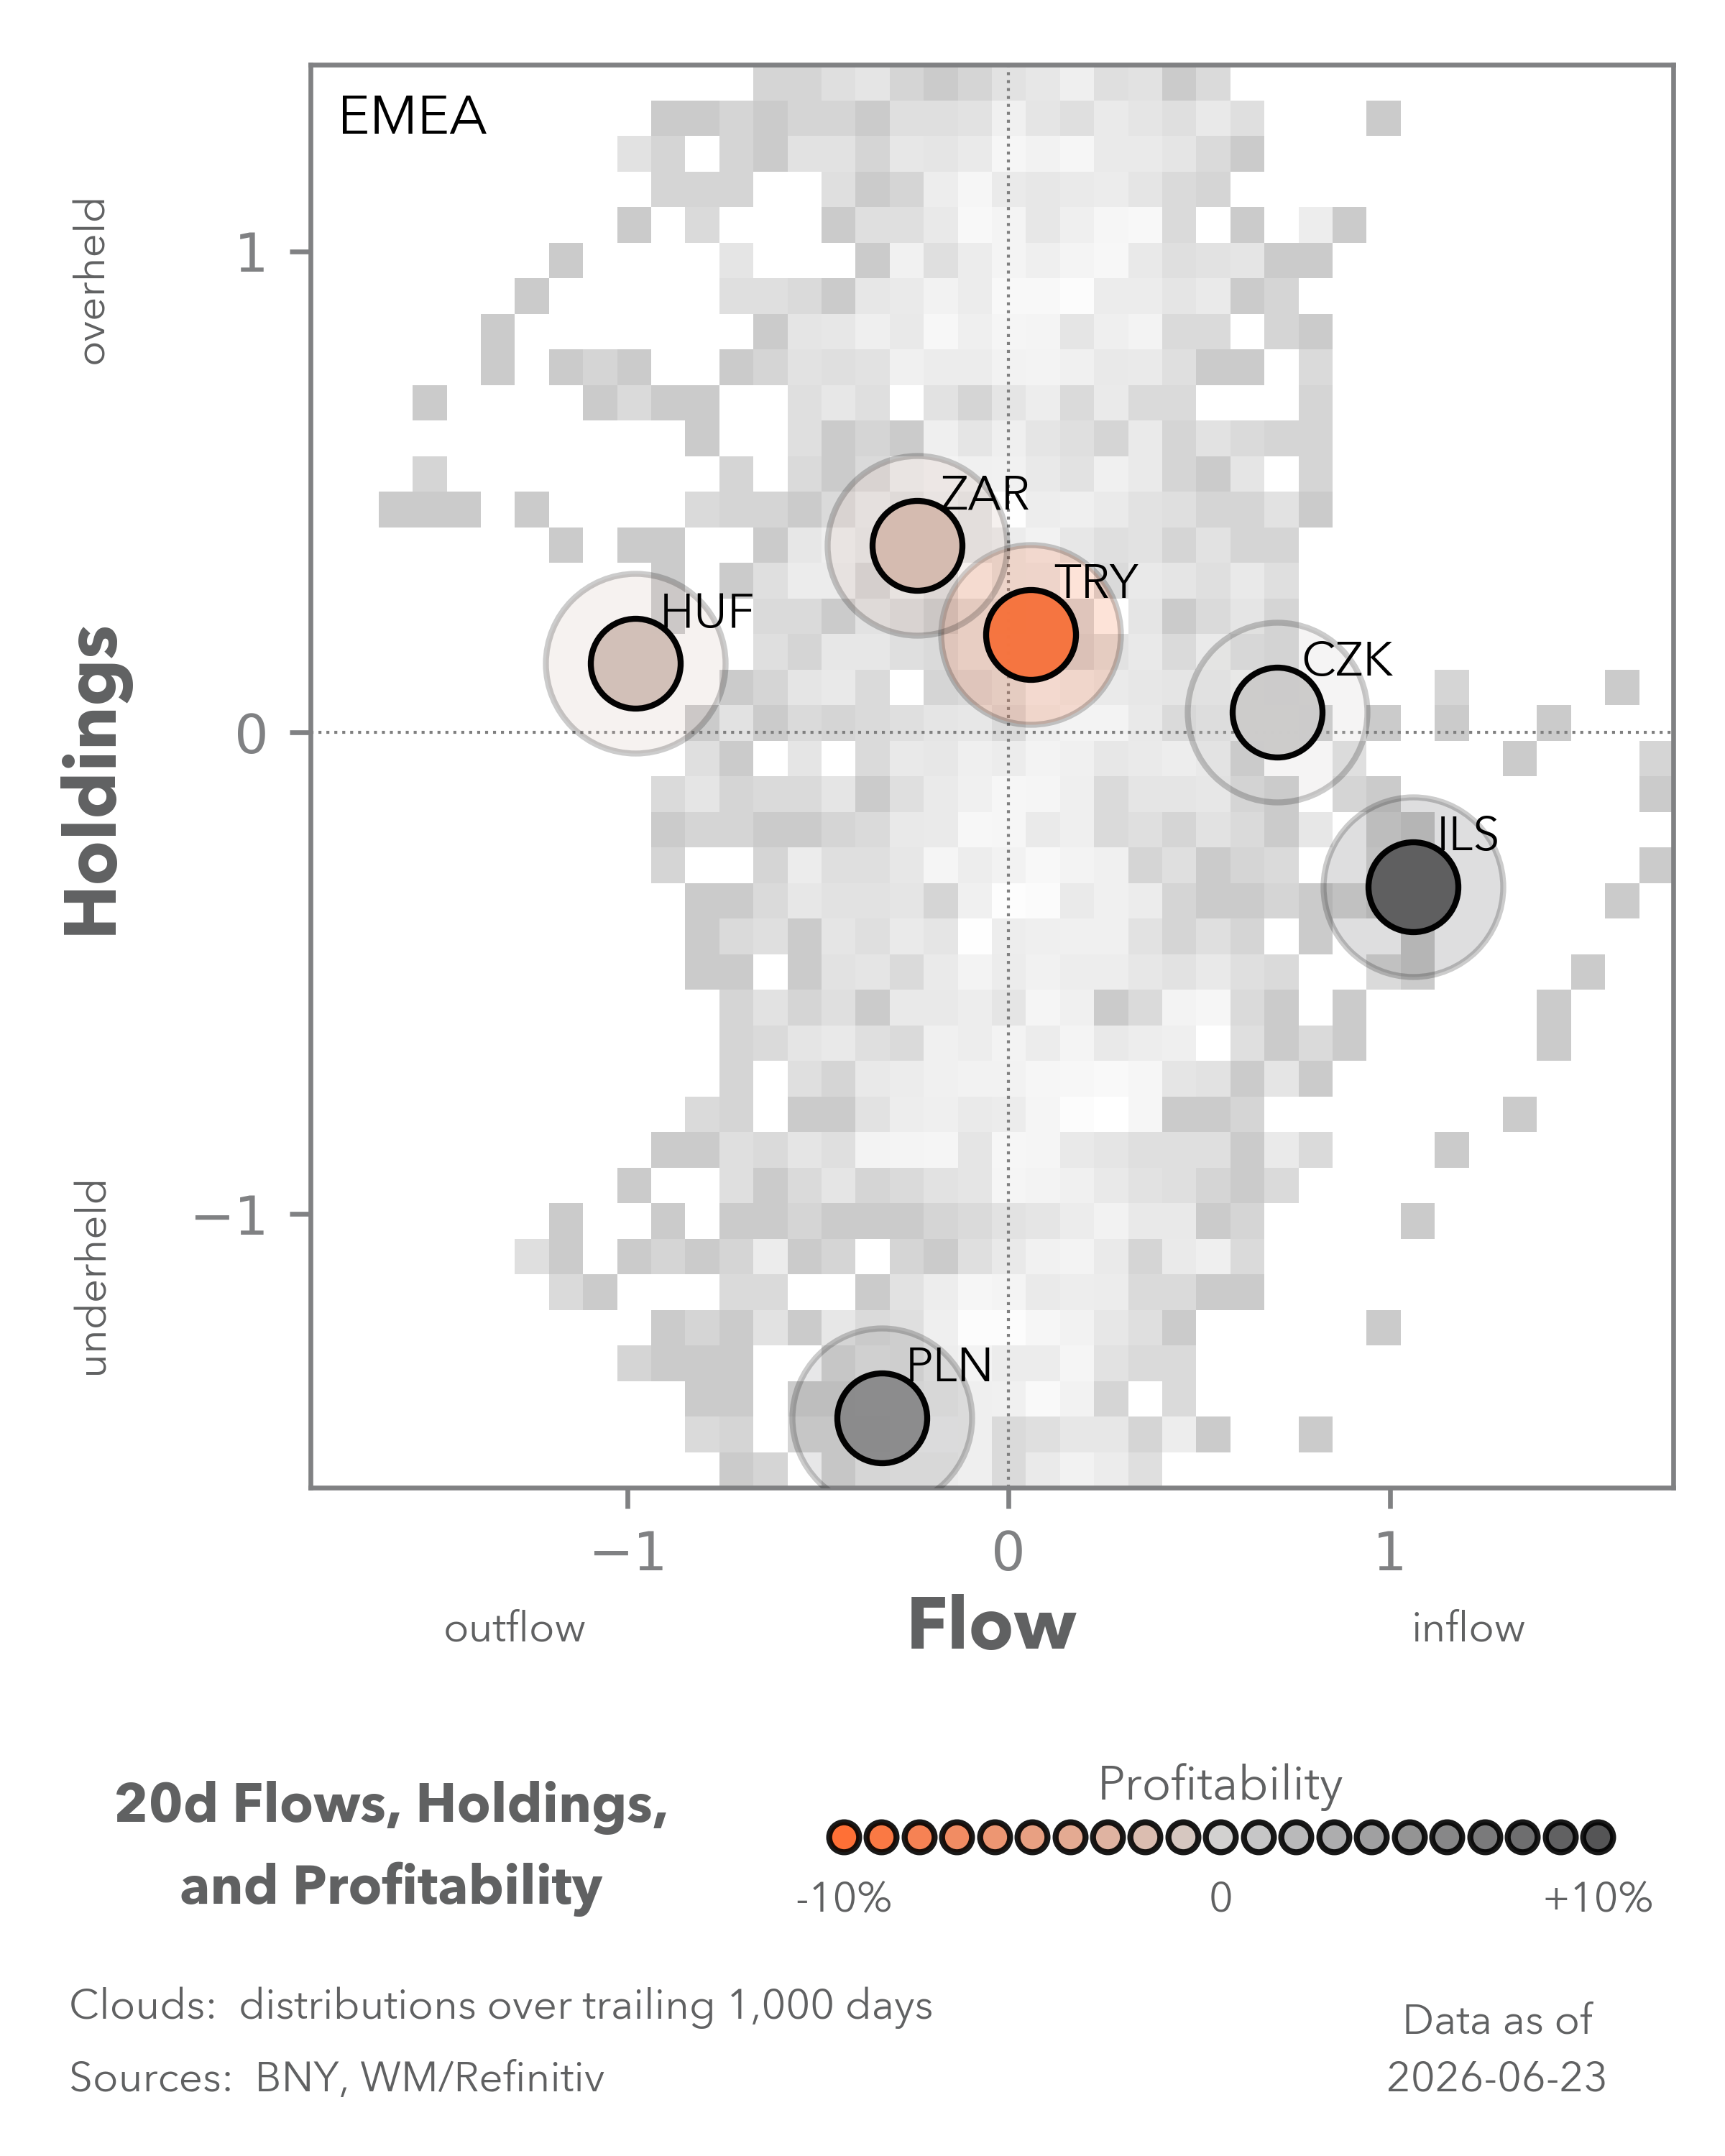
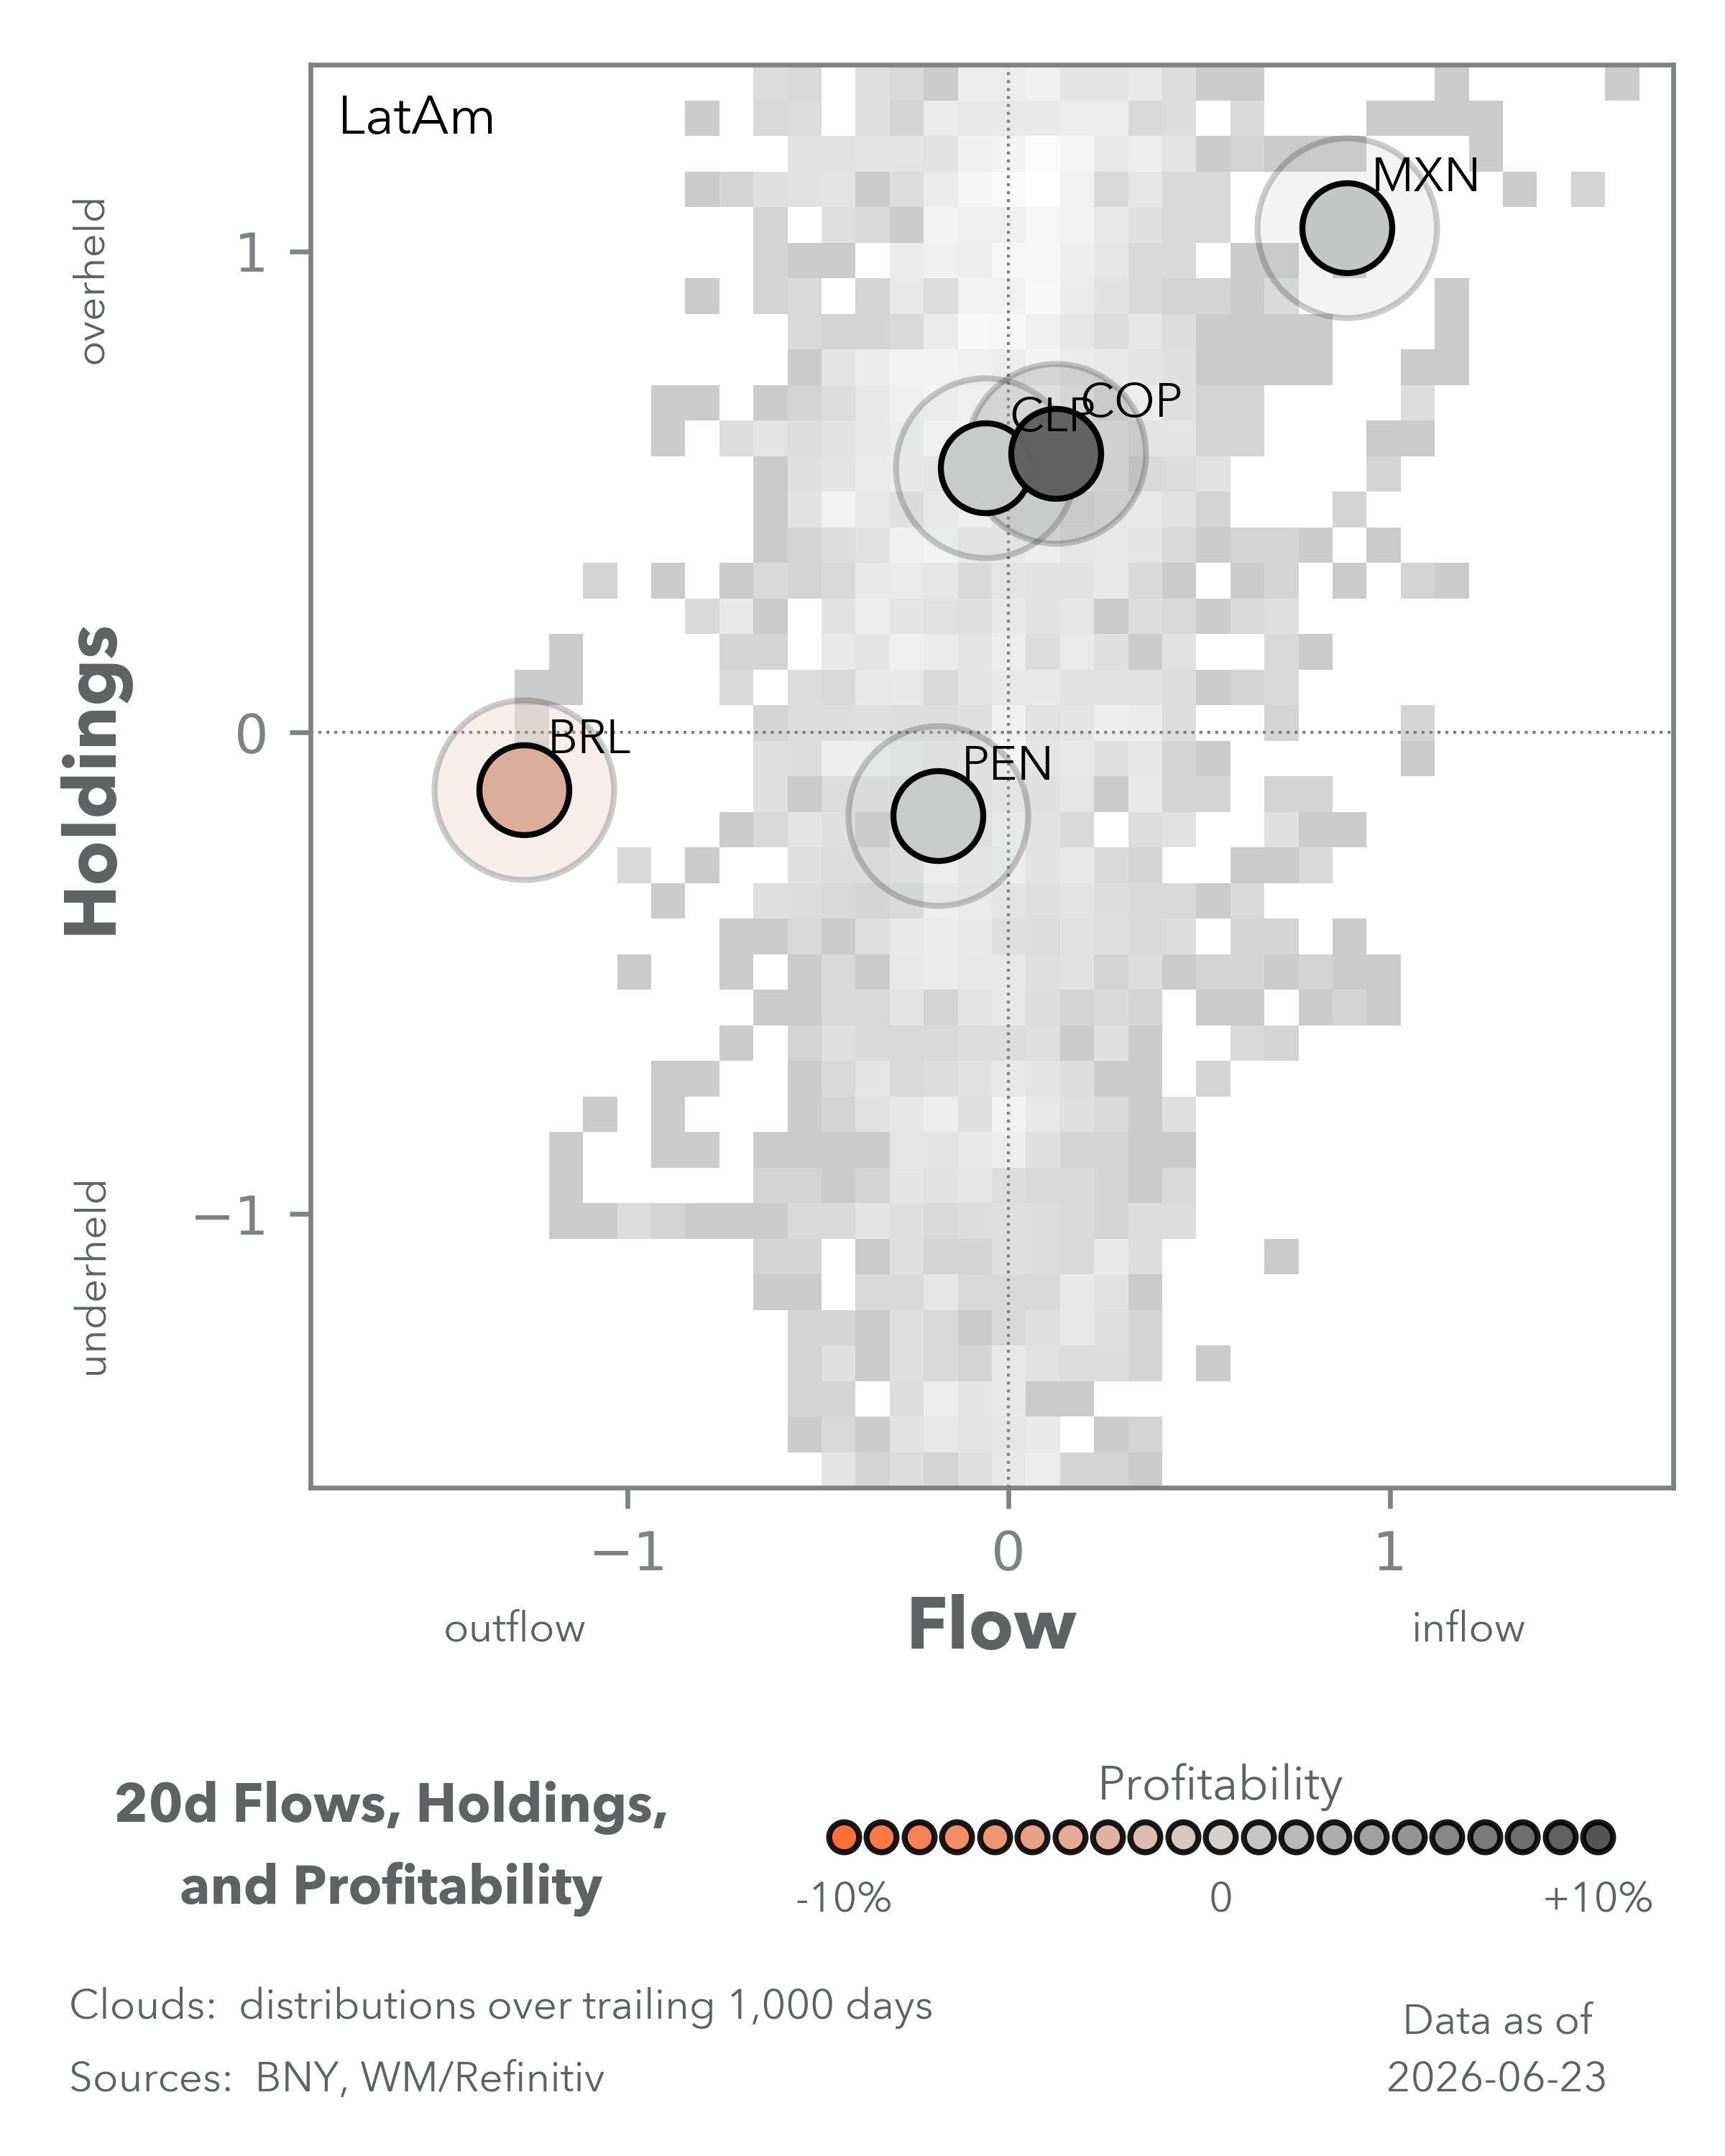
The ongoing weakness in precious metals performance is therefore significantly affecting currencies with the greatest relative terms-of-trade exposure. Industrial metals or other “hard assets” are facing similar pressure from high nominal and real yields. The marginal cost to export receipts will undermine performance in what should be an improving environment for the carry trade. As for direct exposure, we believe ZAR and PEN have the most to lose. Platinum and platinum group metals (PGMs) dominate South African exports, while Peru is the world’s third-largest silver producer, its exports disproportionately large relative to China and Mexico, the top two producers. Holdings of both PEN and Peruvian equities moved one-for-one with silver prices through January and February, but both struggled through the conflict. More recently, we can see that there’s been convergence in holdings losses for ZAR and PEN, in line with the deterioration in terms of trade.
Forward Look
Falling precious metals prices will continue to impact ZAR and PEN performance, but we don’t see a shift toward outright underheld or aggressive underperformance. There are institutional factors that could prove beneficial, such as South Africa’s inflation mandate and central bank resilience. Peru is also on the cusp of policy changes that are seen as more business-friendly and U.S.-aligned, potentially helping asset performance emulate the recent gains in Colombia. We have always advocated that single-commodity exposed economies use the fiscal space created by terms-of-trade improvements to engage in structural reform. Arguably, South Africa has achieved this since the formation of the Government of National Unity, culminating in a lower inflation target. Stronger fiscal rules were due but were derailed by the Iran conflict. The silver surge was too brief to generate material benefits for Peru, but there will be a second chance as the new government is sworn in.
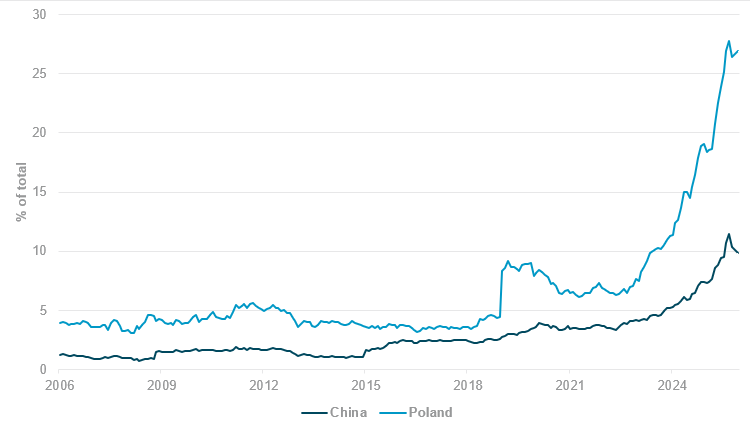
EXHIBIT #3: GOLD AS A SHARE OF TOTAL RESERVES
Source: BNY, Bloomberg LP
Our take
We don’t see the recent selloff derailing structural plans to increase gold’s share of reserve assets. Fundamentally, we don’t see any change in the status of the dollar or U.S. Treasurys, but growing debt burdens in the developed world are unlikely to change, and reserve managers will continue to push for asset diversification. Poland has long been seen as the most aggressive: Governor Adam Glapinski has called gold a “long-term anchor of security.” Current holdings amount to nearly 30% of total, which will increase portfolio volatility in the near term.
Meanwhile, China as the world’s biggest reserve manager clearly has the firepower to absorb much more of the market and has been doing so in relative terms. In the past, when gold purchases resumed, there were soft limits on gold as a share of total reserves, which were subject to upward revision. As these caps were hit, either due to gold price appreciation or reserve losses, there would be a pause in purchases. However, the recent run of purchases is now at 19 months – the longest streak on record. There is clearly no sign of a cap in place even after holdings surpassed 10% of total in January this year. Matching Poland’s 30% share is excessive as it would mean gold reserves surpassing $1tn. Nonetheless, current accumulation appears far less restrictive.
Forward look
At current prices, gold markets may now look at the prospect of re-accumulation by central banks. Assuming the supply shock is over, real rates could fall sharply as central banks pivot away from inflation vigilance to growth support, especially in the developed world, where risks remain strongly to the downside. Political pressures could lead to recovery in fiscal impulse, and markets will start revisiting the “debasement” theme. Liquidity stress has also eased with balance of payments normalization, giving central banks the space to look at less liquid reserve assets. However, unlike the Q1 rush, we don’t see strong private sector participation, as its funding remains focused on technology and semiconductor themes.