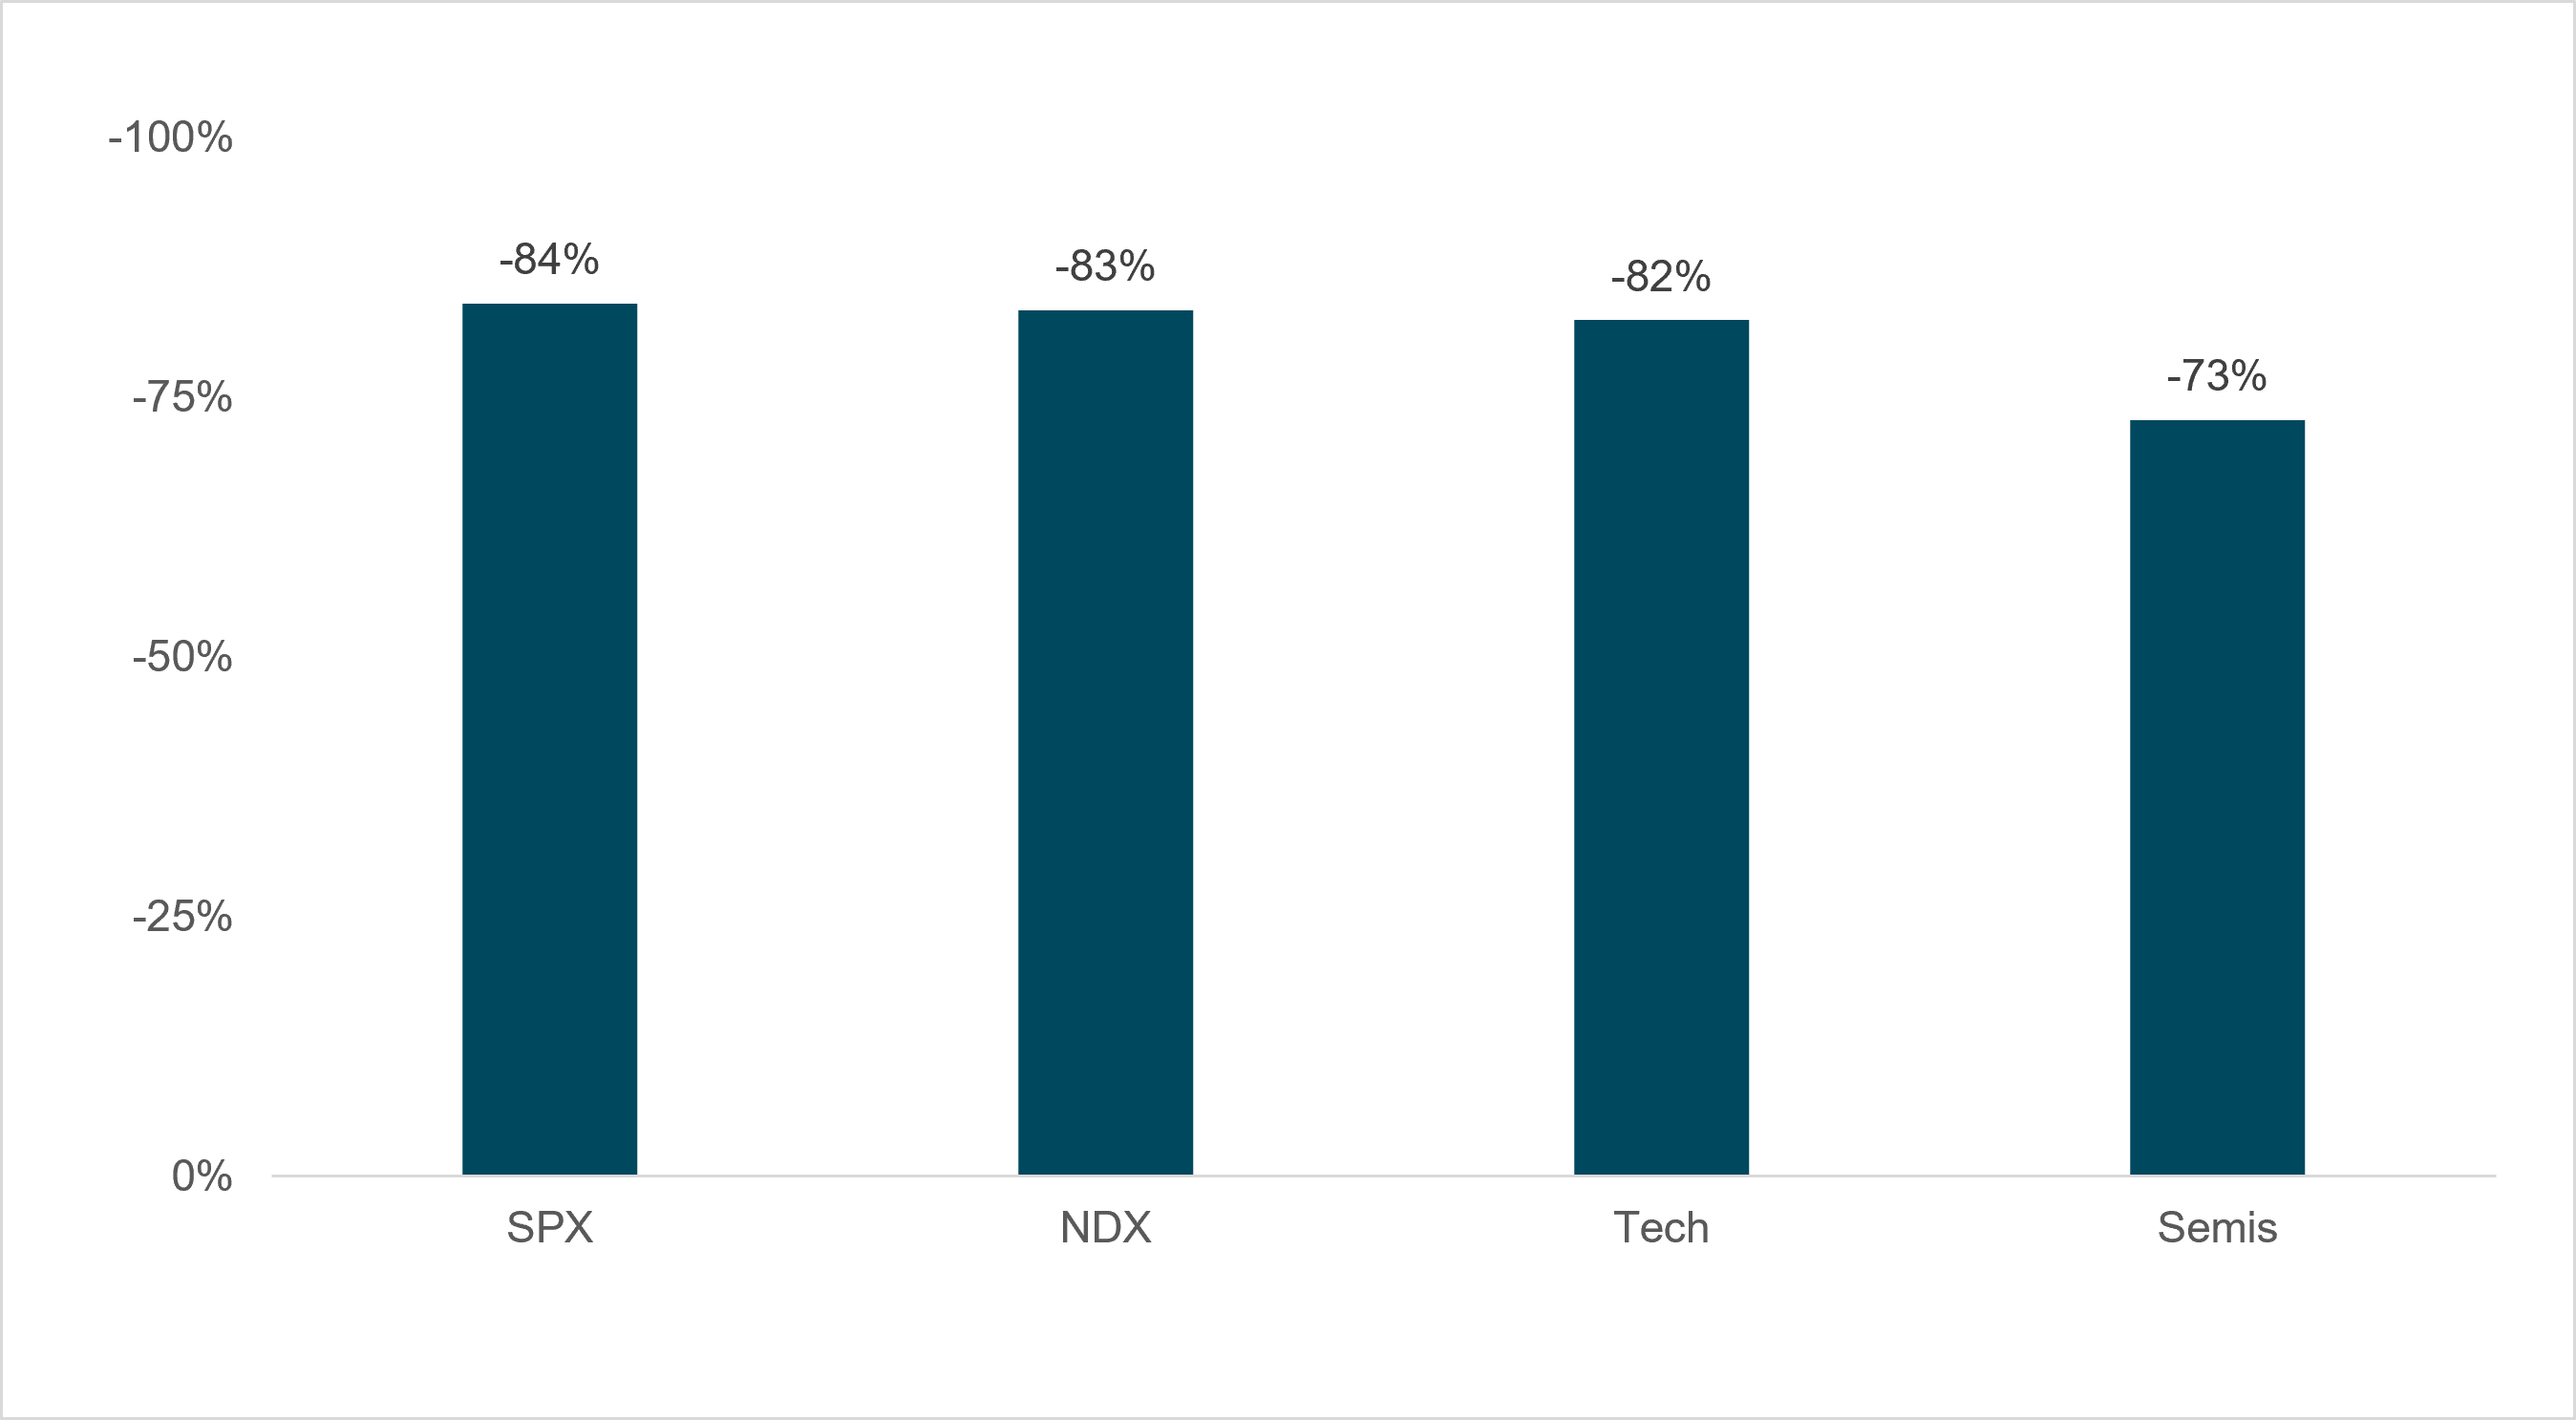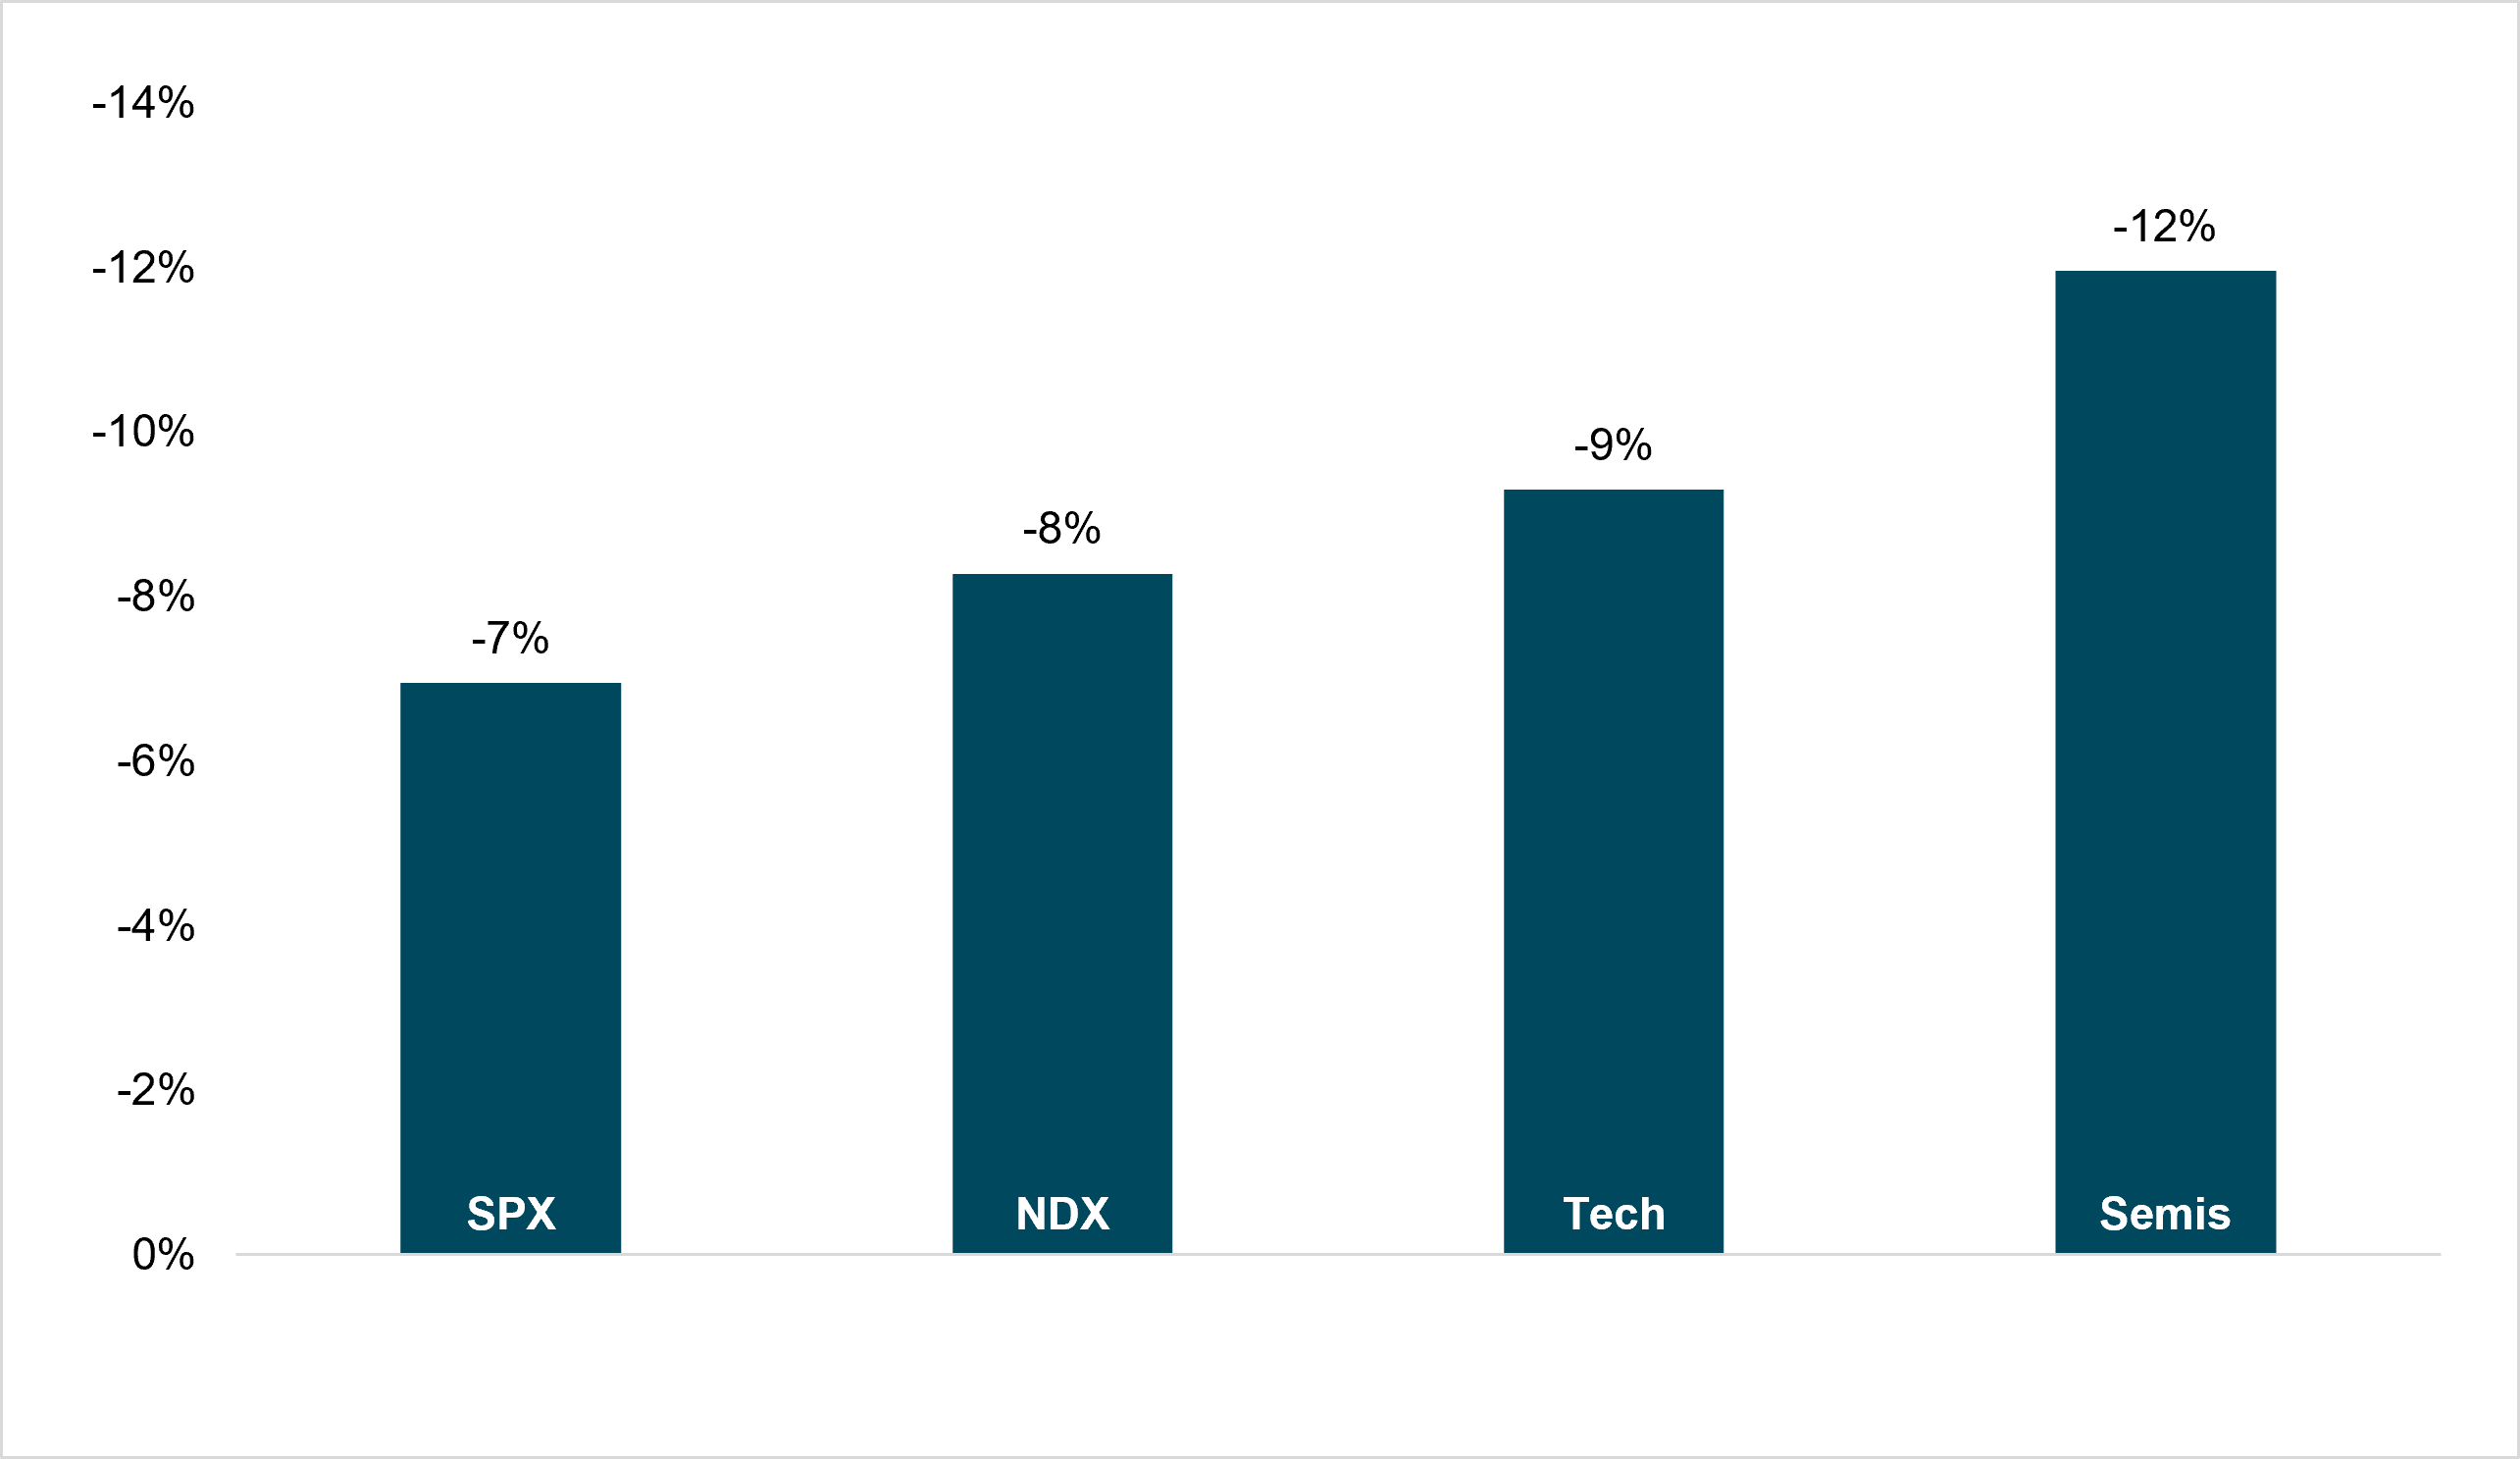Rates volatility and portfolio risk
iFlow > Equities
An in-depth look each Friday at the factors shaping equities markets in developed and emerging economies around the world.
iFlow > Equities
An in-depth look each Friday at the factors shaping equities markets in developed and emerging economies around the world.
David Tam
Time to Read: 2 minutes
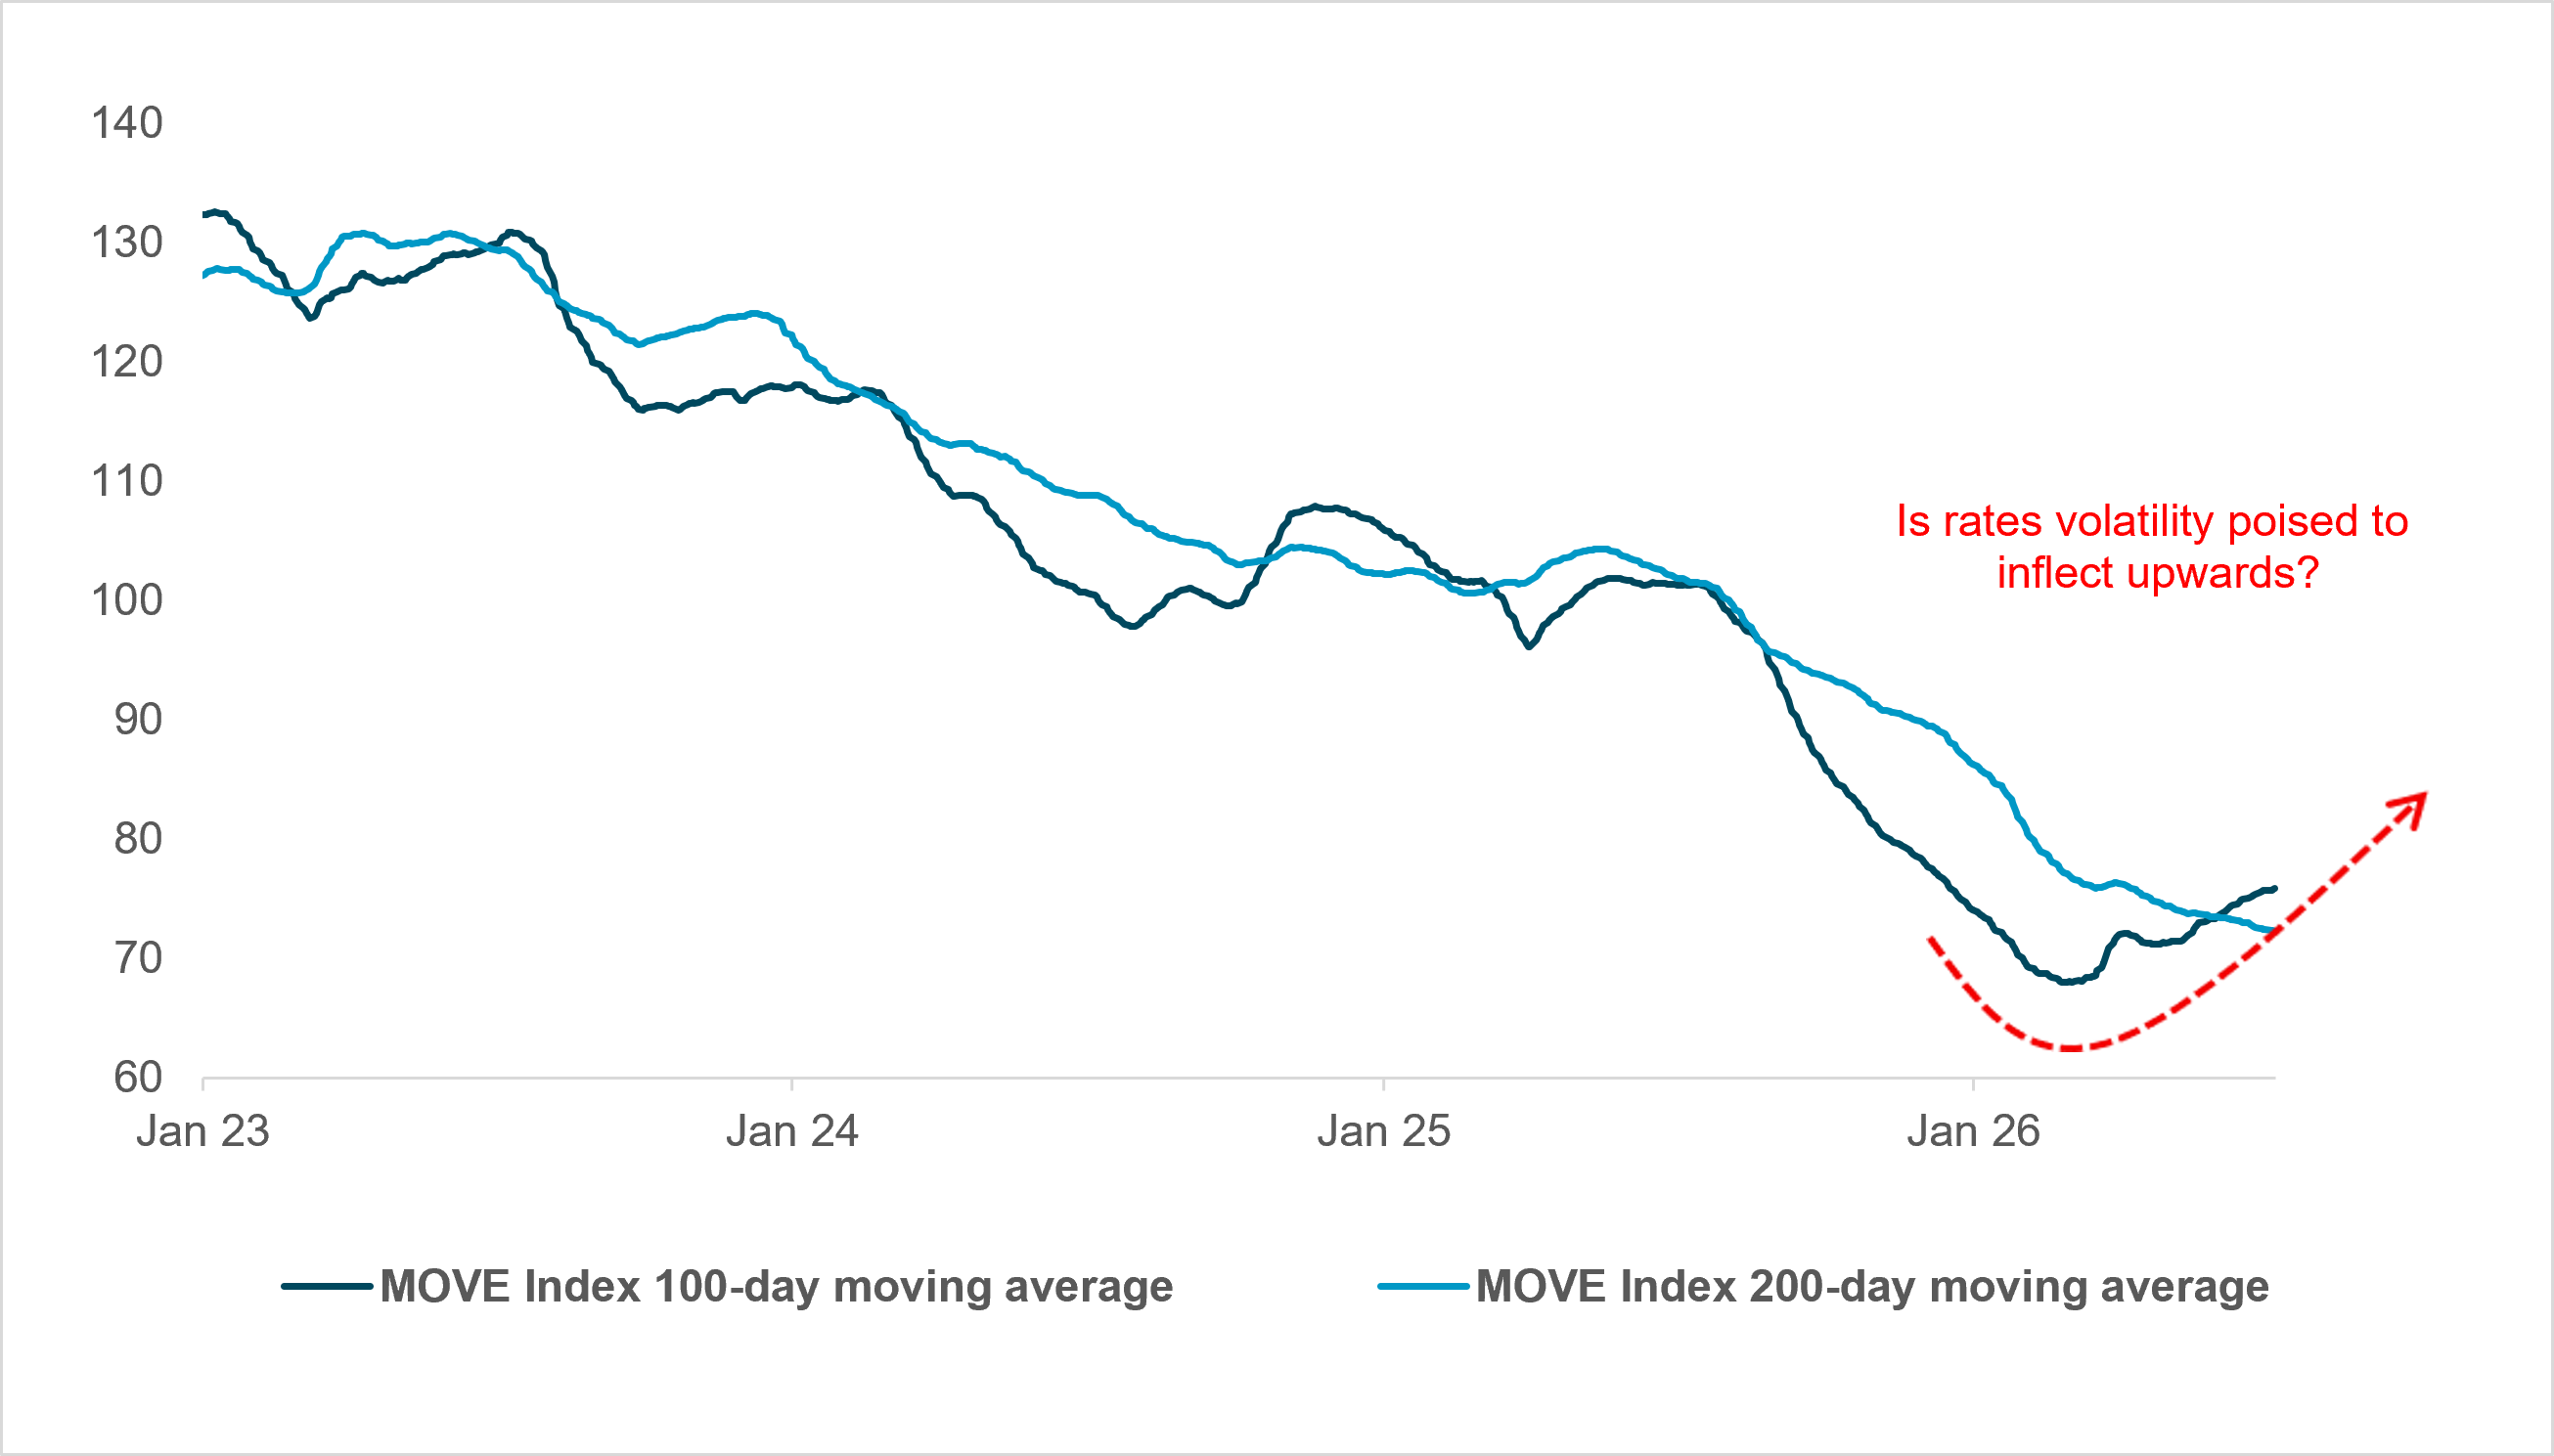
EXHIBIT #1: MOVE INDEX MOVING AVERAGES HAVE EXPERIENCED A MULTIYEAR DECLINE
Source: BNY Markets, Bloomberg
Rates volatility is poised to increase after a multiyear decline, which could be driven by the following:
Exhibit 1 suggests that the decline in rates volatility stretching back to 2023 might have reached its trough.
EXHIBIT #2: MOVE INDEX VS. EQUITY INDEX – DAILY CORRELATIONS, JANUARY 1, 2023, TO JUNE 30, 2026
Source: Bloomberg
Since 2023, and more recently since 2025, rates volatility has also been much more consequential for equity markets than in the past. As Exhibit 2 shows, the S&P 500 has been strongly negatively correlated with rates volatility at about -84 %, as measured by the MOVE Index. This pronounced correlation persists across tech-centered equity market segments. The Nasdaq (-83%), tech (-82%), and semiconductors (-73%) are reacting far more to bond market volatility than many investors are positioned for.
EXHIBIT #3: CHANGE TO EQUITIES ASSOCIATED WITH A 1BP CHANGE IN THE MOVE INDEX
Source: BNY Markets, Bloomberg
Growthier equity segments are longer-duration assets and – when rates volatility rises – are responding much like long-duration bonds. Exhibit 3 shows the beta of these equity indices to the MOVE Index, indicating that the biggest pressure is landing on the longest-duration parts of the equity market.
That matters most for semiconductors. While they have nearly the same correlation to the MOVE Index as the S&P 500 does, semiconductors are twice as sensitive to rates volatility as the market, indicating embedded growth expectations, more duration risk, and more downside if bond volatility keeps rising.
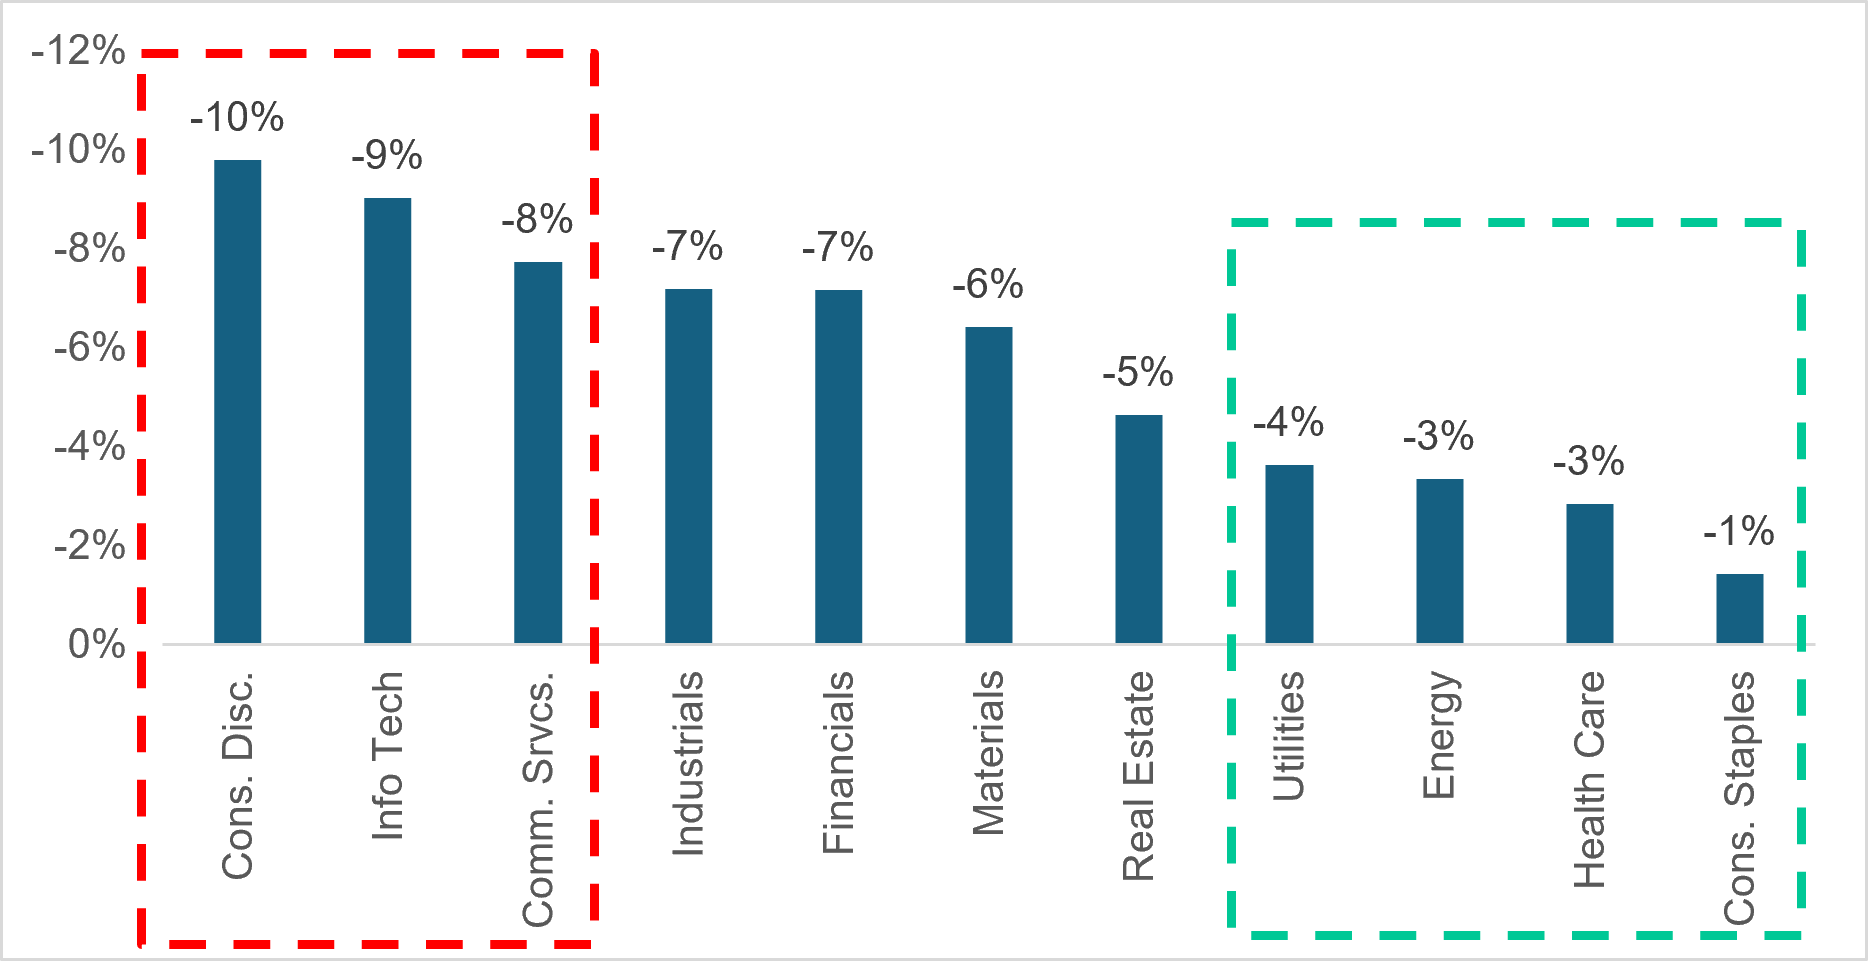
This same pattern runs across sectors. As Exhibit 4 shows, longer-duration sectors like Consumer Discretionary, Information Technology, and Communication Services are materially more sensitive to rates vol than defensive sectors and energy are. If rates volatility rises from here, leadership could change quickly, and portfolios concentrated in growth could see sharper swings than investors have grown used to.
EXHIBIT #4: PERCENT CHANGE IN S&P 500 SECTORS ASSOCIATED WITH A ONE-POINT CHANGE IN THE MOVE INDEX
Source: BNY Markets, Bloomberg
Investors should rotate toward more defensive exposure
Investors should act now. That means expanding risk budgets, reducing equity exposure, or actively reducing the equity duration of their portfolios by changing their sector allocation or size/style emphasis.
In particular, investors should favor defensive sectors on the right of Exhibit 4, with large cash reserves on their balance sheets and consistent all-market revenue.
How to track our theses: