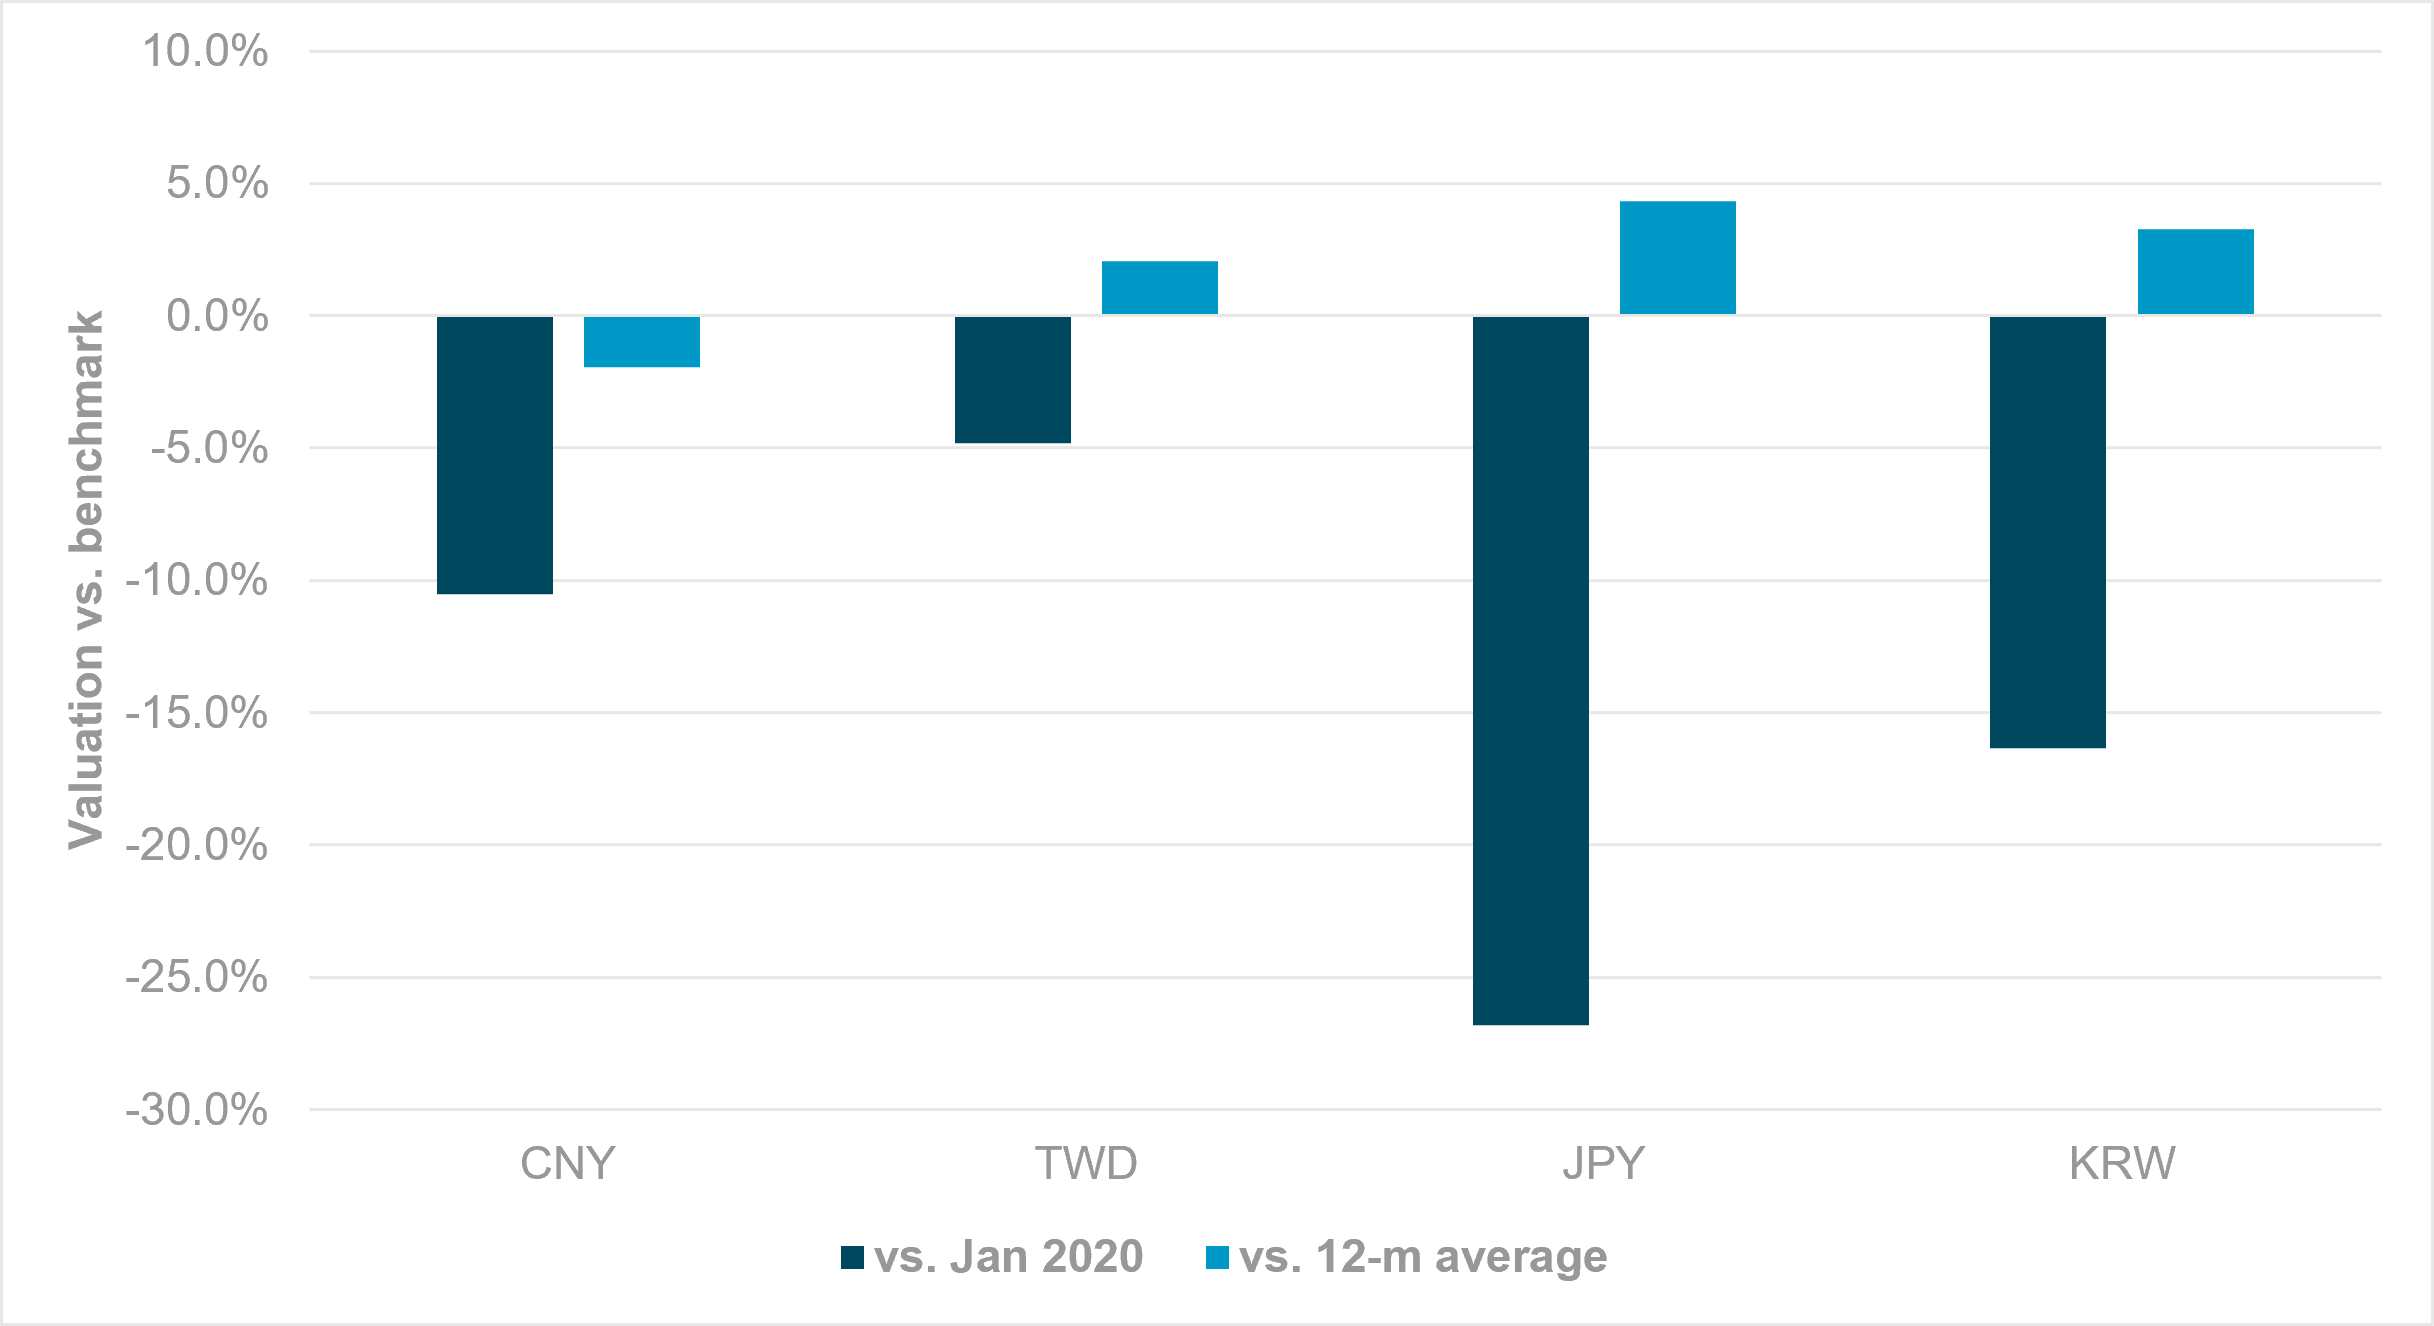APAC FX Flows: Record volumes, divergent drivers
Special Report

Geoff Yu
Time to Read: 9 minutes
APAC asset-market volumes hit records in 2026. Don’t mistake that for broad risk-on conviction. iFlow shows rebalancing, hedging and profit-taking are driving much of the activity. In South Korea and Taiwan, some of the world’s best equity returns have come with persistent institutional selling. In EM Asia rates, bond turnover has jumped, but FX has often failed to confirm. In several currencies, cheap valuations and louder policy pressure still have not produced sustained appreciation. The takeaway is clear: the busiest markets are often distributing risk, not adding it.
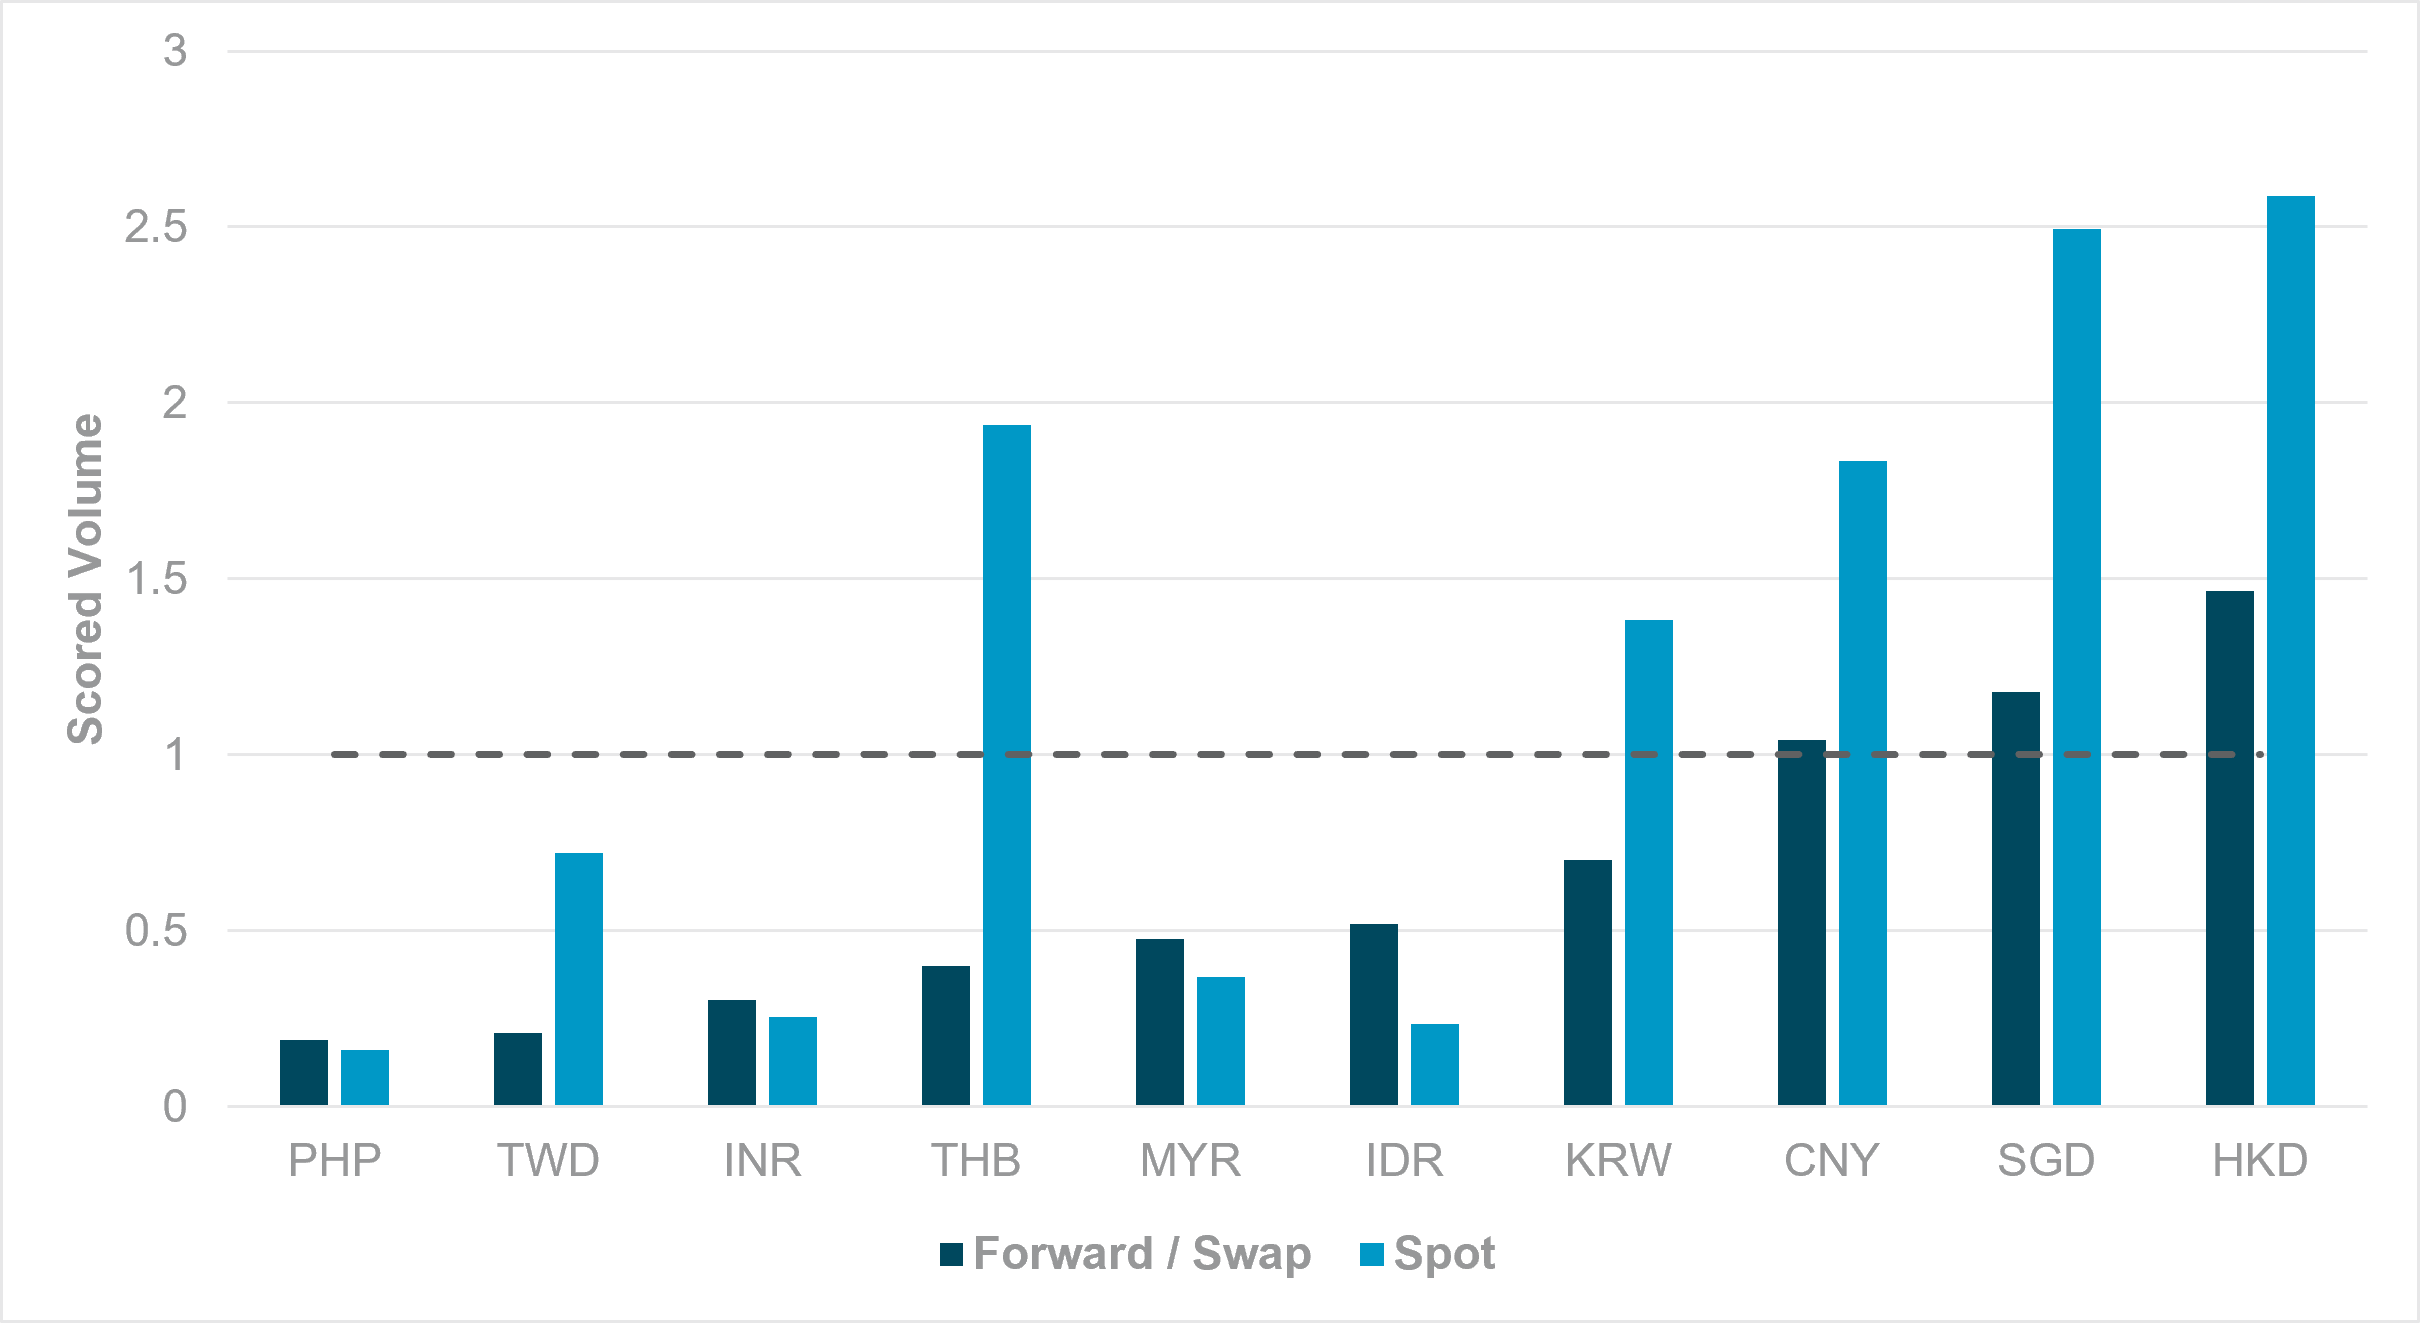
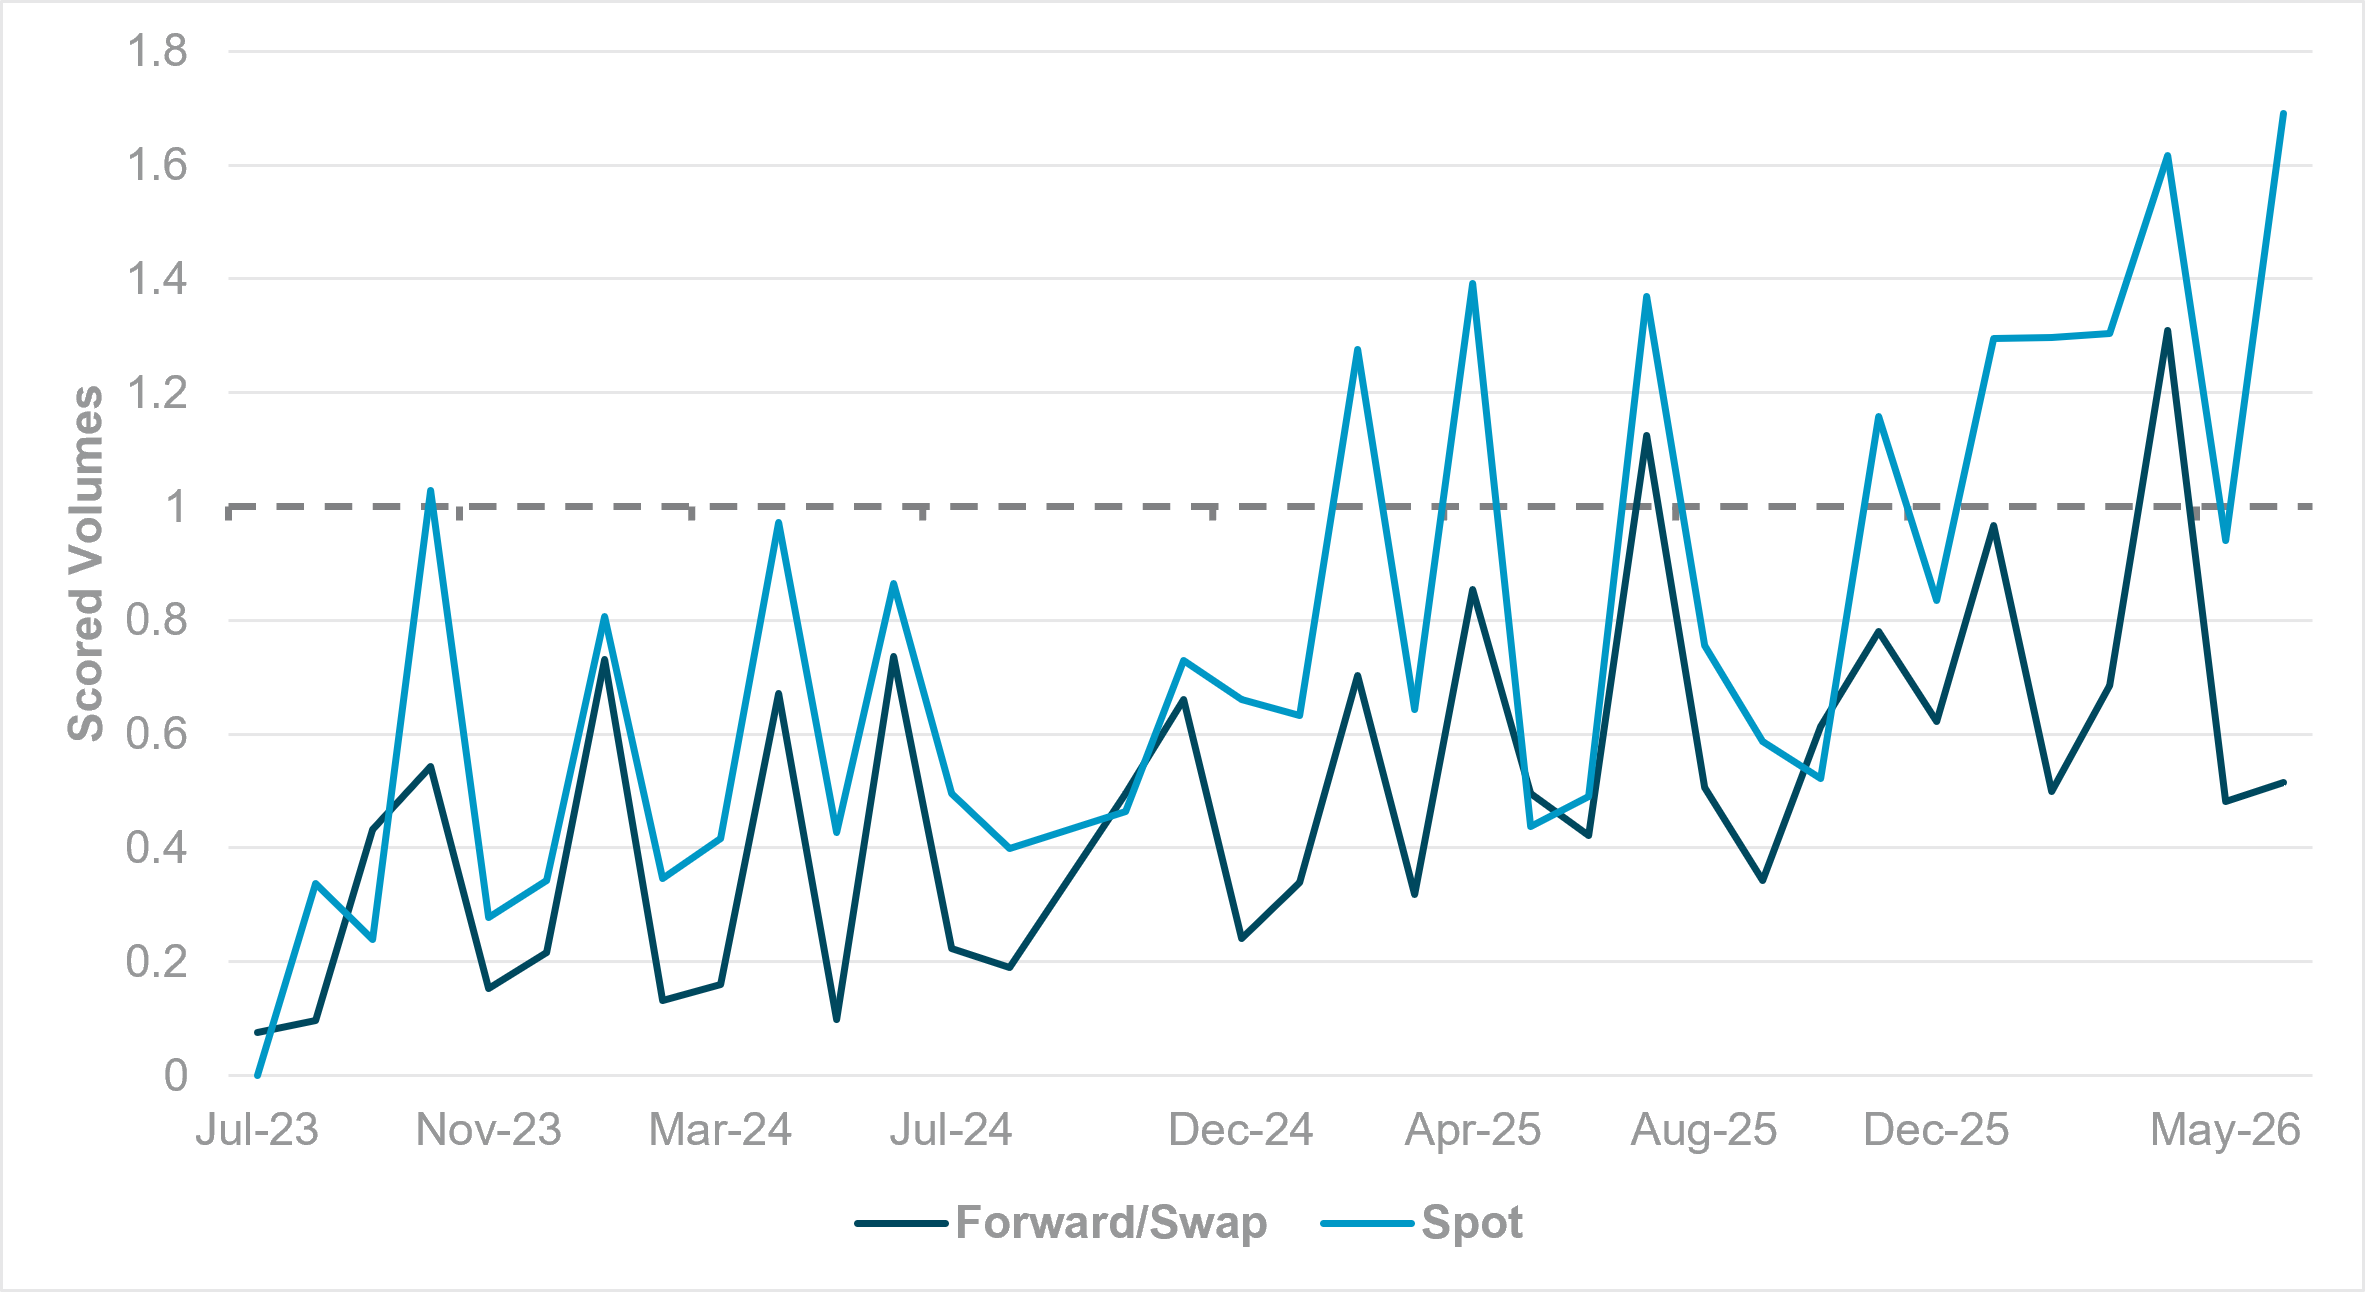
EXHIBIT #1: YEAR-TO-DATE APAC FX VOLUME SCORES, 1.0 = 12-MONTH AVERAGE
Source: BNY
Equity focus: South Korea and Taiwan
South Korea and Taiwan are standout equity markets in the first half of 2026. Both have ridden the AI and semiconductor cycle. But our flow data show institutional investors have been notable net sellers into that strength. That gap between returns and flows fits a broader pattern across Asia’s tech-heavy markets: strong performance is triggering rebalancing and profit-taking, not fresh institutional buying.
Cross-asset volumes back that up. In South Korea, KRW activity picked up sharply as the rally extended, but FX never confirmed the equity move. Despite the KOSPI rising more than 110% year to date, the won weakened by about 6% against the U.S. dollar. That points to hedging, profit repatriation and portfolio rebalancing driving the move under the surface. Taiwan looks different, with TWD activity tied more to periodic rebalancing than to outright directional equity demand. Both currencies still screen as fundamentally undervalued, which helps explain why investor interest has held up even without meaningful FX appreciation.
Who is selling
South Korea: South Korean equities saw $17.25bn of net institutional outflows year to date through June 2026. The Americas drove the move, accounting for $15.65bn of net selling, or nearly all of the global total. U.S. institutions were the biggest sellers by far, responsible for 72% of all South Korean equity sales globally year to date. The selling accelerated fast: almost half of total sales came in May and June.
Also important: The British Virgin Islands accounted for $1.6bn of selling, or almost 9% of the total. That points to liquidation by offshore hedge fund vehicles. APAC investors also sold, with $1.38bn of net outflows concentrated in Southeast Asian entities. Europe was a minor source of pressure, with just $221mn net sales, or about 1.3% of total outflows. Those exits came mainly from British, Dutch, and Swedish asset managers. Ireland-domiciled fund vehicles provided some offset, with international investor buying absorbing part of the outflow.
Taiwan: Taiwanese equities saw $1.73bn of net institutional outflows year to date. Again, the Americas were the main sellers, with $4.33bn of net sales. U.S. pension funds and hedge funds led the move, making up almost 75% of total selling from the region. But unlike South Korea, other regions stepped in to buy. APAC investors bought $859mn, led by Hong Kong-based pension funds. EMEA investors bought $1.74bn, which kept total outflows relatively limited.
The divergence matters: EMEA participated in Taiwan, but not in South Korea. European buying in Taiwan was led by Dutch and U.K. long-only investors. Luxembourg-domiciled fund buying was also meaningful, though it likely reflects broader international demand routed through local fund structures. South Korea faced more one-sided global selling pressure, while Taiwan saw stronger regional support.
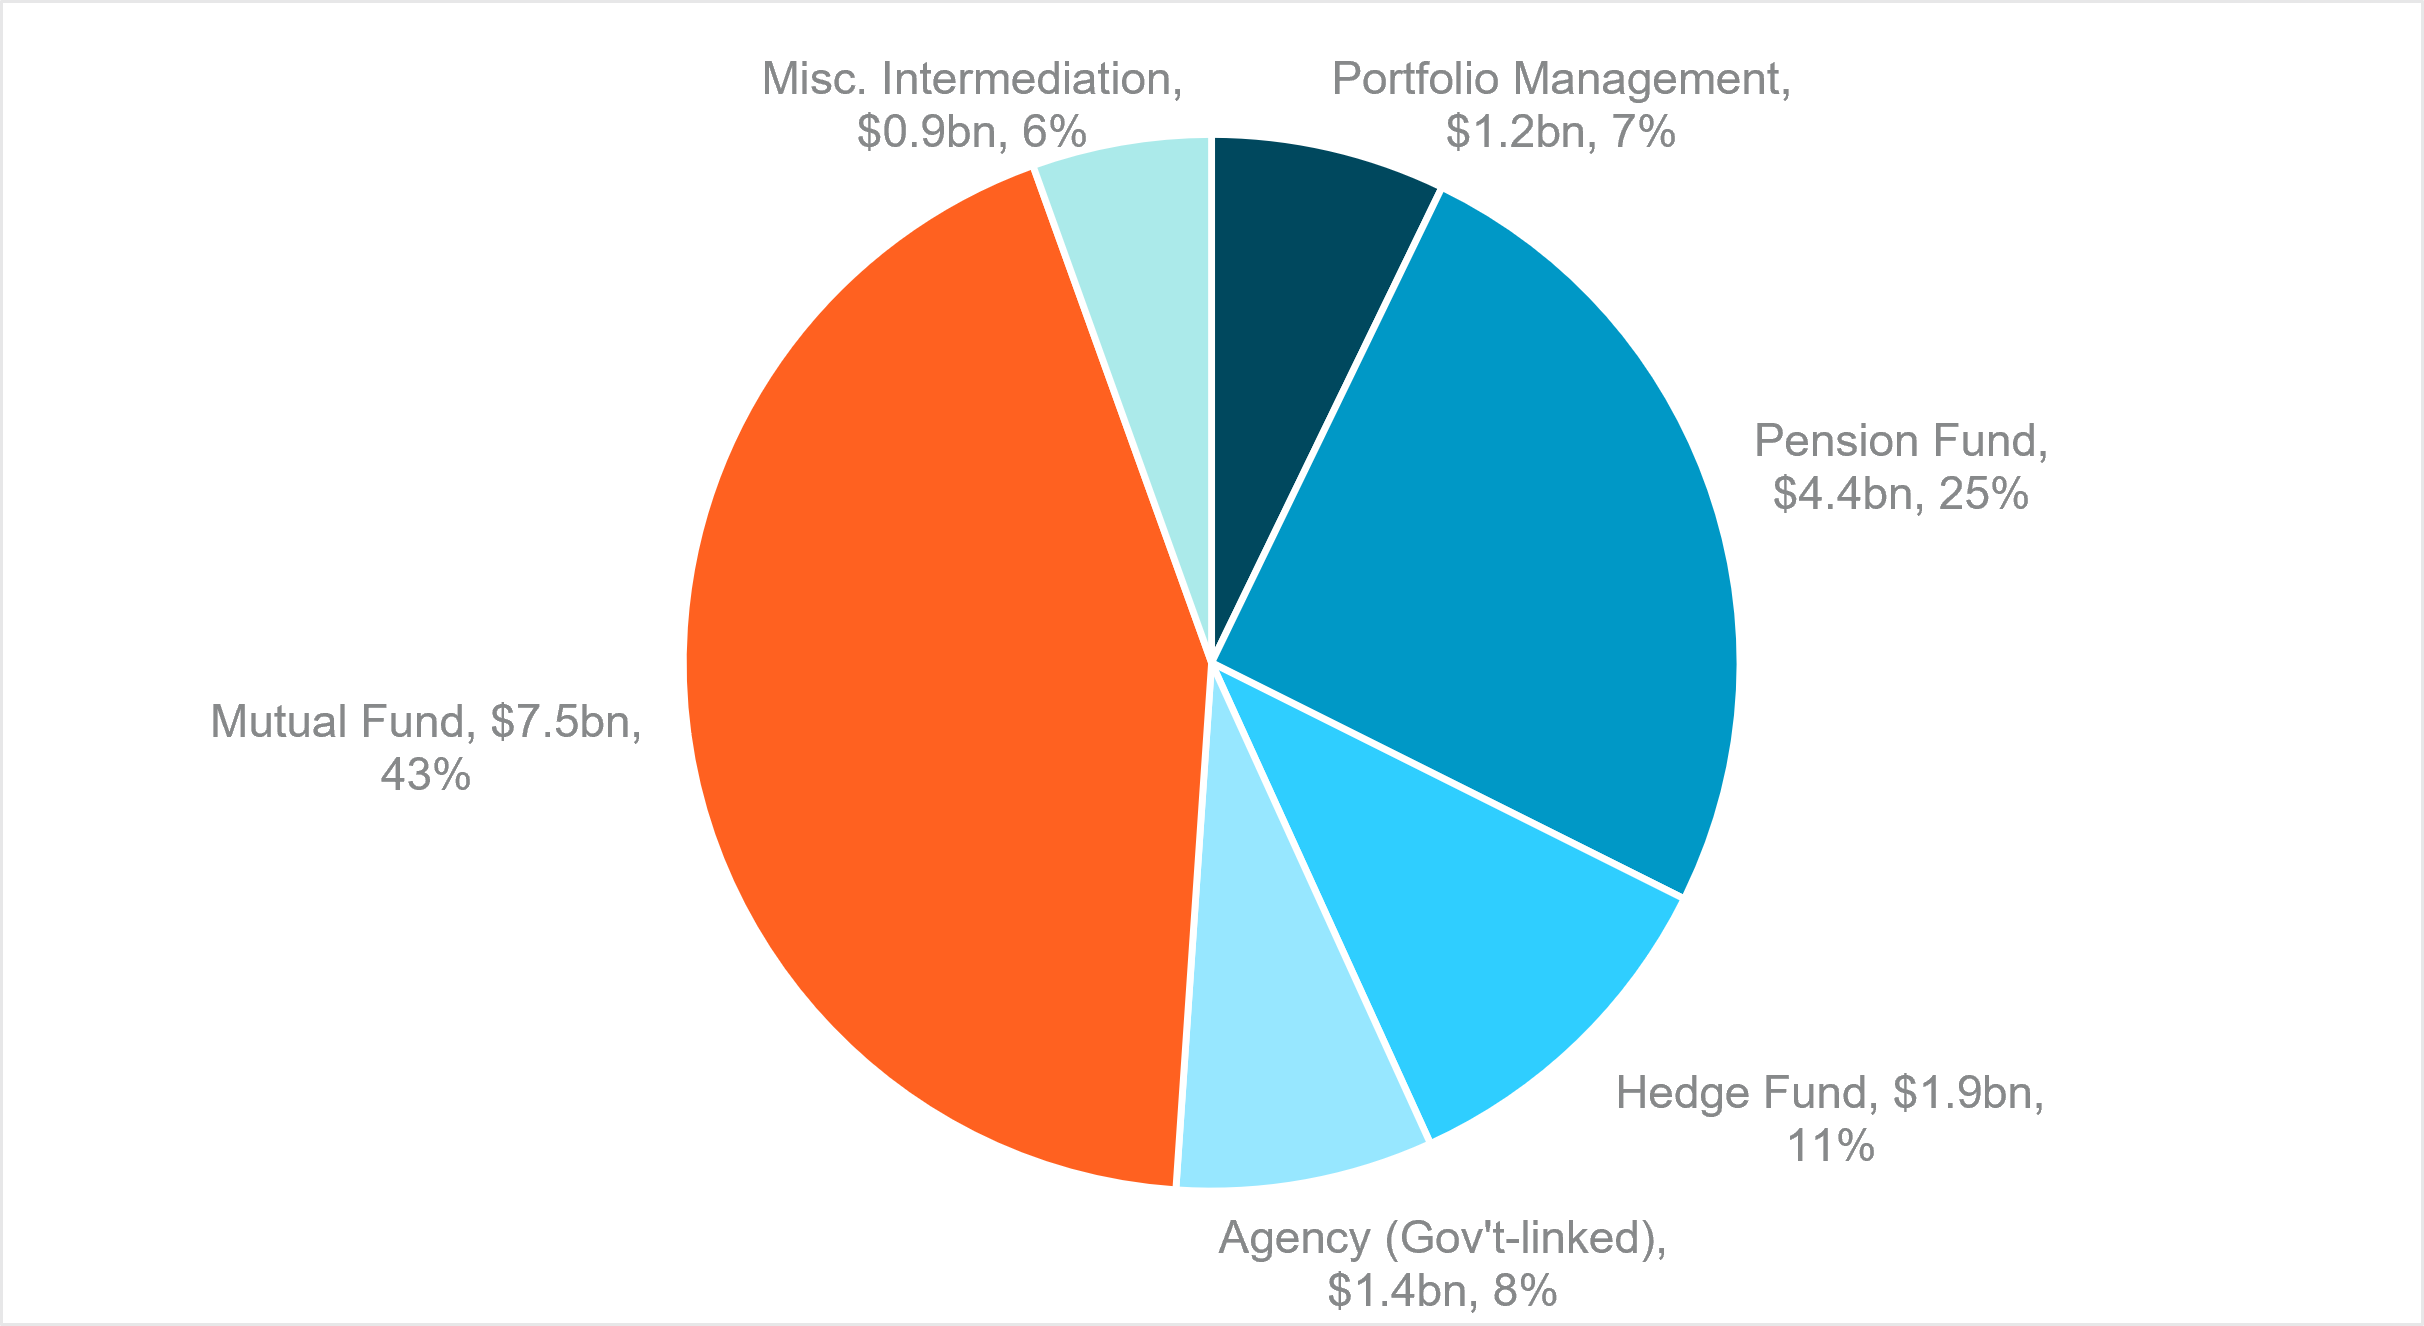
By investor type in South Korea: Mutual funds (-$7.50bn) and pension funds (-$4.35bn) were the main sellers, with hedge funds adding another -$1.87bn. That is the key signal. The selling was led by long-only accounts, which points to benchmark rebalancing and profit-taking, not a broad rejection of South Korea.
By investor type in Taiwan: The mix was different. Pension funds (-$3.12bn) and hedge funds (-$1.78bn) were the main sellers, while government and agency accounts bought $906mn. Taiwan selling was less mutual-fund driven and more concentrated in pensions and hedge funds than South Korea.
EXHIBIT #2: GLOBAL SELLERS OF SOUTH KOREAN EQUITIES, BY CLIENT TYPE, YEAR TO DATE
Source: BNY
Industry breakdown
In South Korea, selling was concentrated and decisive. Technology Hardware and Equipment (-$8.23bn) and Semiconductors and Semiconductor Equipment (-$6.13bn) made up more than 80% of total net selling. Capital Goods and Automobiles also saw outflows.
Taiwan looked more like rotation than exit. The market also saw heavy semiconductor selling (-$5.59bn), but that was offset by buying in Technology Hardware (+$3.74bn), Capital Goods (+$232mn) and Banks (+$132mn). The message: investors were not exiting Taiwan wholesale. They were rotating within the tech complex.
Positioning and FX flow dynamics
Exposure remains high. Aggregate client exposure to South Korean equities stayed high at the 78th percentile year to date. Monthly holdings just before the June 23 selloff were at the 92nd percentile versus the prior six months. Investors are still carrying strategic exposure. They are cutting and reshaping positions more actively.
Retail is the marginal buyer. Retail investors have become the key marginal buyers in South Korea. Free from ownership caps and benchmark constraints, they kept adding to AI and semiconductor names even as institutions sold. At several points over the past two months, retail demand was strong enough to force institutional investors back into key index names where capacity remained open.
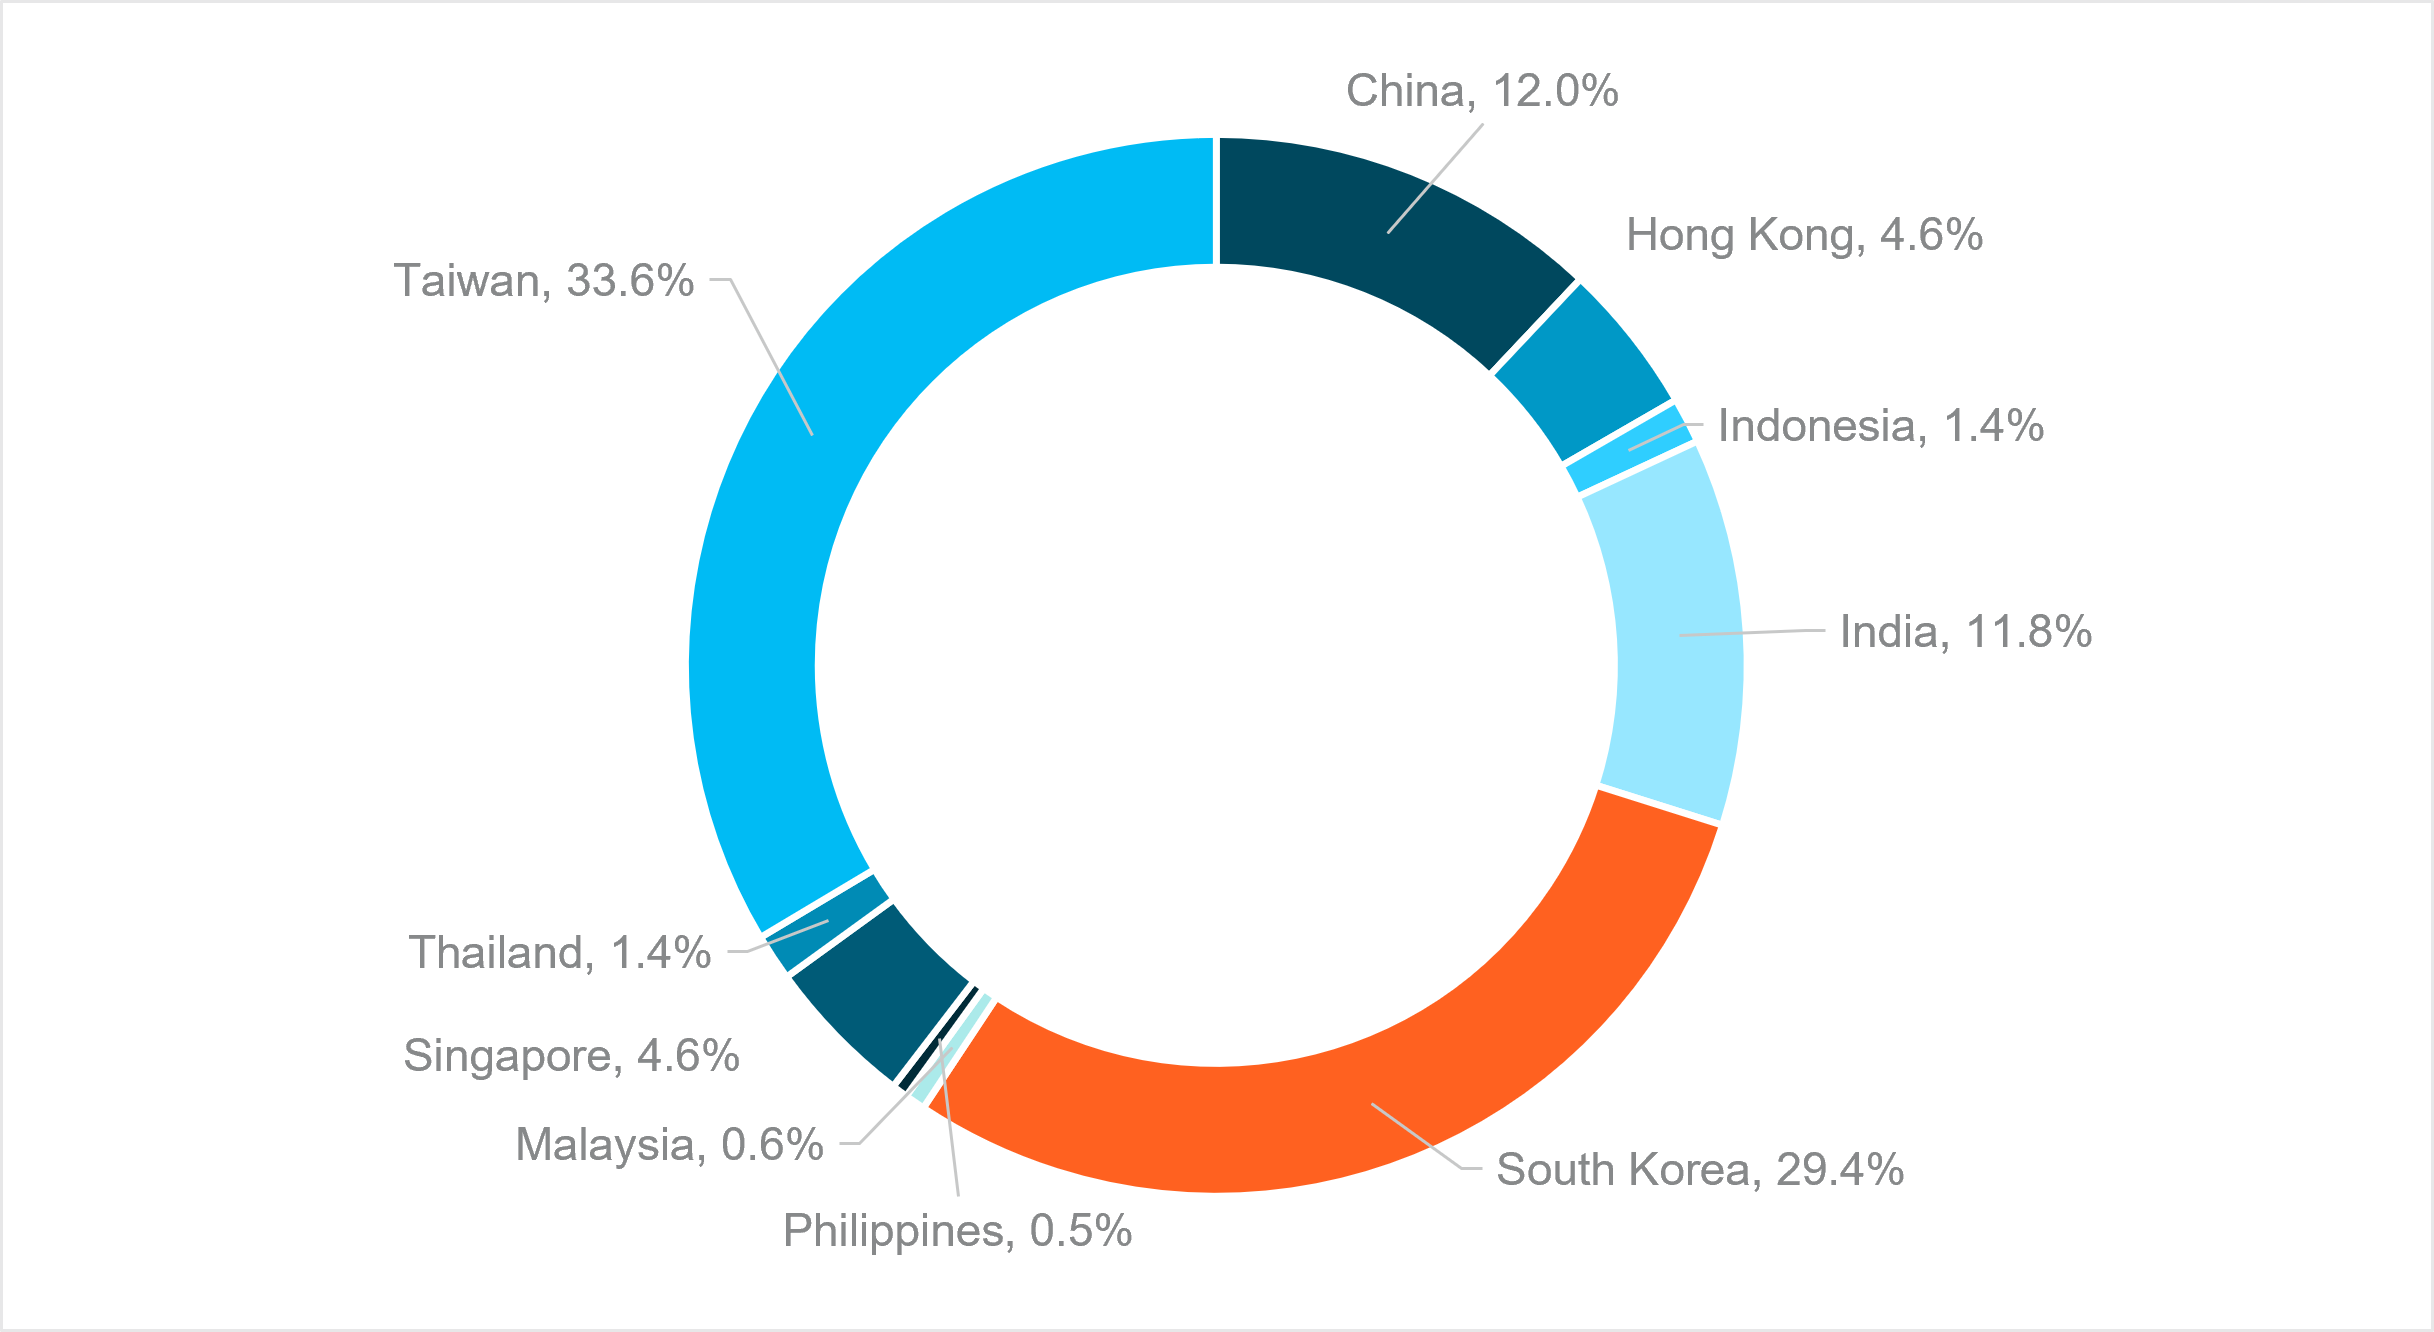
The concentration risk is rising. Even after recent outflows, South Korea and Taiwan still make up close to 4% of all equity positions in our custody base. Because these positions are heavily tied to the Semiconductor and Semiconductor Equipment industry group, combining them with U.S. names in the same group now takes that segment to nearly 14% of all global equity holdings – triple the level of three years ago.
EXHIBIT #3: SHARE OF TOTAL EM APAC HOLDINGS BY INDIVIDUAL MARKET
Source: BNY
Valuations still matter in FX and equities
The valuation case was strong coming into 2026. Investors started the year with a clear argument for unhedged exposure to North Asia. Current-account surpluses were surging in Taiwan, Japan and South Korea on the tech cycle, while China’s surplus was boosted by collapsing export prices and dominant market share. Markets also expected geopolitical pressure to push regional currencies stronger, especially as the U.S. and EU became more vocal on FX misalignments. U.S. Treasury Secretary Scott Bessent said KRW and JPY should reflect “fundamentals.” The BOJ intervened in May. That backdrop lifted activity. It did not deliver FX alpha.
CNY, TWD, JPY and KRW posted only limited gains and, as of end-May, all remained well below long-run average real effective exchange rates. Tensions with the U.S. are likely to persist, but cheap FX remains part of the attraction for equity investors.
EXHIBIT #4: NORTH ASIA CURRENCY VALUATIONS
Source: BNY, Bank for International Settlements
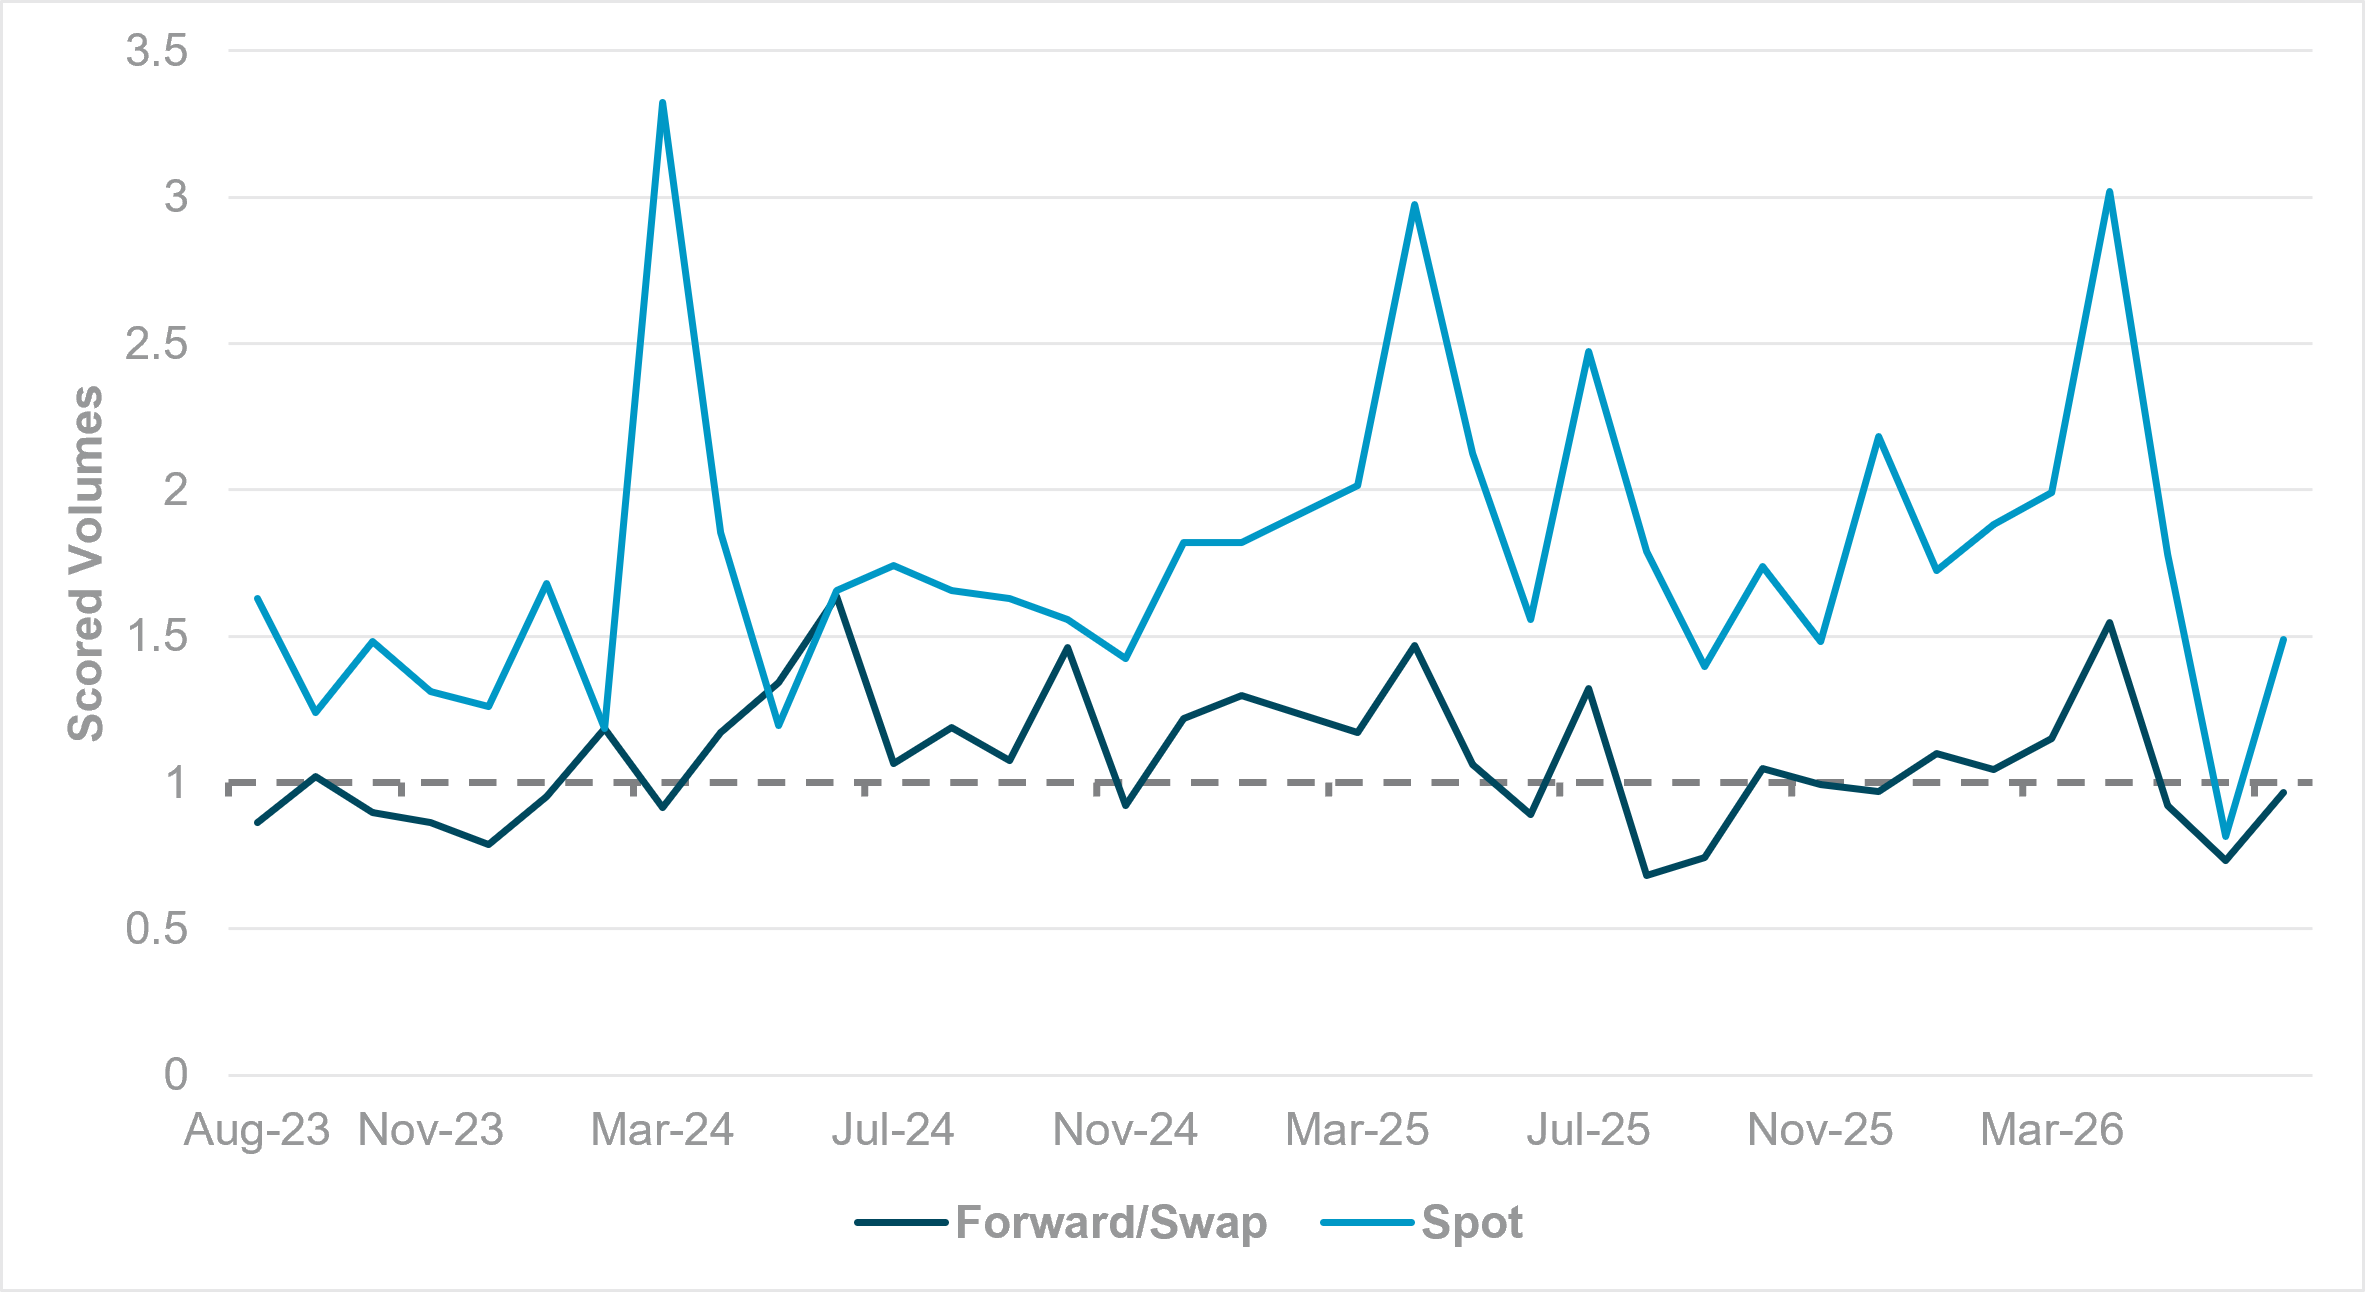
Cross-asset activity makes the South Korea story clear. In forwards and swaps, cross-border KRW FX volumes averaged 1.23x normal year to date, with nine surge days above the 2.05x threshold – almost 8% of all trading sessions. June posted the highest KRW activity of the year at 1.90x normal volume, even though the KOSPI returned just 3.6% for the month. FX activity tracked market stress and adjustment more than equity strength. The currency tells the same story. Despite the KOSPI’s 110%+ gain year to date, USDKRW rose roughly 6%, leaving the won weaker. That points to concentrated equity buying, profit repatriation and heavy hedging demand – not broad foreign inflows.
EXHIBIT #5: MONTHLY VOLUME SCORES, KRW; 1.0 = 12-MONTH
Source: BNY
Watch the marginal buyer. There are signs South Korea’s retail flow impulse may be fading. The June 23 correction, with the KOSPI down 10% on the day, along with wider weakness in global tech, is likely to increase scrutiny of leveraged retail participation. If regulators tighten rules on leveraged products, the market could lose the main force offsetting institutional selling.
Taiwan remains much quieter. TWD activity is still subdued. Spot volumes, which track equity purchases more directly, are below the rolling one-year average. Forward and swap volumes are negligible outside transaction windows such as IMM dates. That tells us active hedging by cross-border investors is still very light. Historically, TWD turnover has shown only a weak relationship with TAIEX performance, and spikes in activity tend to line up more with rebalancing around IMM windows. There is a clear pickup in volumes over the last 12 months, but it is still far less pronounced than in South Korea.
China stands apart. The contrast with North Asia’s semiconductor markets is sharp. CNY, SGD and HKD have seen the biggest jump in transaction levels relative to the 12-month average, and that is reflected in equity volumes as well. China shows how much valuations matter, even in a bear market. Major China indices are down close to 20% from year-to-date highs and more than 12% below their 200-day moving averages. The market is deeply oversold. Yet valuations remain undemanding, with the Shanghai Stock Exchange on 17.6x trailing P/E and the HSCEI on 11.3x.
EXHIBIT #6: MONTHLY VOLUME SCORES, CNY; 1.0 = 12-MONTH AVERAGE
Source: BNY
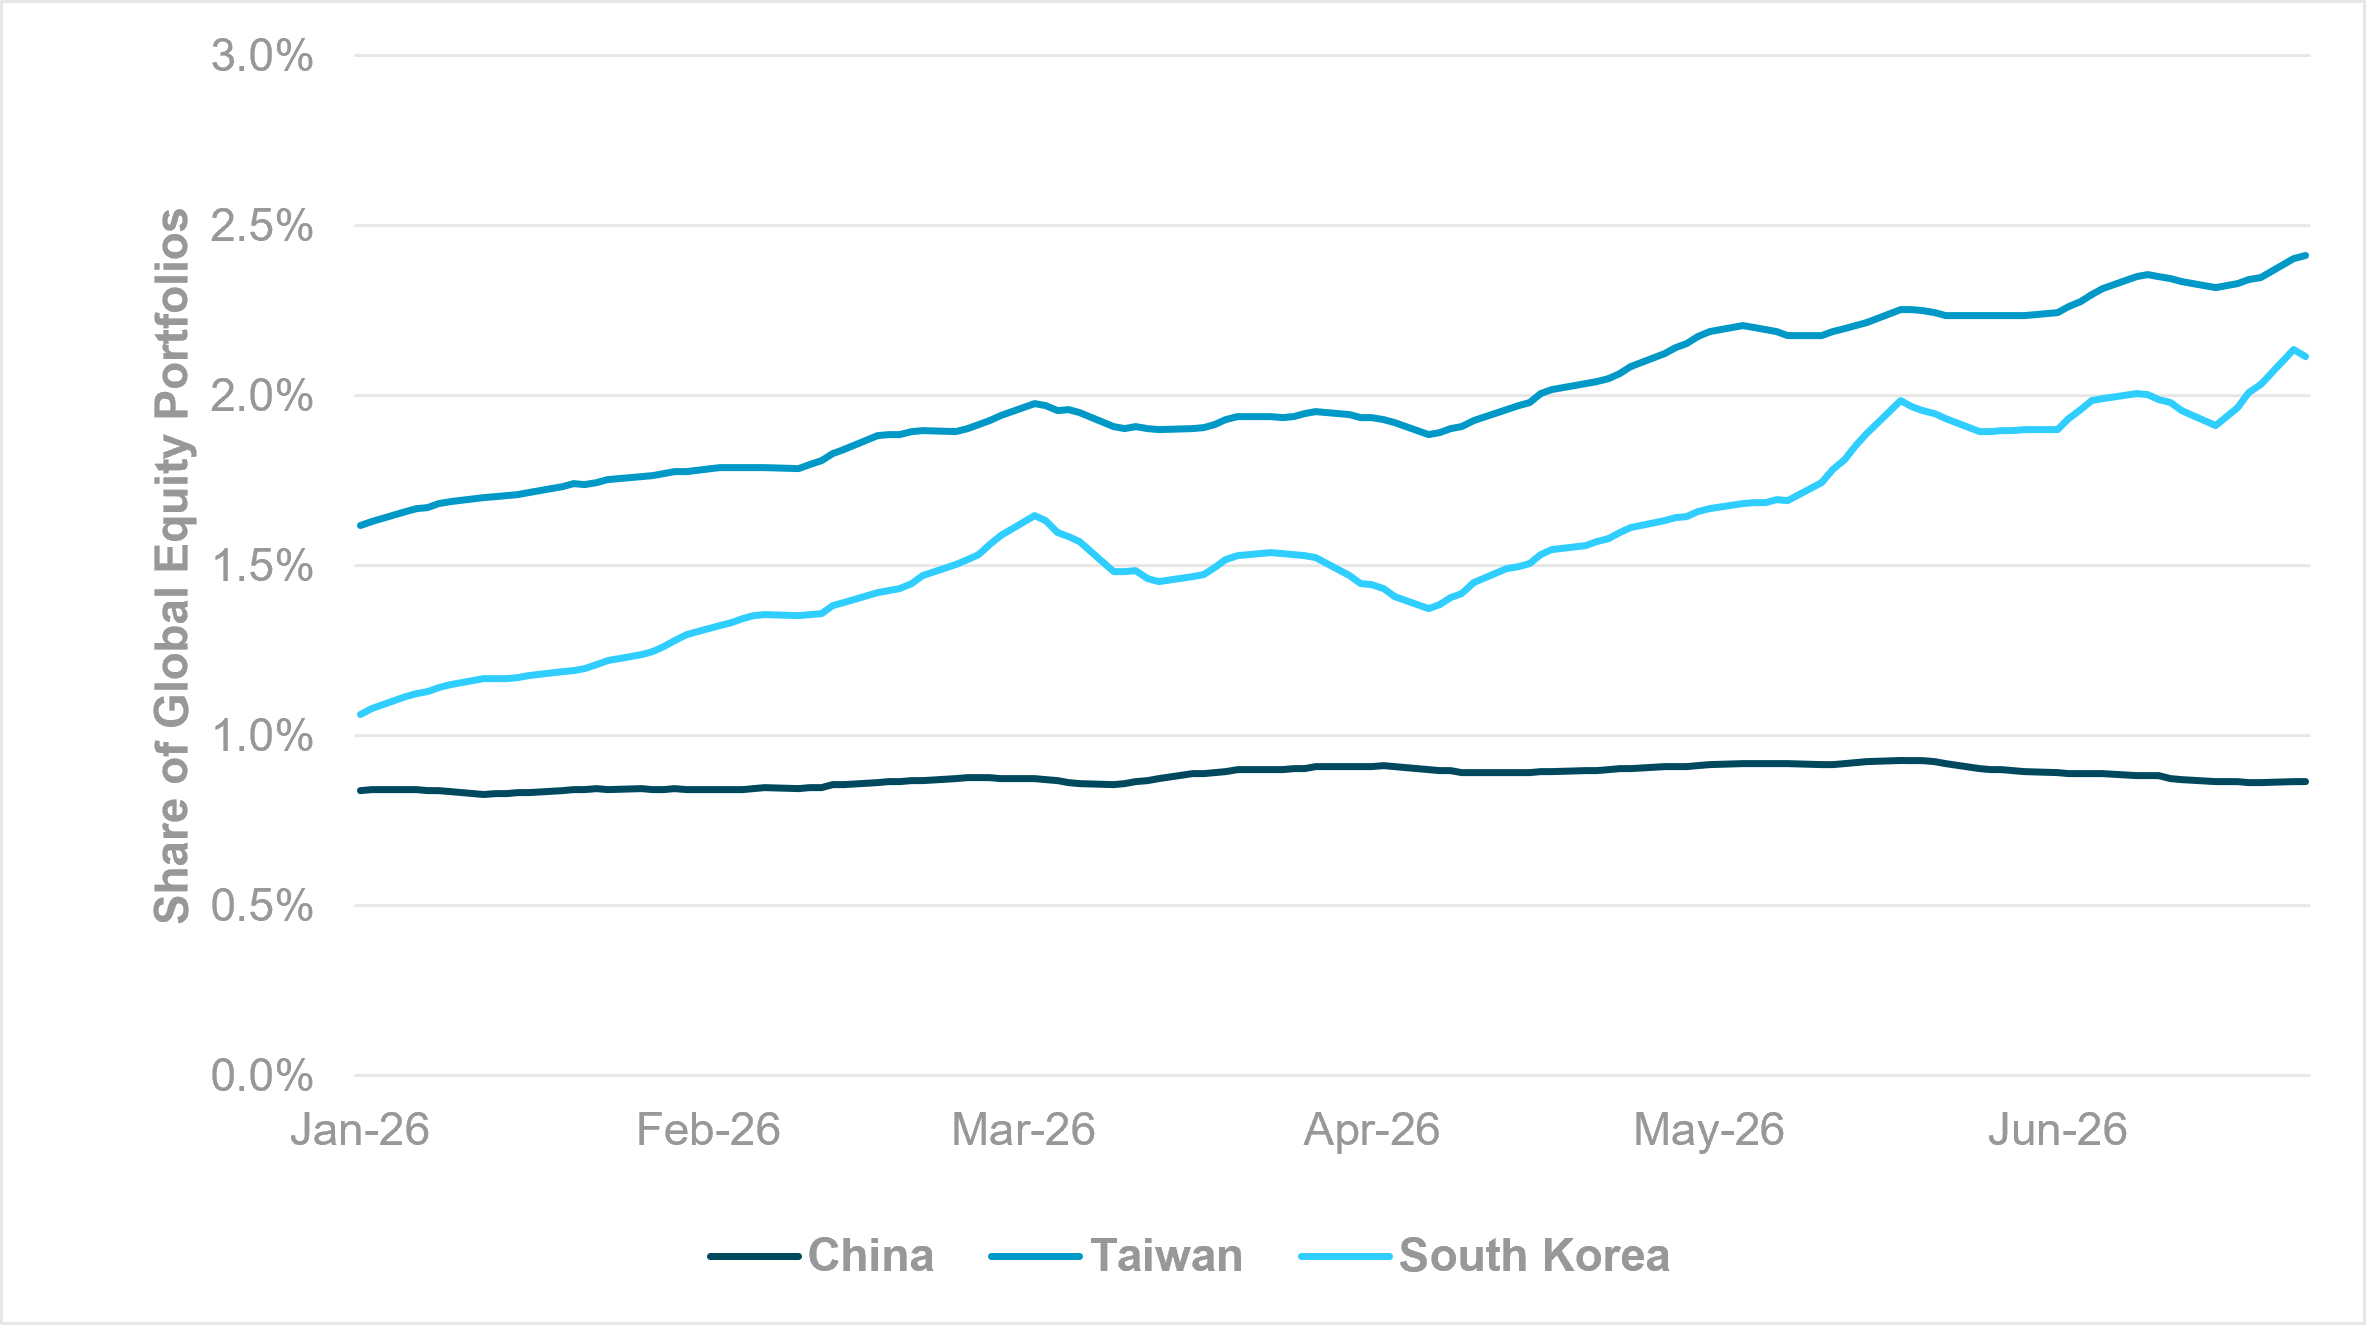
That’s starting to pull buyers back in. For many institutional investors, the selloff has gone further than any change in the long-term thesis. That is supporting buy-the-dip behavior. CNY spot flows are running 81% above the rolling one-year average on a weekly smoothed basis, and March 2026 ranked as the sixth-highest month on record, in the 97th percentile of data back to 2012. Cumulative institutional flows into China have reached $4.5bn by end-June. With client positioning in China at just 0.86% of global portfolios – barely 20% of South Korea and Taiwan combined at 4.42% – the case for a valuation-driven rotation is building.
EXHIBIT #7: CHINA, TAIWAN, SOUTH KOREAN EQUITY MARKET POSITIONING AS SHARE OF GLOBAL EQUITY HOLDINGS
Source: BNY
EM APAC fixed income: balance of payments still matters
Bond market activity has surged. FX still has not followed. That is the key message. Net flows into China, the region’s largest market, are flat. EM APAC overall has also seen net selling in a weak risk and carry backdrop. Cumulative flows for the whole region are just $3.5bn – a fraction of the outflows from South Korean equities alone. Weakness in Chinese government bonds over the past two years shows how much nominal and real yields still matter. Big macro events, from Liberation Day tariffs last year to the recent conflict, have triggered talk of CNY and CGBs as alternatives to the dollar and Treasurys. Investors are not buying that story, and Beijing is not pushing it.
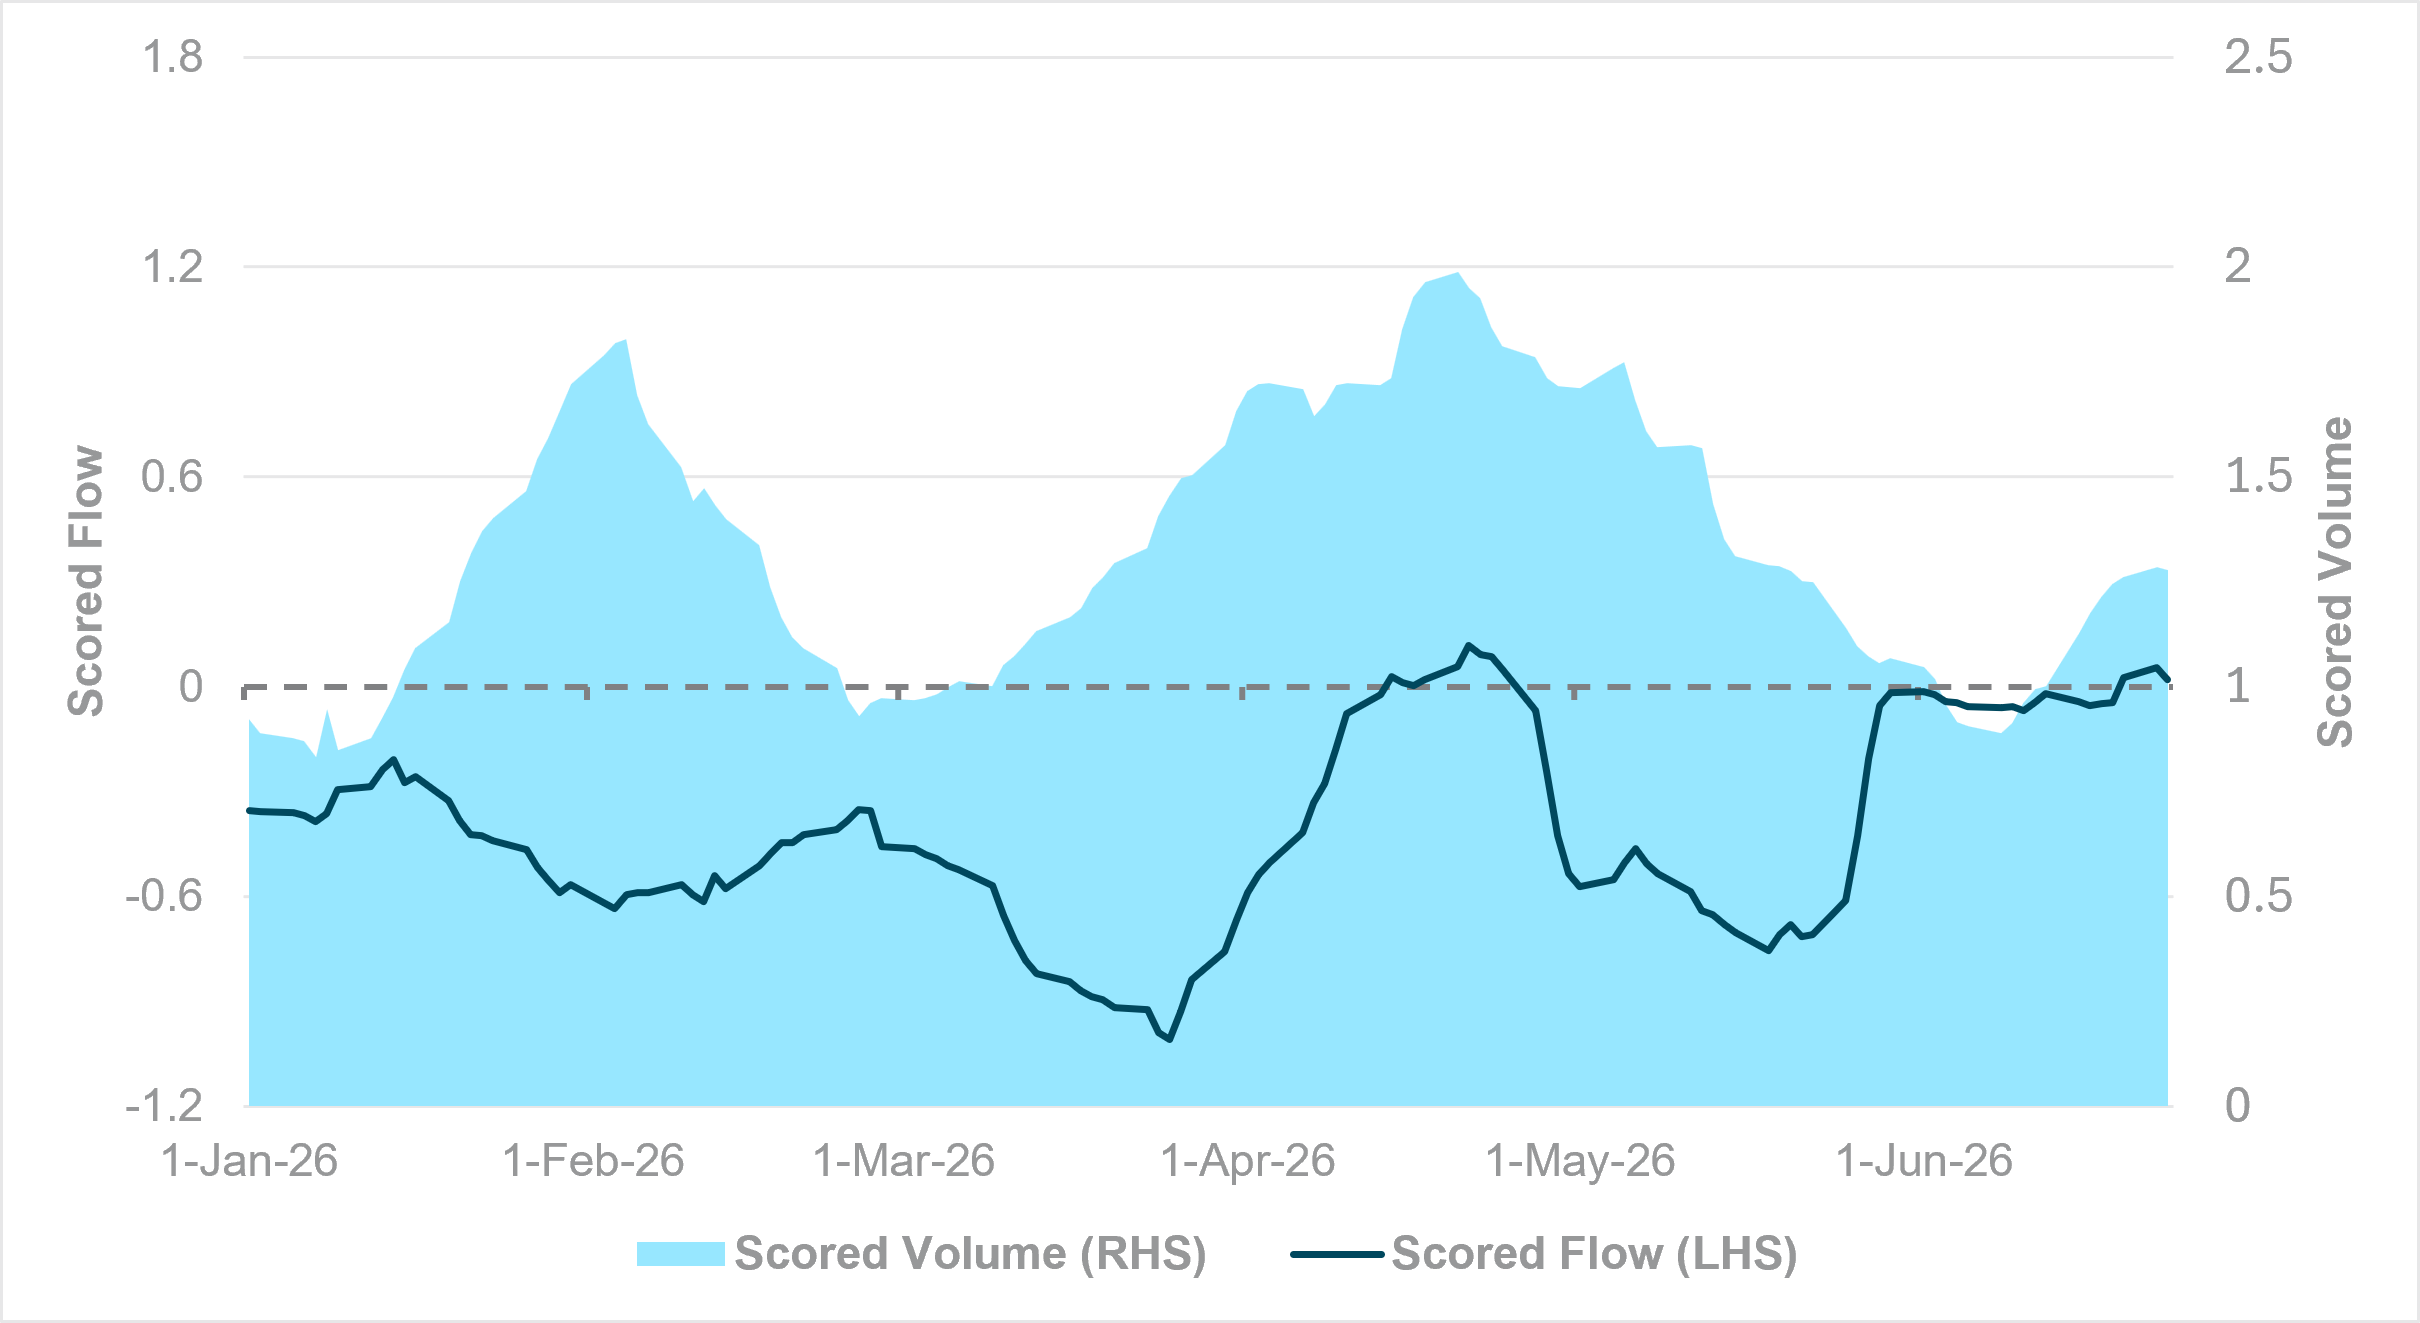
The timing of the volume spikes matters. Daily sovereign bond volumes in EM APAC are running 40% above the rolling one-year average year to date. There have been two major waves. The first came in January, when holdings were cut sharply as investors rotated into Latin American fixed income for carry. The second, and biggest, came around end-March to early April. By then, the most intense phase of the conflict had passed, and markets were starting to price a ceasefire. At a 2.54 volume score on a weekly average basis, that was the highest reading since March 2022 and the 97th percentile of history back to 2017. Net flows also moved close to positive during that relief rally and marked the best buying point of the year. More recent flows have improved in net terms too, but sovereign bond volumes are now much weaker.
EXHIBIT #8: EM APAC SOVEREIGN BOND FLOWS AND VOLUMES (1.0 = 1Y AVERAGE)
Source: BNY
Indonesia: one of the few clear cross-asset signals
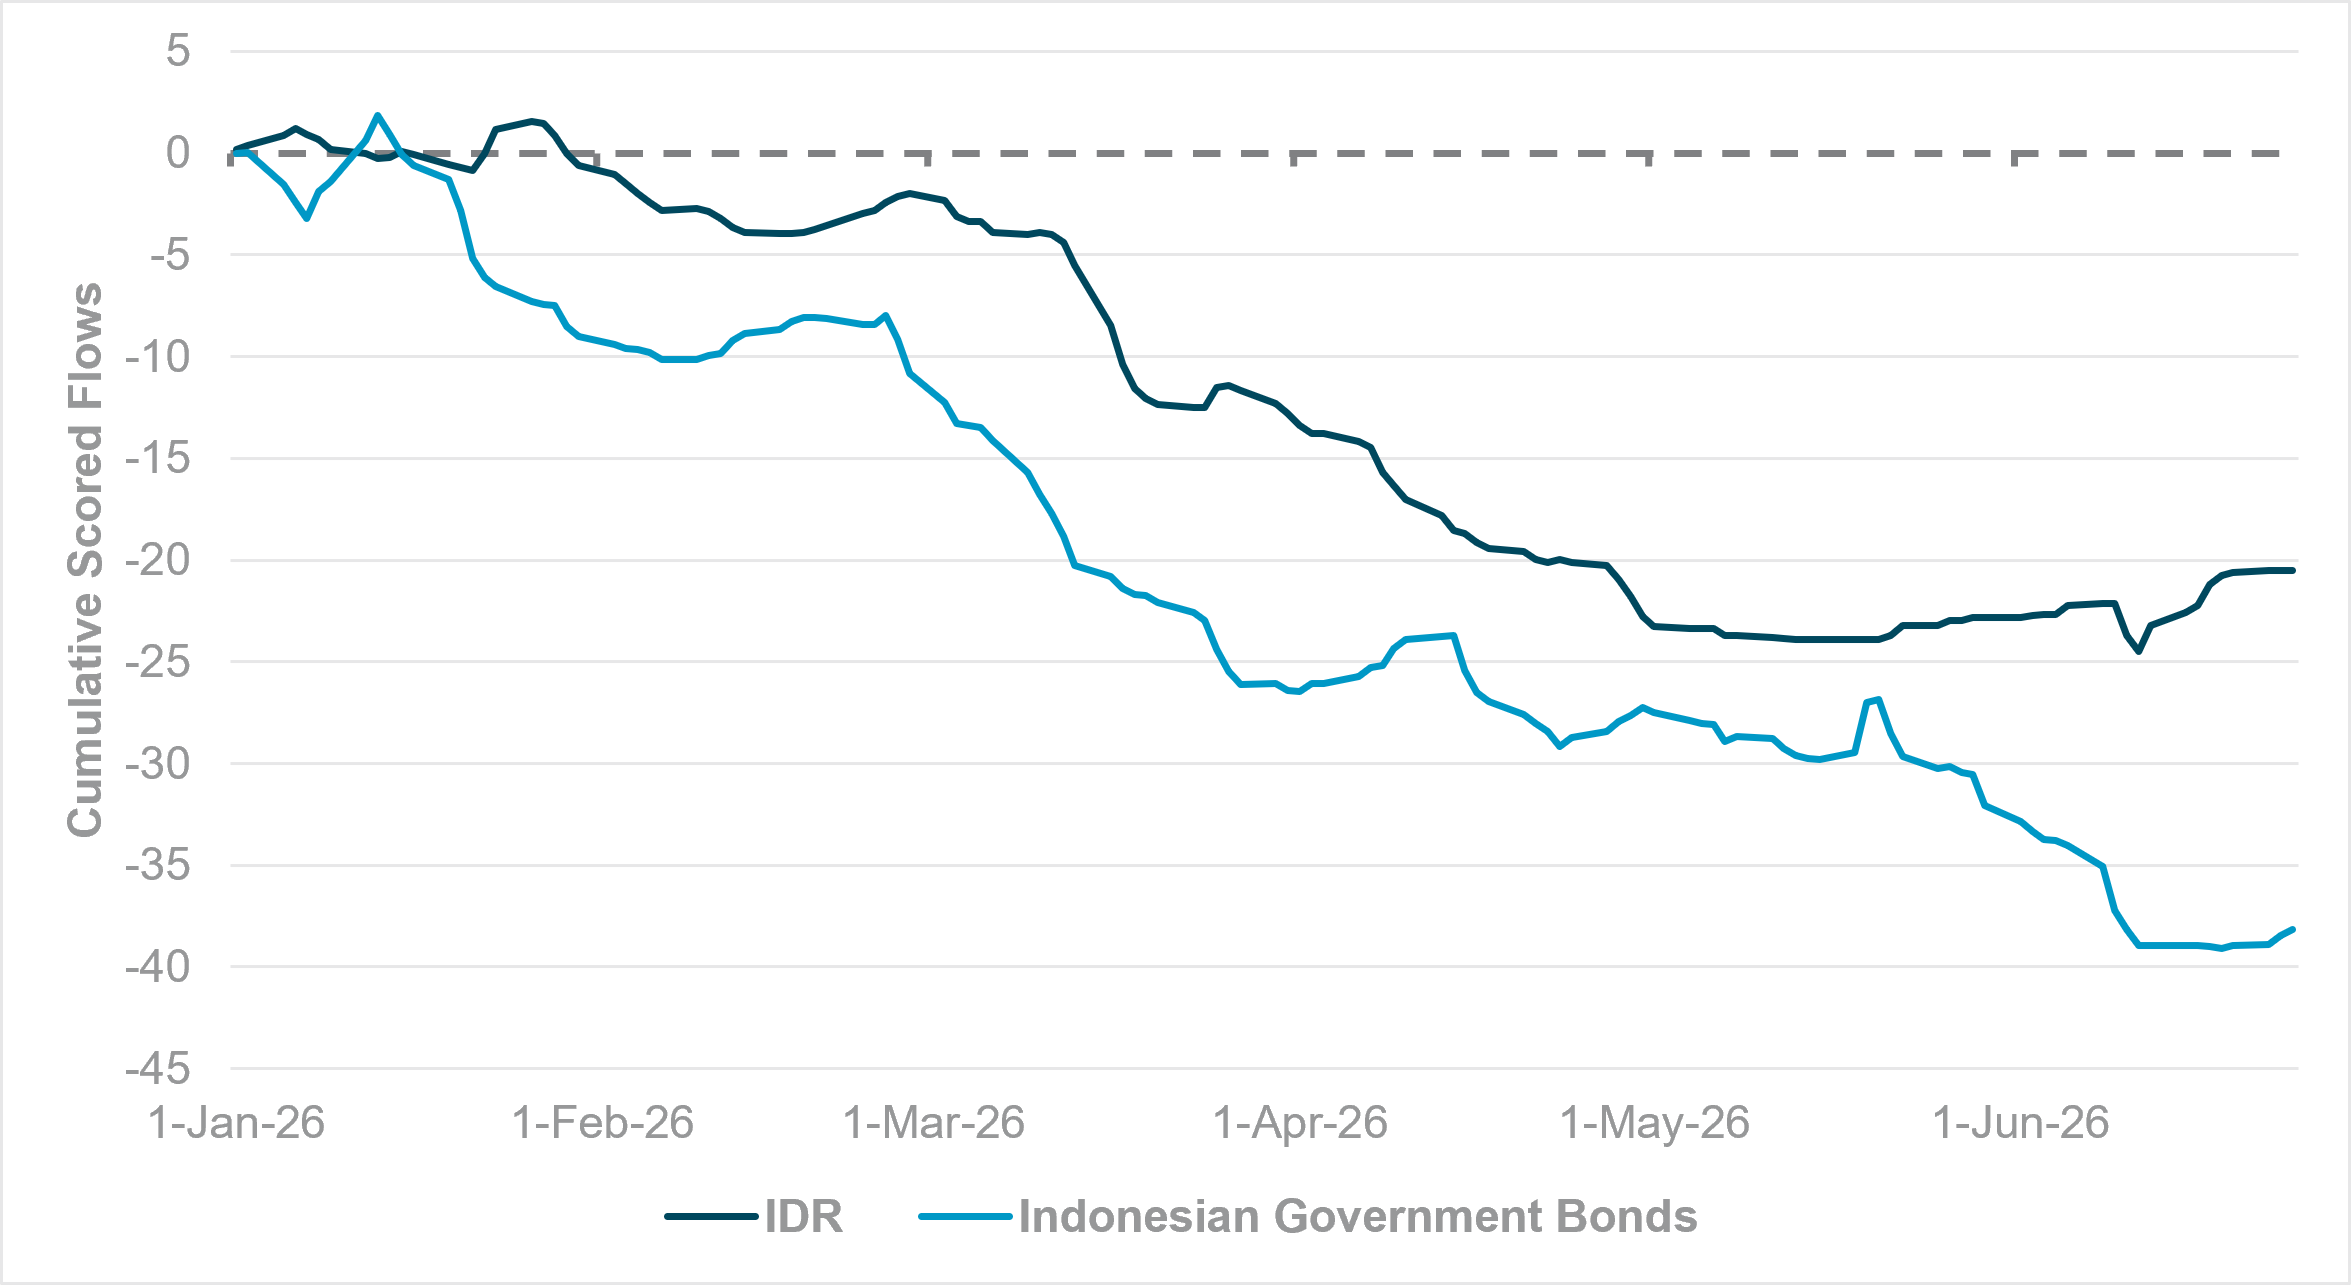
Indonesia is one of the cleanest signals in the region. FX and fixed income lined up. Fiscal concerns worsened balance-of-payments stress in March, making that the biggest outflow period for both sovereign bonds and IDR. Our data tracked more than $200mn of outflows in March alone, close to 50% of total Indonesia outflows year to date. Hedge ratios on these carry-driven trades are limited because they are expensive, so FX flows were smaller in size. Since late May, some divergence has emerged: FX flows have stabilized even as IDR bond flows continue to worsen. Our iFlow Carry index suggests FX carry liquidation is running out of steam, helping IDR recover. That leaves a better tactical opportunity in FX than in sovereign credit or duration.
EXHIBIT #9: CUMULATIVE SCORED FLOWS, IDR AND INDONESIAN SOVEREIGN DEBT
Source: BNY
Bond volumes are up. FX still is not confirming
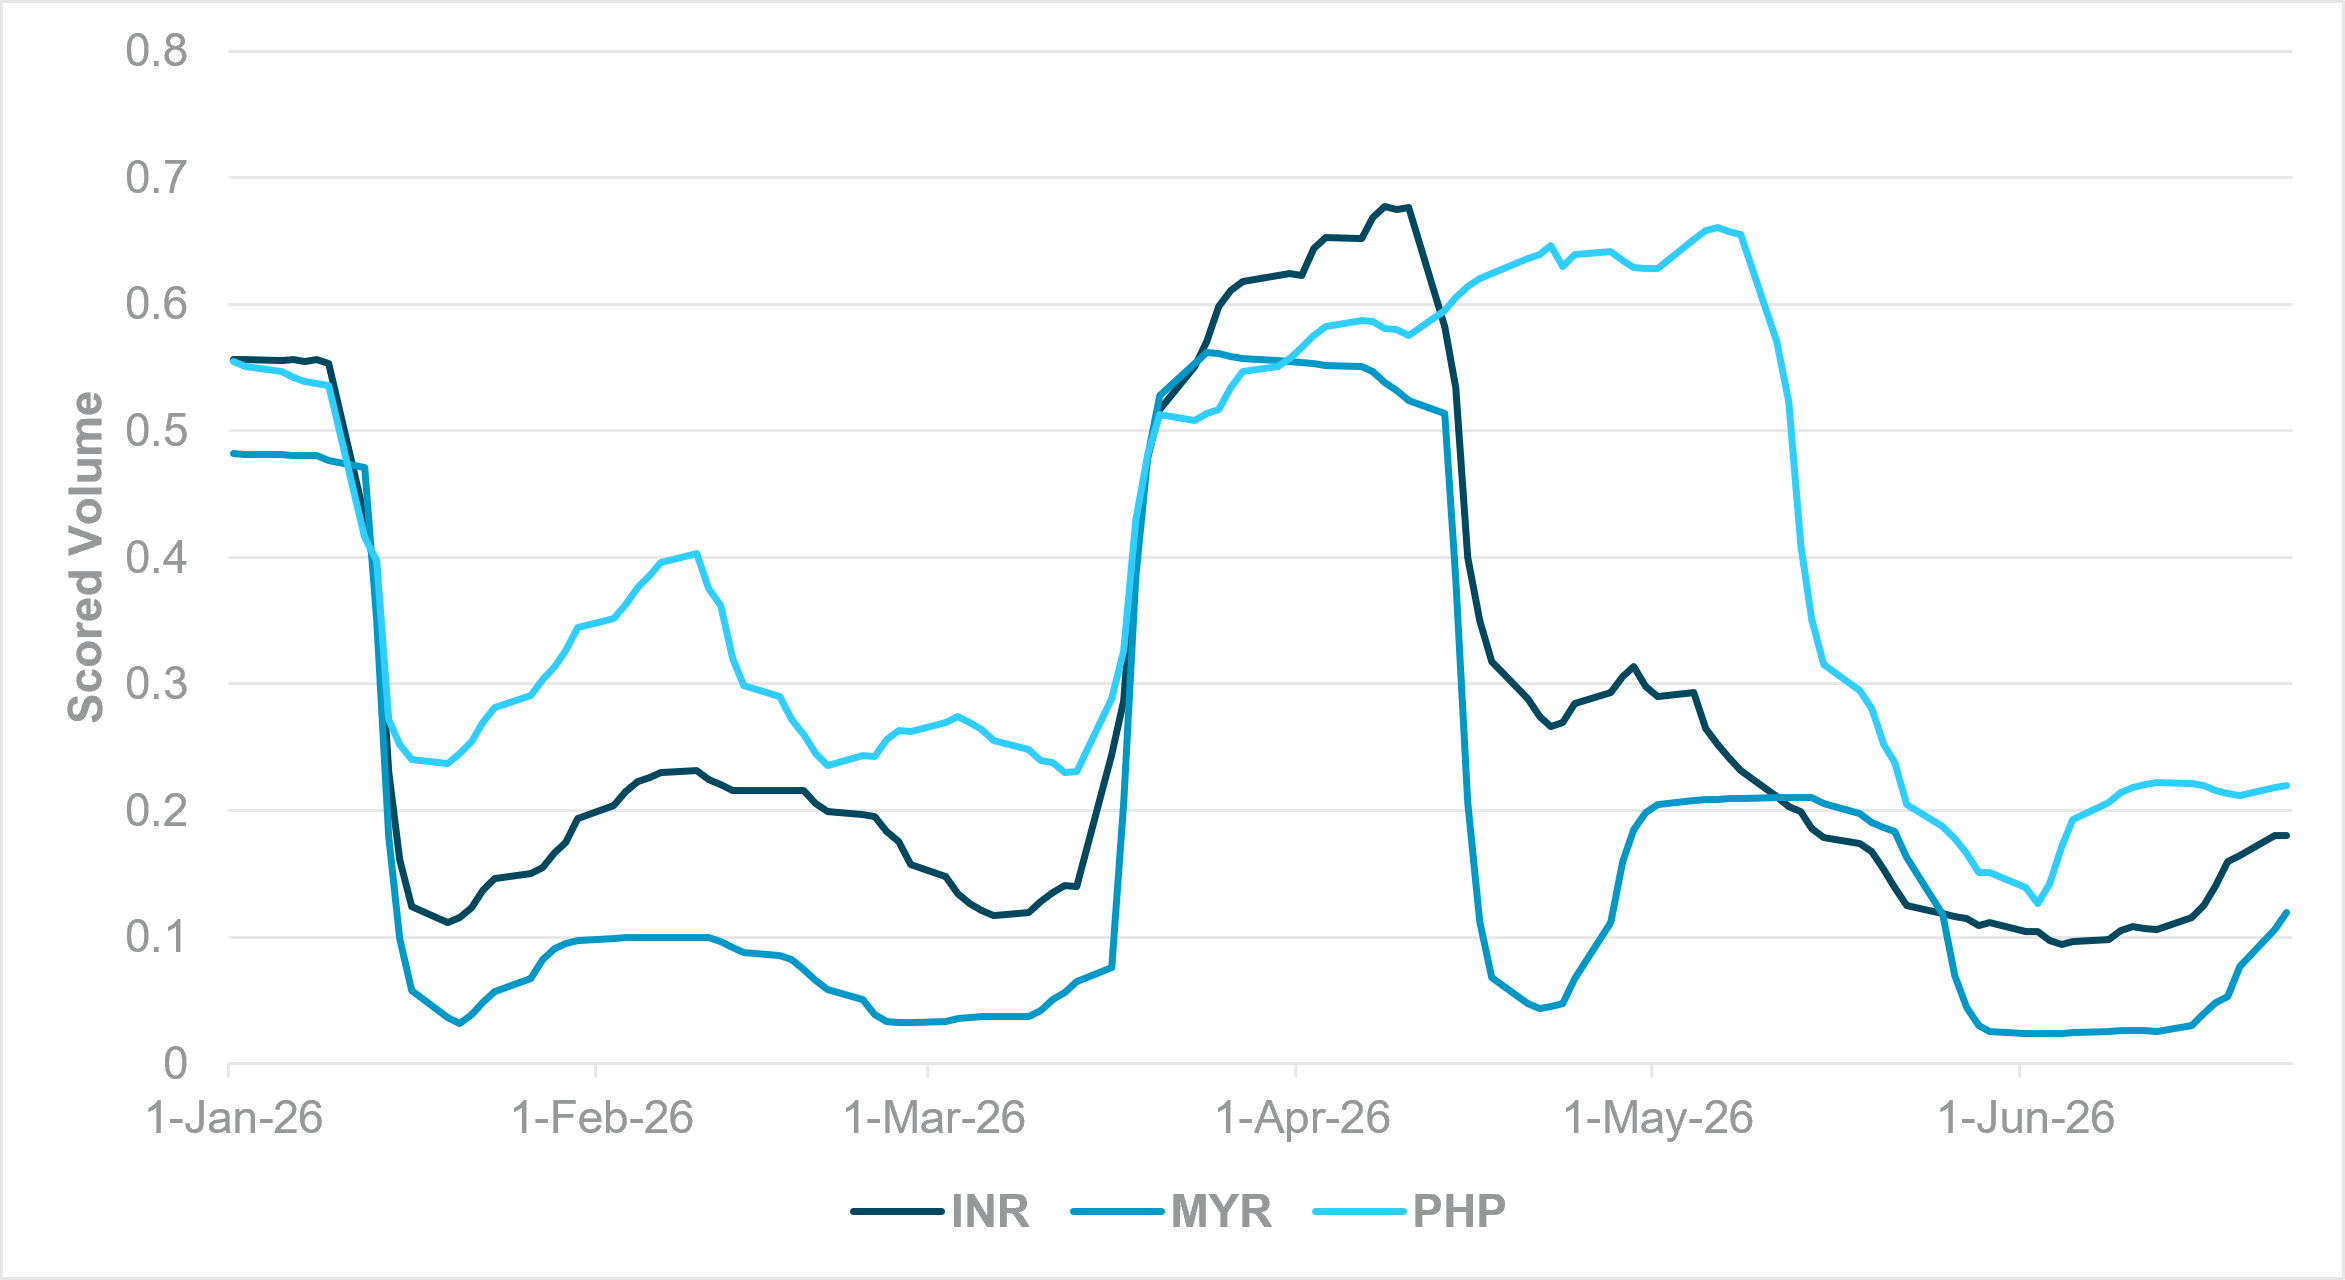
This is the point investors need to act on. Strong bond market volumes have not translated into strong FX volumes, especially in countries most exposed to the conflict. INR, MYR and PHP all saw FX volume jumps in late March and early April alongside higher bond activity. But even then, none came close to rolling one-year average FX volume levels. Current flows are weak, with monthly flows at 20% of the one-year average or lower. IDR is even weaker: year-to-date average volume is just 0.53 in forwards/swaps and 0.23 in spot.
EXHIBIT #10: SELECT EM APAC FX MONTHLY SMOOTHED VOLUMES (1.0 = 1Y AVERAGE)
Source: BNY
High volume is not the signal. Intent is the signal. Across APAC, elevated activity is often telling us investors are managing risk, taking profit and rotating exposures – not putting fresh capital to work. That is most obvious where flows, volumes and prices are moving in different directions.
Focus on divergence, not headlines. Treat South Korea and Taiwan as position-management stories, not clean momentum trades. Watch closely for any fade in South Korean retail support. In China, keep tracking whether valuation-driven rotation broadens. In EM rates, do not assume bond turnover means currency support is coming. Use iFlow to separate conviction from redistribution of risk.